

Frontier tech, longevity, investing, and the future of being human. I write about it two ways: nonfiction (One-Person Empire) and sci-fi (Age of Unbounding).
USA and Rio de Janeiro
Joined April 2009
- Tweets15.9K
- Following722
- Followers835
- Likes2K




Pinned Tweet
In June, investors at US brokerages owed $1.06 trillion more than the cash in their accounts.
The lowest reading in the history of the data.
I wrote a book on what leverage like this has meant before, and made a dated call.
Free until Dec 31. Link below.

Anthropic priced its IPO at $83. That is about $1.5 trillion for a company with one profitable quarter on record.
I read the S-1 cover to cover and ran $ANT through Michael Burry's Scion Capital checklist. Here is what the filing says, good and bad.
THE GROWTH IS REAL
- Revenue: $41M in 2023, $386M in 2024, $4.6B in 2025
- First nine months of 2026: $33.2B
- Q2 2026 was the first operating profit: $974M, an 8% margin
- Operating cash flow turned positive: $3.9B in the first half
- Customers spending $1M+ a year: more than 1,900
- About 5,300 employees, $6.6M of revenue each
THE PRICE
- About 43x trailing revenue
- About 18.5x the reported $81B run rate
- The last private round, in May and June, was $58.90 a share split-adjusted. The IPO is 41% above it.
- Burry's form wants a 50% discount to value. That needs a $3 trillion business.
THE COMMITMENTS
- $265.6B of minimum purchase commitments
- $321.4B of leases signed but not yet started
- $266B more signed after June 30
That is about $853B, more than ten years of today's run rate. The counterparties are Amazon, Google, Microsoft, Broadcom and AMD, who are also investors, and some are customers.
THE DILUTION
- $6.2B of Amazon notes convert into 1.84B shares. At $83 those are worth about $153B.
- $26.6B of stock unit expense has not hit the income statement yet
- A further $5.8B of stock units was granted after June
- 5% of the company went to a public benefit fund, and the board can issue up to 2% more each time the stock rises 50%
THE CONTROL
- One founder share carries 50.1% of the vote
- A five-seat trust elects the board majority
- Public Class A holders are capped at 49.9% combined
THE FINE PRINT
- 48% of revenue runs through cloud marketplaces
- 5% to 7% of revenue came from customers violating its usage terms
- $1.5B copyright settlement, more suits pending
- Auditor changed in October 2025
- First-half net loss of $80.7B, of which $72.4B is a non-cash markup on convertible notes
VERDICT
The fastest revenue ramp I have seen in a filing, priced as if the next decade is already banked. On Burry's form it is a pass at $83.
What would you pay for it?
Not investment advice.

1
62
$AMD at $522. I ran it through Michael Burry's Scion Capital analysis template, the checklist he filled out before buying anything. Here is what the form says.
THE PRICE
- Market cap: about $856B
- 121x trailing free cash flow
- 18.8x sales
- About 34x 2027 consensus earnings
Burry's form demands a 50% discount to value. To qualify at this price, AMD would have to be worth about $1,044 a share. That is a $1.7 trillion company.
THE CASH
- Q3 net income: $2.4B, up 95%
- Q3 operating cash flow: $1.2B
- Cash covered 49.5% of reported earnings
- Inventory up 57%, revenue up 45%
- Days of inventory: 149 a year ago, 170 now
THE WARRANTS
OpenAI and Meta each hold warrants on up to 160M AMD shares at $0.01. Together that is 320M shares, 19.5% of the share count. They vest as the two companies buy GPUs and as the stock climbs. AMD is paying its biggest AI customers in AMD equity.
THE EARNINGS GAP
- Non-GAAP net income runs 43% above GAAP
- GAAP itself got a $555M tax benefit
- $1.5B went out in one quarter to buy back stock for employee tax withholding. It sits in financing, so free cash flow never sees it.
THE OTHER SIDE
Q4 is guided to about $17B. Management expects revenue to grow more than 80% in 2027. Gross margin is 53.9% and rising. Most of the inventory build is work in process ahead of the ramp, and finished goods fell.
THE VERDICT
Strong business, no margin of safety. On Burry's own form this is a pass. Shorting it is a separate bet: estimates are rising, and the stock moved 45% in five trading days this month.
Which number matters more to you, the 121x or the 19.5%?
Not investment advice.
1
40
Bought for $2.6M on $190,000 of income. Two years of good management lift it to $281,000. At a 7.3% cap rate, that's a $3.85M facility, about six hours a week.
Don't buy the occupancy. Buy the town around it.
The Self-Storage Handbook: amazon.com/dp/B0H7SW8SSG
16
$APP just ripped +30% on a “beat.”
The numbers looked strong on the surface. The setup for the next 1–2 quarters is less clear.
Q3 revenue +55% and an 84% adj. EBITDA margin is impressive. But Q4 guidance implies sequential growth slowing to the high single digits, and management itself noted that bigger Q4s are often followed by tougher Q1s as the consumer/e-commerce business scales.
The AI model upgrade that drove the beat is still only partially rolled out. Full deployment timeline remains open-ended. Competition in mobile ad tech (Unity, Meta, others) hasn’t gone away, and the legal overhang on AI claims is still live.
After a 60% drawdown, the stock was cheap. After a 30% one-day pop, a lot of the near-term good news is now in the price. High-beta names that gap hard on earnings often mean-revert when the next data point is merely “in-line.”
The business is still high-quality. The trade on the pop is less obvious.

1
65
Peter Agro retweeted
My million $$ advice to you ( I accept X cash ) is sell it all put it into $SGOV for now and invest the dividends, buy some real estate , travel , focus on health and stop wasting time on Twitter unless you need money .
In 2002, Sun Microsystems CEO Scott McNealy looked back at the peak of the dot-com bubble and asked investors one question:
“At 10x revenues… what were you thinking?”
He explained that even at 10x sales you would need zero costs, zero expenses, zero taxes, zero R&D, and 100% of revenue paid out as dividends for 10 years just to break even.
Sun later fell more than 90%.
Palantir $PLTR is currently trading at roughly 50–60x trailing sales.
That is 5–6 times the multiple McNealy already called ridiculous.
At these prices the same logic requires something closer to 55 years of paying out every dollar of current revenue as pure dividends — still assuming zero costs, zero taxes, and flat growth forever.
What are we thinking?

1
20
Buying Palantir at these prices is like paying $150 for a slice of pizza that currently costs $1 to produce.
Here’s the math.
Palantir’s market cap is roughly $429 billion.
Last twelve months profit: about $3.7 billion.
That’s a trailing P/E of ~125x.
In pizza terms:
You buy the entire shop.
The shop currently makes $3.7 billion in profit a year.
You paid $429 billion for it.
If profits stayed flat forever, it would take you 125 years of collecting every dollar of profit just to get your money back.
Even on next year’s expected earnings (forward P/E ~80x), you’re still looking at roughly 80 years of all future profits to break even — assuming zero growth after that.
For the price to make sense, the shop has to keep growing extremely fast for a long time. High multiples only work if the growth is both large and durable. Any slowdown in the growth rate and you are left holding a very expensive piece of pizza.
The quality of the growth also matters. Recent results still show receivables rising faster than sequential revenue. Strong headline growth, but part of the “sales” is still unpaid.
Not advice.
Do your own work.
Make your own Pizza.

2
32
Apple just guided to 7–10% growth and 45–46% gross margins.
That profile historically supports a mid-20s to low-30s forward P/E.
The stock is still trading at 35–38x.
At those multiples the math points to roughly $270–$320.
The arithmetic doesn’t require a crash — just a recognition that mid-teens growth is over and the multiple has room to compress if the guide holds.
Not a sell call. Just math. $AAPL

1
22
Palantir’s Q3 numbers look strong on the surface.
Revenue +96% to $2.31B.
U.S. commercial surpassed government for the first time.
Guidance raised again.
But the quality flag is still there.
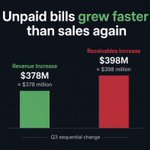
Accounts receivable rose ~$398M in the quarter.
Revenue rose ~$378M.
Unpaid bills grew faster than the new sales again.
Cash generation remains excellent, but the collection lag continues.
At this valuation, that gap matters more than the headline beat.

1
16
Apple $AAPL reports today. The setup looks stretched.
• Trading at ~39x trailing / ~36x forward earnings with revenue growth expected to slow into the mid-to-high single digits.
• No clear AI-driven iPhone upgrade supercycle. Replacement cycles are lengthening and early iPhone 18 Pro signals in China have been soft (shorter lead times, discounts). • Still heavily exposed to China for both demand and manufacturing. Local competitors keep taking share. • Services is the high-margin engine, but it still depends on hardware units and faces regulatory risk (Google TAC payments, App Store rules).
• Market is treating a mature hardware + ecosystem company like a high-growth AI platform. That gap is the short.
Earnings can always surprise. The multiple leaves little room for disappointment.
Not advice.

74
Palantir $PLTR is booking more sales.
A growing share of those sales is still unpaid.
In 9 of the last 12 quarters, the unpaid bills grew faster than the actual sales.
One customer alone is a big piece of the unpaid pile.
This doesn’t mean the sales aren’t real.
It does mean the cash is arriving slower than the growth numbers suggest.
Probably nothing to worry about … 👝

44
Michael Burry’s point on $PLTR:
At a fully diluted market cap north of $350B, you could buy Northrop Grumman, General Dynamics, and Lockheed Martin—and still have enough left over for L3Harris.
Today the gap is even wider. PLTR sits around $470B. The four traditional defense primes combined are still smaller.
But the earnings gap is the opposite story.
In 2025 those four companies generated ~$15B in combined net income.
PLTR generated $1.6B.
On a trailing basis the four still produce roughly 5–6× more net earnings.
These are companies with decades of Pentagon contracts, massive backlogs, hard assets, and actual manufacturing. PLTR is priced as if its software platform has already replaced them.
Burry has held long-dated puts on the name for a long time. The comparison is still the cleanest version of his valuation argument.

1
92
$MU cash vs market cap near a cycle top.
Market cap: ~$1.06T
Cash + short-term investments: ~$43B
Broader cash + marketable securities: ~$73B
That’s roughly 4–7% of the equity value sitting in cash.
The rest is priced on peak-cycle earnings from the AI memory boom. Memory has never stayed this profitable forever. SK hynix leads HBM, Samsung is ramping HBM4 hard, and capacity is coming from all three plus Chinese players in conventional DRAM.
When the cycle turns, cash doesn’t cushion a $1T valuation the way people think it does. Peak earnings get capitalized at trough multiples.
The cash pile is real. The permanence of the margins is not.
80
Palantir $PLTR (~$475B market cap) holds only ~$9.4B in cash.
That’s ~2% of the valuation.
The rest is a pure bet on growth that must stay exceptional.
Claude (and other frontier models) is the under-discussed risk.
What used to require a specialized platform + ontology + forward-deployed engineers can now be approximated by connecting Claude to a company’s own data + some lightweight agents.
The barrier for “good enough” operational AI just collapsed.
Palantir’s real moat isn’t the model. It’s deep data integration, security clearances, and high switching costs once you’re embedded. That still matters for defense and complex enterprises. But for a growing set of commercial use cases, the premium is harder to defend.
Meanwhile, pairing a Grok bot (persistent memory, routines, computer access) with Claude creates something closer to a private operating system for one person or a small team. One handles long-horizon execution and tools; the other brings strong reasoning and coding. Together they let you build, analyze, and operate systems that used to require a vendor.
The technology is evolving faster than most enterprise software premiums. Cash doesn’t protect a 160× earnings multiple when the product layer is getting cheaper to replicate.

1
120
Peter Agro retweeted

In this AI valuation reset driven by high capex, debt and delayed ROI, the strongest short candidates are overleveraged neoclouds: CRWV, NBIS, IREN and APLD. Bond yields spiking above 15% and refinancing pressure leave them most exposed to further downside versus better-capitalised leaders.
You call it a "Danish."
The Danes call it "Viennese bread."
And the Germans call it a "Copenhagen."
How a 1850s labor strike transformed a butter crisis into the world's most confused pastry.
🧵👇🏼

1
40