

A rational mind with an adventurous soul.
Joined June 2021
- Tweets2.1K
- Following389
- Followers595
- Likes7.6K





Pinned Tweet
21 Logical Reasons Why Patience in $RFD Could Be Extraordinarily Rewarded
If your honest answers to these questions are mostly “Yes,” then it is only logical to believe that $RFD represents not just a speculative token, but a patient investment into one of the rare, truly visionary ecosystems being quietly built in crypto today.
1. Has Blurr proven himself to be a DeFi genius with a successful track record?
2. Is Blurr respected by many early crypto adopters and DeFi experts?
3. Has Blurr demonstrated an ability to innovate and anticipate market needs?
4. Has Blurr acted transparently whenever it was not harmful to the project, and always without malicious intent toward the community?
5. Has Blurr ever shown through his actions (such as burning almost 0.5 million $RFD) that he is not involved in $RFD for quick personal gain?
6. Is it obvious by on-chain actions and community knowledge that Blurr is the deployer, creator, and manager of $RFD’s treasury wallet?
7. If Blurr had intended to abuse his credibility for unfair gains, wouldn’t he have easily sent the $RFD chart skyrocketing with empty promises, but he chose not to?
8. Is it logical that building a unique and innovative ecosystem requires time, a silent environment, and protection from copycats?
9. Does Blurr most probably have sufficient wealth and therefore no motivation to risk his reputation for a quick or unfair gain?
10. Has Blurr ever publicly expressed that the true purpose of life lies in meaningful creation rather than just personal enrichment?
11. Is it true that Blurr launched $RFD without taking any funds through taxes, pre-mines, VC deals, or unfair advantages?
12. Can $RFD be considered one of the fairest and purest token launches ever seen in DeFi?
13. Does the $RFD token still have an organic and loyal community despite harsh market cycles?
14. Has Blurr unchangeably hinted that he holds a big vision for $RFD?
15. Is it logical to believe that a builder who already achieved greatness is capable of doing it again, especially with more experience?
16. Have we seen clear hints suggesting that $RFD will probably connect to a broader and innovative DeFi ecosystem?
17. Is Blurr known for working silently and carefully in the background, rather than overhyping projects prematurely?
18. Can projects built quietly and carefully sometimes outperform those that are loudly and prematurely marketed?
19. Is timing often critical in DeFi, and could early positioning in a strong project lead to exceptional rewards?
20. Is it likely that $RFD’s fair launch, wide distribution, and community-first philosophy will help it succeed in the decentralized future?
21. Is there a real possibility that $RFD and Blurr’s future developments could reshape important parts of the DeFi landscape?
#RFD #DeFi @ReFundCoinETH

Refund ($RFD) & Papertrade:
A Shared Liquidity Engine?
Could @blurr, the deployer of Refund, be considering a future in which Refund and Papertrade become complementary parts of the same economic ecosystem? This is a hypothesis, not a confirmed plan. If it is not already part of his vision, it may be worth exploring.
Under this model, Papertrade would remain the trading platform, while Refund would become an independent liquidity partner. Rather than acting simply as a builder channel, Refund would have an exclusive role in two activities: providing a limited redemption route for $PAPER and operating a marketplace for eligible pending winner claims.
A one-way redemption route for $PAPER
A $PAPER holder who wants immediate liquidity could choose to redeem PAPER through an approved mechanism in exchange for USDC. The PAPER would move directly into the Refund ($RFD) treasury, where it could be staked to generate potential future income, while a portion would be burned gradually.
Crucially, PAPER held by the treasury would not be available for resale or onward transfer. This would avoid creating an open secondary market for PAPER, while giving holders a voluntary liquidity option. Any such arrangement would require Papertrade’s approval and a carefully designed exception to the existing transfer restrictions.
A marketplace for pending winner claims
When winning traders have outstanding claims in the payment queue, Refund’s marketplace could allow them to sell eligible claims at a discount to investors who provide USDC. Winners who choose to sell could access liquidity earlier, while buyers would accept the risks of waiting for settlement.
The marketplace could generate processing fees for Refund’s income pool. This part of the model would require claims to be transferable and enforceable under Papertrade’s rules.
A role for $RFD and the Refund treasury
Refund’s economic role could give more people a reason to use and trade $RFD. In turn, increased genuine trading activity could generate transaction fees from the RFD/ETH liquidity position (liquidity Pool).
The proposed allocation would connect the two ecosystems:
RFD collected through the liquidity mechanism could be burned.
ETH collected as fees could strengthen Refund’s liquidity reserve and, under agreed conditions, help support Papertrade.
Income from staked PAPER and marketplace fees could contribute to Refund’s income pool and the broader ecosystem.
$RFD holders could therefore participate indirectly in the economic activity surrounding Papertrade without needing to trade on the platform themselves. The benefit would depend on the project’s treasury rules and market conditions; holding $RFD would not automatically give holders a direct claim on $PAPER staking rewards or treasury assets.
A shared economic cycle
The vision is a partnership in which Refund provides a dedicated liquidity layer around Papertrade, and both projects contribute to a sustainable economic relationship.


From the Nevada Desert to the Papertrade Ecosystem: Could Refund ($RFD) Have a Place in This Emerging City?
Just as casinos once transformed the barren Nevada desert into a vibrant and prosperous destination, giving rise to hundreds of businesses, large and small, that flourished within the economy surrounding them, Papertrade, through its innovative economic model and network of Builder Channels, has the potential to become the beating heart of a vast and dynamic ecosystem.
An ecosystem where new economic opportunities, innovative utilities, and businesses of all sizes can emerge and thrive.
Within this vision, the potential for Refund ($RFD) to play a meaningful economic role in this emerging city should absolutely not be overlooked.
Perhaps Refund’s place in this grand architecture has yet to be revealed, but one question remains:
Will Blurr, with his long-term vision and distinctive philosophy, truly leave a project he once initiated unfinished?
I strongly believe Blurr is not the kind of architect who abandons a creation halfway through its journey, especially when an entirely new city is rising alongside it.


Ships Are Built to Sail, Not to Remain in Harbor.
Blurr’s philosophy also reminds us that ships are not built to remain safely in harbor, but to sail toward new horizons.
Has the Refund ($RFD) ship raised its sails and is ready for the open sea?
It’s time to continue the voyage we once began, guided by the very philosophy Blurr and Refund community always stood for.
Smoke.

Ships Are Built to Sail, Not to Remain in Harbor.
Blurr’s philosophy also reminds us that ships are not built to remain safely in harbor, but to sail toward new horizons.
Has the Refund ($RFD) ship raised its sails and is ready for the open sea?
It’s time to continue the voyage we once began, guided by the very philosophy Blurr and Refund community always stood for.
Smoke.

The first cigarette I ever smoked was in the short-stay car park of Stavanger airport. It was a Camel Blue. The sky was Norwegian. Overcast and grey.
Since then I have smoked a lot of cigarettes, and will often claim that taking it up was the best decision I have made in a long time.
A cigarette operates as a small stick of entropy; within that single gram lives an agent of motion, a compulsion exerting itself over soporific lives. The random conversations one has with strangers over a cigarette often carry an edge of meaning that is hard to find in an otherwise superficial world. Mutual participation in a self-destructive exercise. Common ground transcending language. Line cooks, security guards and executives, relegated to a huddle under an awning as the rain pours, sharing a lighter. Ritual.
Much of what we have lost in the last two generations can be distilled to a neutering of our innate risk appetite. An unlanceable push towards comfort and safety, calcifying young minds and inculcating in them the belief that they are enough the way that they are. That to cast the runes is to err. Lost.
You are not enough. To make it is to understand that you never will be — and then to try anyway.
Smoke.
From Zero Initial LP Capital to $1 Trillion in Trading Volume.
Is Blurr’s Next Surprise $RFD?
Papertrade, built around an innovative economic model requiring no upfront capital to seed its trading liquidity pool, reportedly reached approximately $1 trillion in cumulative notional trading volume in just four days.
An extraordinary milestone that demonstrates how a creative concept can challenge conventional DeFi trading models.
But perhaps the most fascinating innovation isn’t the staggering trading volume itself. It’s the way Papertrade is redefining the economics of losing.
Under its model, traders who incur eligible losses receive $PAPER, a token that can be staked to participate in the platform’s reward distribution mechanism.
This creates an unusual dynamic: some losing traders may view their losses not simply as financial setbacks, but as the potential cost of entering a long-term income-generating opportunity.
Of course, the future economic value of $PAPER depends on the platform’s performance, reward sustainability, liquidity, and market demand.
Nevertheless, if this model proves sustainable, it could become a remarkable innovation in DeFi economics.
I believe Blurr and Jez, the creative minds behind Papertrade, have the potential to establish an increasingly influential reputation in crypto and DeFi. Their involvement in future projects could eventually become a very powerful source of credibility, attracting substantial attention, capital, and economic value.
And that brings me to the question I find most intriguing:
What does Blurr have in store for his earlier creation, Refund ($RFD), a project whose full potential, in my view, has yet to be realized?
Could Papertrade’s success be setting the stage for an entirely new chapter in the Refund story?
Perhaps the most exciting part of this story hasn’t even begun.

Why hasn’t @blurr used the Refund ($RFD) treasury to accumulate $PAPER?
From the very beginning of Papertrade’s launch, some users began trading with a specific objective: accumulating as much $PAPER as possible. Some even established investment treasuries to accelerate the process of acquiring and accumulating the token.
Their economic rationale is relatively straightforward: if Papertrade evolves into a successful and sustainable platform, staked PAPER tokens could potentially generate substantial recurring rewards over the long term. If sustained, these rewards could strengthen demand for PAPER and contribute to its economic value.
Only a few days have passed since Papertrade went live. According to reported figures, cumulative trading volume has already exceeded $990 billion, approaching the remarkable milestone of $1 trillion in less than a week. Total staking rewards are estimated at approximately $36 million.
Of course, particularly on a platform offering extremely high leverage, trading volume should not be confused with an equivalent amount of capital entering the ecosystem. Likewise, the extraordinary staking rewards observed during the initial days cannot automatically be extrapolated into the future without examining the platform’s underlying economics.
Nevertheless, the initial enthusiasm and users’ determination to accumulate PAPER cannot necessarily be dismissed as mere short-term speculation.
It appears that at least part of the market is already attempting to price in the token’s future income-generating potential.
If these expectations materialize, PAPER alone could become the foundation of a secondary economic market generating millions of dollars in daily trading activity.
But this brings us to an intriguing question.
Why Has the Refund Treasury Apparently Not Accumulated PAPER?
Blurr, who participated in the creation and development of Papertrade and is also the creator of Refund ($RFD), has spent the past several years allocating portions of the Refund treasury’s assets to various DeFi opportunities, including staking, liquidity provision, and yield-generating strategies.
So the question is:
Why hasn’t he apparently deployed the Refund treasury’s resources to accumulate PAPER this time?
Given Blurr’s direct involvement in developing Papertrade, it seems reasonable to assume that he has a particularly deep understanding of PAPER’s economic mechanics, revenue potential, and associated risks.
Imagine that the Refund treasury had allocated approximately $2 million to acquiring PAPER and, under particularly favorable conditions, managed to accumulate 200 million tokens.
In that scenario, Refund would essentially become an investor in the Papertrade ecosystem, with its economic exposure largely dependent on PAPER’s valuation and staking returns.
But what if Blurr has envisioned a much broader economic role for Refund than simply holding PAPER as an investment?
This is precisely where my hypothesis begins.
The Hypothesis: Refund as an Economic Infrastructure Layer Complementing Papertrade
I believe one of the most intriguing possibilities is that Blurr may have preferred to leverage Refund’s existing independent resources, including its substantial liquidity pool, multimillion-dollar treasury, and established holder community, to develop an economic ecosystem operating alongside Papertrade.
Under this scenario, Refund would not merely own PAPER tokens.
Instead, it could actively participate in capital circulation, liquidity provision, financial services, and the development of secondary markets connected to Papertrade.
🧵1/3

The significance of this possibility becomes clearer when we consider one of the fundamental challenges facing meme coins.
Community enthusiasm and social momentum, although essential for launching and growing a project, are rarely sufficient on their own to sustain its economic value indefinitely.
What can contribute to long-term sustainability is the creation of genuine economic utility, recurring demand, and durable revenue streams.
However, designing such utility, particularly when it must be innovative, competitive, and economically productive, is exceptionally difficult.
With Papertrade, Blurr and Jez have attempted to introduce a different approach to leveraged trading and the distribution of economic rewards.
The platform’s remarkable initial trading activity suggests that this model has succeeded, at least initially, in attracting substantial market attention.
Of course, its long-term success will depend on several critical factors: sustainable liquidity, reliable settlement mechanisms, effective risk management, transparent economics, and continued user confidence.
If Papertrade demonstrates operational stability over the coming months, builds further trust, expands the range of tradable assets, and introduces additional functionality, its capacity to attract users and economic activity could reasonably increase.
Sustained growth in trading volume, however, should not be taken for granted.
This brings me to another question:
Why should we assume that an ecosystem with such economic potential, co-created by Blurr, will have no connection whatsoever to the economic future of another project he created, Refund ($RFD)?
Such a connection remains unproven, but I believe the possibility deserves serious economic consideration.
A Refund Builder Channel: One Possible Scenario
In his recent interview, Blurr emphasized the importance of genuine economic utility for meme coins.
He also discussed the potential economic opportunities associated with creating successful builder channels on Papertrade.
Taken together, these two observations provide an interesting foundation for speculation.
Imagine that Blurr eventually unveils a dedicated Refund Builder Channel, one designed to operate far beyond a conventional trading interface and provide users with a broader range of financial and economic services.
Subject to the necessary technical infrastructure and risk controls, such a channel could potentially offer the following capabilities.
1. Exclusive Benefits for $RFD Holders
Users holding a specified minimum amount of $RFD could gain access to premium services, economic incentives, or participation in designated reward mechanisms.
2. A Secondary Market for $PAPER
A marketplace enabling users to trade economic exposure to PAPER, participate in staking-related investment strategies, or transfer eligible future claims.
3. Immediate Liquidity for Pending Trading Profits
A mechanism allowing traders to sell eligible, transferable claims on unsettled winnings at a discount to liquidity providers, receiving immediate USDC or other supported assets.
4. Performance-Based Trader Rewards
Allocating a portion of the channel’s actual revenue, including eligible builder fees, to competitive incentives and rewards for successful traders.
5. Intelligent Trading Tools
Providing automated strategies, predefined trading systems, and risk-management tools, particularly for users with limited technical experience.
🧵2/3
A Multimillion-Dollar Opportunity for Refund ($RFD)?
In just the first 24 hours of Papertrade’s operation, approximately 6 billion $PAPER tokens were generated, more than 98% of which have been staked so far. According to the latest figures, the total rewards recorded for stakers have also reached approximately $25 million.
If we consider the total losses that led to the creation of this volume of PAPER, the initial cost incurred by losing traders could perhaps be estimated at more than $70–80 million. However, this figure is merely an estimate and should not be confused with PAPER’s market capitalization, as the token’s actual value depends on multiple factors; particularly expectations regarding future revenues and rewards.
The remarkable point is that we are talking about figures in the tens of millions of dollars, all within Papertrade’s very first day of operation!
Sooner or later, some $PAPER holders will consider liquidating their assets. This implies potential demand for the creation of an organized and liquid secondary market; one that could potentially generate millions of dollars in daily trading volume.
Now, here is the intriguing question:
Do you really think @blurr , as one of Papertrade’s developers and the creator of $RFD (Refund), would overlook such significant economic potential for creating real utility within his own project, $RFD?
Perhaps no official economic connection between the two projects has been announced yet, but it is not difficult to imagine Refund ($RFD) eventually playing a role in providing liquidity, facilitating $PAPER trading, or even handling claims owed to Papertrade.xyz winners.
And, of course, sometimes the answer to a complex question is right in front of us, even in the project’s name!
REFUND, Why not? 😉
This post is merely an economic speculation and does not claim that any agreement or confirmed plan exists yet between the two projects. NFA DYOR

Blurr’s Three Final Cryptic Messages: Is Chapter 13 Next?
“A penny for the old guy.”
What if Blurr’s final three cryptic messages from 2023 were clues to a much bigger story?
11. “Those who know do not speak, those who speak do not know.”
Three years of silence, followed by Blurr’s recent public interview ahead of Papertrade’s launch.
12. “The mighty ruler sends a request across the land and along the sea path, offering the abundant radiance of terror to their men and sons.”
Could this foreshadow Blurr’s first post on Papertrade’s launch day? A mysterious figure, @blurr , standing on land, facing the sea and the horizon, seemingly leaving uncertainty and risk behind.
13. “A penny for the old guy.”
And perhaps this is the next chapter: the long-awaited emergence of $RFD’s economic role within a broader ecosystem, potentially transforming trading losses into new opportunities through Refund.
Pure speculation, of course. But if messages 11 and 12 have found their symbolic moments, could message 13 be the missing piece?
Papertrade.xyz is just the beginning, and Refund’s real story is yet to unfold… soon 👀


🔥 Is $RFD (Refund) entering a new chapter of growth?
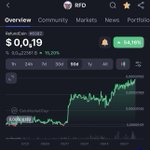
Over the past 30 days, while Ethereum ($ETH) has gained just 1.1%, Refund ($RFD) has delivered an impressive 30.2% surge!


$RFD: Quietly Gaining Momentum Alongside Ethereum
Over the past 90 days, $RFD has moved remarkably in step with ETH, while slightly outperforming it: roughly +54% vs. +50%.
Even more encouraging, the past 30 days have shown a slow but steady increase in new wallets buying RFD, suggesting gradually expanding participation.
If this momentum continues, the coming days could paint an even more interesting picture for $RFD. 📈
Slow growth. Stronger base. Brighter days ahead.
0x955d5c14C8D4944dA1Ea7836bd44D54a8eC35Ba1


In my view, if we interpret the gun as a symbol of danger and risk, Blurr may be hinting at a ten-day period, from October 11 to 21, following Papertrade’s launch, as a potentially risky phase. But what’s particularly intriguing is that his gaze is fixed on the horizon, as if he sees a long-term vision beyond the short-term risks.
The Refund Community: Exciting Days May Lie Ahead!
The $RFD (Refund) community may be approaching an exciting new chapter.
@blurr , the creator and deployer of $RFD (Refund), finally showed his face publicly in last week’s interview, nearly three and a half years after RFD’s launch. The occasion was the introduction of another remarkable and innovative creation: Papertrade.xyz
Developed in collaboration with @izebel_eth , this new platform has already generated considerable excitement and interest among traders and crypto enthusiasts. Both creators deserve sincere congratulations for this impressive achievement.
In my view, this success gives the Refund community another reason to take pride in Blurr’s creativity, innovative thinking, and willingness to challenge conventional boundaries.
Since RFD’s earliest days, his mysterious and thought-provoking cryptic messages have hinted at a deeper philosophy centered on long-term value creation, collective participation, and the untapped potential of decentralized finance.
Yet one fascinating question remains:
Will there be a meaningful economic connection between these two projects: Refund ($RFD) & @papertrade_xyz ?
Or perhaps Refund, along with its multimillion-dollar treasury, which has been built and managed over the past few years by Blurr, is part of an entirely separate and innovative vision that has yet to be unveiled.
debank.com/profile/0x4c53148…
Of course, these possibilities remain speculative, and only concrete developments can confirm them.
Nevertheless, I believe one important point deserves particular attention:
Even without any direct economic integration between $RFD and Papertrade, Papertrade’s success will become a valuable advantage for Refund’s future.
Why?
Because every new achievement by Blurr strengthens his professional credibility, demonstrates his ability to execute ambitious ideas, and reinforces his position within the crypto ecosystem.
That growing reputation could naturally attract greater attention to his earlier creations, mainly $RFD. Should meaningful economic utilities eventually emerge, this increased visibility and credibility could become powerful catalysts for Refund’s long-term development.
In other words, Papertrade’s success could help create a much more favorable environment for $RFD to realize its potential soon.
For that reason too, we, as members of the Refund community, have every reason to watch Papertrade’s launch and future development with even greater enthusiasm and optimism.
As a $RFD community member, I sincerely wish Blurr and Jez continued success.
The most exciting chapter of the Refund story has yet to be written!


EVEN BEFORE TRADING BEGAN, @PAPERTRADE_XYZ HAD SURPASSED $90M IN TVL.
nitter.gq/HyperliquidNews/status…

Refund ($RFD): An Unfinished Story, an Economic Vision, and the Mystery of October 28
Could Blurr’s next chapter finally reveal the purpose of Refund?
In his recent interview,@blurr made an important observation: a social movement alone cannot guarantee the long-term sustainability and growth of a meme coin. Economic utility matters.
That statement raises an intriguing question about Refund ($RFD), the token he created and launched on May 20, 2023.
If Blurr believes that meme coins need economic foundations to survive, could Refund-his own creation-have been designed with a broader economic purpose from the beginning?
To explore this possibility, we need to distinguish between what has actually happened, what can reasonably be inferred, and what remains speculation.
1. The Facts: A Mysterious Beginning and a Treasury That Never Disappeared
$RFD was launched without a presale or team allocation, accompanied by a series of cryptic on-chain messages from Blurr.
Several of those messages carried philosophical themes that could be interpreted as emphasizing patience, independence, meaningful creation, and collective interests.
Blurr also adopted the image of the famous CryptoPunk #9998 as Refund’s visual identity, adding another layer of symbolism to an already mysterious project.
Nearly three and a half years later, Refund remains an unusual case among meme coins: a token whose creator has offered virtually no public explanation of its long-term purpose, yet whose associated on-chain assets have continued to be managed.
One of the most significant events occurred in 2024, following the expiration of Refund’s approximately 15-month Uniswap liquidity lock.
According to the on-chain transaction history I have followed, Blurr took several notable actions:
Token burn: The RFD accumulated through Uniswap trading fees, worth approximately $500,000 at the time, was transferred to the zero address and permanently burned.
Treasury management: More than 900 ETH accumulated from trading fees was subsequently deployed across DeFi staking and yield-generating strategies, rather than simply being distributed or withdrawn for personal use.
Separation of initial capital: The ETH originally contributed from Blurr’s personal wallet to establish Refund’s initial liquidity was returned to that wallet. In my interpretation, this was a meaningful distinction between his initial personal contribution and the assets subsequently accumulated through the project.
Continuing liquidity and asset management: Refund-related treasury assets and its substantial unlocked Uniswap liquidity position have remained observable on-chain.
The relevant wallet activity, including transactions across Ethereum and Base, can be examined publicly through DeBank:
debank.com/profile/0x4c53148…
At various points, the treasury has held approximately 780 ETH, alongside other DeFi positions. The project also maintains a substantial unlocked liquidity pool.
These observations are important because they establish something beyond symbolism: Refund has accumulated and managed economically meaningful assets.
However, an important distinction remains. The existence of a treasury and an actively managed liquidity pool demonstrates financial infrastructure, but does not by itself prove a specific future utility or commitment to any particular ecosystem.
2. The Interpretation: Why Build a Treasury Without an Economic Purpose?
This is where documented activity gives way to interpretation.
In my view, the combination of accumulated trading fees, token burns, treasury management, and continued liquidity provision suggests that Blurr may have had a longer-term economic strategy for Refund.
Otherwise, why preserve and manage these resources for years?
Even more intriguing is his silence.
🧵1/4

Across two interviews over the past couple of years, Blurr has neither publicly outlined Refund’s future nor explicitly distanced himself from the project.
For some holders, this prolonged silence has understandably been frustrating. For others, including myself, it leaves open a different possibility.
Perhaps the unspoken message is:
“My work with Refund is not finished. I will explain it when the time is right.”
To be clear, these are my words, not Blurr’s. They represent my personal interpretation of his actions and silence.
His actual intentions remain unknown.
Still, his apparent preference for measured execution over constant publicity makes this interpretation worth considering.
And that brings us to an even more fundamental question.
3. Why Call It “Refund” in the First Place?
Names can sometimes reveal the underlying philosophy of a project.
The word Refund naturally suggests returning money, compensating for a loss, or restoring value that someone previously gave up.
Was the name chosen merely for its meme appeal? Or could it eventually describe an actual economic function?
Could Refund become a mechanism for providing liquidity against losses, purchasing discounted claims, or allowing users to recover some value from otherwise illiquid assets?
Until recently, such questions had no obvious economic context.
Then came Papertrade.xyz
4. Papertrade: Could This Be the Missing Economic Context?
Papertrade, scheduled to launch on October 10, 2026, introduces an entirely new dimension to this speculation.
The platform’s proposed economic structure includes leveraged trading, the creation of PAPER tokens associated with trading losses, and potential future utilities for those tokens.
Yet several economically important questions remain.
What will determine PAPER’s market value? How easily will holders be able to liquidate their tokens? What role might external liquidity providers play? And how will the platform handle the liquidity and settlement of claims associated with winning traders?
These are distinct economic challenges, and they do not necessarily require the same solution.
But this is precisely where Refund becomes interesting.
What if Refund was designed to become an independent economic participant within the broader Papertrade ecosystem?
Consider a hypothetical structure in which Refund operates through a separate protocol or builder channel.
Its treasury could potentially provide liquidity to $PAPER holders willing to sell their tokens at a discount, allowing those holders to exit without waiting for deeper secondary-market liquidity.
A separate mechanism could potentially involve purchasing eligible outstanding claims from winning traders at discounted prices, subject to the platform’s settlement architecture and the transferability of those claims.
In return, Refund’s treasury could acquire assets with potential future value, while the broader ecosystem benefits from additional liquidity and more flexible exit opportunities.
Under such a model, Refund would not necessarily need to distribute $RFD tokens or sell its holdings to fund these transactions. Treasury reserves could be allocated under clearly defined rules, with appropriate liquidity and risk controls.
The existing RFD liquidity pool could continue serving its original market function, while treasury capital supports separate economic activities.
This distinction matters because it could help preserve the independence of the two projects.
Papertrade could remain focused on its trading infrastructure, while Refund operates as an independent liquidity and capital-allocation participant, potentially benefiting from the economic opportunities created by the platform.
Such an arrangement might also help reduce conflicts of interest, provided governance, pricing, risk allocation, and settlement mechanisms were appropriately designed.
🧵2/4
$RFD: Quietly Gaining Momentum Alongside Ethereum
Over the past 90 days, $RFD has moved remarkably in step with ETH, while slightly outperforming it: roughly +54% vs. +50%.
Even more encouraging, the past 30 days have shown a slow but steady increase in new wallets buying RFD, suggesting gradually expanding participation.
If this momentum continues, the coming days could paint an even more interesting picture for $RFD. 📈
Slow growth. Stronger base. Brighter days ahead.
0x955d5c14C8D4944dA1Ea7836bd44D54a8eC35Ba1
Why Could $RFD + Papertrade.xyz Create a Self-Sustaining On-Chain Economy?
Are Blurr and Jez trying to turn some of crypto’s most persistent human behaviors into a self-sustaining on-chain economy?
$RFD, created and launched by Blurr.eth on May 20, 2023 (0x955d5c14C8D4944dA1Ea7836bd44D54a8eC35Ba1), together with its 13 cryptic messages, taps into the social dynamics that make memecoins so powerful: community, identity, attention, and, of course, the asymmetric dream of turning relatively small amounts of capital into extraordinary returns.
@papertrade_xyz taps into another powerful human behavior: the appetite for speculation, competition, and extreme leverage, where a relatively small number of traders can potentially win enormously while many others lose their positions.
#DeFi provides the infrastructure capable of transforming all of this activity into liquidity, fees, treasury flows, and programmable economic value.
It is also worth considering that while the Papertrade ecosystem itself could provide a foundation for developing many attractive economic utilities, not every utility necessarily needs, or should, to be embedded directly into the core protocol. In a broader decentralized ecosystem, maintaining some separation between economic interests and incentive mechanisms can be valuable, particularly where integrating a protocol’s own direct economic interests into every mechanism could create conflicts of incentives or reduce neutrality.
From that perspective, an independent project with complementary characteristics could potentially expand the economic design space around Papertrade without requiring every function to be internalized by Papertrade itself. If RFD were ultimately intended to play such a complementary role, its independence would not necessarily imply separation from the broader ecosystem; paradoxically, that independence could be precisely what allows the ecosystem to expand while preserving distinct incentives, communities, liquidity structures, and economic functions.
The interesting part is what happens to the losses.
In conventional leveraged trading, a trader loses $1,000 and, economically, that is largely the end of the story for that trader. But if Papertrade converts trading losses into PAPER, and staked PAPER represents participation in future platform revenue, part of the economic value associated with that loss may effectively be recycled into a new claim on future cash flows.
If, as I anticipate, $RFD eventually becomes another predetermined layer in that loop through a Builder channel, treasury, liquidity, conversion mechanism, or some other utility, the architecture becomes even more interesting:
Speculation → trading profits/losses → PAPER → revenue participation → RFD / treasury / liquidity → recycling losses by acquiring future claims or expected PAPER value at a discount → more economic activity.
In such a model, the treasury could potentially act as an economic intermediary: providing immediate liquidity by acquiring claims on future value at a discount, while recycling capital back into the ecosystem.
That would not mean a system with “no losers.”, but it could mean something more unusual: an on-chain economy where losses do not necessarily become economically dead capital, but can instead be transformed into new assets, claims on future revenue, liquidity, and continued participation in the ecosystem.
Perhaps the bigger idea isn’t to eliminate crypto’s endless appetite for speculation, but to build an economic machine around it, and continuously recycle the value generated by that speculation.
Whether RFD is actually part of that machine remains entirely speculative. But if it is, the name “Refund” suddenly becomes much more interesting.
In my view, @blurr may have envisioned “Refund” , from the beginning, as more than returning money: a reward-mechanism for turning risk, losses, and future claims into continued economic participation.

A Speculative Theory
Could $RFD Be the Missing Economic Layer Around Papertrade?
Papertrade.xyz is expected to launch soon. Based on the information available so far, @izebel_eth appears to be the principal architect behind Papertrade, with @blurr participating in its design and development.
One detail in the early Papertrade “whitepaper” is particularly interesting for the Refund community. Blurr was not introduced simply as a developer or collaborator, but specifically as:
“Blurr — Refund Contract Deployer”
This does not prove any connection between #RFD and Papertrade. However, Blurr is well known independently of Refund, so explicitly identifying him through Refund was not strictly necessary. It is therefore reasonable to ask whether Refund could eventually play a role in the broader economic architecture surrounding Papertrade.
$PAPER Appears to Control Papertrade’s Internal Economy
The current Papertrade model does not appear to require a large amount of initial liquidity. Instead, liquidity can grow progressively from traders’ losses. Losing traders receive PAPER, which can be staked to participate in the protocol’s future economics and revenue.
This makes PAPER the central economic asset inside Papertrade.xyz
Based on everything publicly disclosed so far, there is no demonstrated role for RFD within the core Papertrade protocol.
That, however, does not necessarily mean there is no role for Refund outside the core protocol.
The Builder Layer Creates Another Economic Opportunity
Papertrade’s Builder architecture allows third parties to build their own frontend or integrate Papertrade contracts into their existing distribution.
In simple terms, Papertrade.xyz can be viewed as the trading engine, while Builders can create alternative gateways to that engine.
A successful Builder therefore needs to offer users something valuable enough to justify choosing it over the native Papertrade frontend.
This could include better tools, fee rebates, rewards, automation, special access, or benefits connected to holding another asset.
This is one possible place where $RFD could theoretically acquire utility.
For example:
Hold RFD → Trade through a Refund Builder → Receive better fees, rebates or additional benefits
$USDC could still remain the trading collateral. $RFD would not need to become the currency used for trading; instead, it could function as a utility or access asset within the Refund layer.
Could Refund Treasury Become a Liquidity Backstop for PAPER?
There is another potentially more significant possibility.
If $PAPER is transferable under its final token rules, a separate smart contract could theoretically allow $PAPER holders to transfer or sell their PAPER to the Refund Treasury in exchange for $USDC or $ETH.
Importantly, this would not require a $PAPER/$RFD liquidity pool.
A hypothetical mechanism could work like this:
Trader loses on Papertrade
→ Receives PAPER
→ Trader chooses between:
A. Stake PAPER and retain the right to future Papertrade revenue
or
B. Transfer/sell PAPER to the Refund Treasury and receive immediate $USDC or $ETH liquidity
The Refund Treasury could determine the purchase price according to a transparent formula or at a discount to some reference valuation.
For example, a trader may prefer immediate liquidity rather than waiting for future staking income. Refund Treasury could purchase that PAPER, provide USDC or ETH to the trader, and then stake the acquired PAPER itself.
The economic relationship would therefore be straightforward:
Trader gives up future PAPER income in exchange for liquidity today.
Refund Treasury provides liquidity today in exchange for acquiring the future economic rights associated with PAPER.
If PAPER staking generates meaningful revenue, accumulating PAPER at an appropriate valuation could potentially become a productive use of Refund’s treasury rather than simply holding ETH or other assets passively.
🧵1/3
A Thought Experiment:
Could an Auction Marketplace Become RFD’s Most Interesting Papertrade Utility?
We’ve already explored one possible role for the $RFD treasury within the Papertrade ecosystem: providing liquidity to $PAPER holders who prefer immediate liquidity rather than holding or staking PAPER for future platform revenue.
But there may be another, and potentially much more interesting, opportunity on the other side of the trade: the winners.
What happens when Papertrade’s LP cannot immediately settle all profitable positions?
Some winners may have to wait in a creditor queue until sufficient liquidity becomes available. This creates an interesting possibility: what if those pending claims were made transferable?
Imagine you have a $10,000 claim, but nobody can tell you exactly when it will be fully settled.
Would you wait?
Or would you take $7,000 today? $5,000? Maybe even $3,000?
Now imagine putting that claim into an auction marketplace, where buyers compete for the right to its eventual $10,000 settlement.
Papertrade.xyz would effectively create another market:
a market for discounted future claims.
This is where #RFD could potentially become particularly interesting.
The RFD treasury could participate as a bidder when discounts become attractive, potentially providing liquidity to winners who prefer immediate cash over waiting for settlement.
But RFD wouldn’t necessarily need to take the balance-sheet risk itself.
If RFD provided the marketplace infrastructure, it could potentially collect a fee on every claim traded between third parties. In other words, rather than simply deploying treasury capital, RFD could monetize the flow of capital through the marketplace.
Combined with the earlier PAPER-liquidity thesis and potential Builder fees, an interesting structure begins to emerge:
Papertrade trading
→ PAPER liquidity
→ pending claims
→ claim auctions
→ Builder + marketplace fees
→ RFD Treasury
→ RFD buybacks / protocol-owned liquidity / other value-accrual mechanisms
At that point, the RFD treasury would no longer look like capital sitting around waiting for a purpose.
It could potentially become a liquidity and capital-allocation layer around the Papertrade ecosystem.
There is also something particularly interesting about a claim auction: the discount itself becomes a market price for liquidity, time and settlement risk.
A $10,000 claim trading for $8,000 tells one story.
The same claim trading for $3,000 tells a very different one.
That could make the secondary claim market almost as fascinating to watch, and potentially trade, as Papertrade itself.
Importantly, transferable claims do not necessarily need to exist in Papertrade’s initial architecture for this idea to be technically possible. Making creditor claims transferable would itself be a design choice or additional utility that could be introduced if the developers (@blurr @izebel_eth ) wanted to enable such a secondary market. Claims could potentially be represented as transferable on-chain rights, allowing ownership of the future settlement to change hands before the underlying payout occurs.
And since Blurr seems determined not to spoil whatever plans he may have for Refund, we might as well enjoy the sport of theorizing and trying to predict them ourselves. 😄
Maybe RFD’s biggest advantage isn’t simply that it has a treasury.
Maybe it’s that a treasury gives its deployer, Blurr, the capital, and flexibility, to invent utilities that otherwise wouldn’t be possible.
But for now, let’s put the theories aside and focus on Oct. 10, Papertrade launch day, with pre-deposits opening on 8th. Wishing Blurr and Jez a successful launch. Whatever our RFD theories may turn out to be, building something genuinely new, taking the risk of bringing an unconventional idea to life, and putting it out there for the market to judge deserves respect. Innovation doesn’t happen without people willing to take those risks. Good luck!

Notes from Blurr’s Interview: Is His Silence on $RFD Meaningful?
What follows is purely my personal interpretation and speculation based on Blurr’s comments in his recent interview. @blurr not only did not suggest any connection between Refund (RFD) and Papertrade but also, as perhaps expected, made no reference to Refund throughout the lengthy interview. On its own, this is not particularly surprising, since Papertrade was the main focus of the discussion. However, given that parts of the interview covered his personal history and some of his more notable experiences in crypto, the complete absence of RFD is, at least to me, worth noting.
Blurr explained that remaining anonymous was never an ideological or carefully planned decision. He simply had little interest in social media or in putting his personal life in the public eye. Now, however, as Papertrade approaches launch, he has chosen to reveal his identity much more openly and effectively put his personal reputation behind a project that, by his own admission, could carry reputational consequences for both him and his partner if it fails.
Elsewhere in the interview, Blurr discussed several notable experiences from his years in crypto, ranging from his early involvement with DeFi and Curve to specific trades and opportunities he encountered over the years. Yet he said nothing about creating and the launch of Refund, a project that attracted considerable attention within the crypto space when it launched.
Why was RFD completely absent from his story?
There is no definitive answer. The simplest explanation may be that he didn’t want to discuss RFD or simply did not consider it relevant to this particular interview. But there is also a more optimistic interpretation: perhaps, from his perspective, the RFD story is not finished yet, and he does not want to discuss it until its next phase is ready to be presented.
That possibility is particularly interesting at this stage. Papertrade has not yet launched, and it would be perfectly reasonable for Blurr to want the market’s attention focused entirely on introducing and launching the new platform. Mentioning RFD in such an interview would immediately invite a different set of questions: What is the future of RFD? What will happen to its treasury and LP? Is RFD still an active project? And, perhaps most importantly, is there any connection between RFD and Papertrade?
If there is indeed a future plan for RFD, remaining silent for now could therefore be a rational communication strategy. Of course, the opposite interpretation remains equally possible: he may simply want to keep RFD separate from his current narrative.
Another point I found interesting was Blurr’s awareness of reputational risk. When discussing potential failure modes, he jokingly referred to the possibility of people becoming angry and posting negative tweets. Elsewhere, he explained that Papertrade does not necessarily offer enormous personal upside to him and his partner, while something going seriously wrong could still have negative consequences for both of them.
This raises an interesting question: if Blurr is now putting his personal reputation directly behind Papertrade, why would he not be concerned about dissatisfaction among long-term RFD holders spilling over into his new project?
If there were absolutely no future plans for RFD, doxxing himself and becoming one of the public faces of Papertrade would naturally expose him to more questions and criticism from RFD holders. One possible interpretation is therefore that he expects it eventually to become clear that his involvement with Refund is not over.
Again, this is a behavioral inference, not evidence that any specific plan exists.
$PAPER and the Still-Evolving Part of the Ecosystem
Another part of the interview that deserves attention in this context is Blurr’s discussion of PAPER.
🧵1/3
youtu.be/2tMMfjBqgvo

He explicitly stated that $PAPER will not be tradable on day one but that it is intended to become tradable later. He did not provide a fixed timeline, explaining that they first need to observe how the system performs in practice. This suggests that Papertrade’s economic architecture will not necessarily reach its final form at launch; parts of the ecosystem may evolve based on the actual behavior of the platform and its users.
An important technical distinction needs to be made here: making PAPER tradable does not inherently require $RFD or the RFD treasury. A market for PAPER could be created through an LP, a DEX, or another liquidity mechanism. Blurr’s comments about PAPER’s future tradability therefore cannot, by themselves, be interpreted as evidence of a role for the RFD treasury.
However, this is precisely where an interesting hypothesis becomes possible.
If builders are eventually able to create their own channels, frontends, and economic mechanisms around Papertrade, RFD could potentially play a role not within the core protocol but as an economic layer surrounding Papertrade.
For example, one could imagine, purely hypothetically, an RFD Builder providing liquidity for PAPER, acquiring PAPER from users seeking immediate liquidity, staking that PAPER, and, in return, capturing PAPER-related revenue and builder fees. Under such a model, the RFD treasury could function as a capital and liquidity reserve.
Conceptually, such a scenario would also be interesting in light of the economic philosophy @blurr described for Papertrade: he wants some of the value that would traditionally accrue to an exchange or market maker to flow back to participants in the ecosystem. PAPER is the primary mechanism through which Papertrade seeks to create that economic alignment.
If RFD were eventually placed in another layer of this value cycle, the name #Refund itself could take on an interesting economic meaning: part of the value generated through trading activity and trader losses could, through another mechanism, ultimately flow back to participants in the broader ecosystem.
But once again, this distinction is essential: Blurr did not describe such a mechanism in the interview. It is simply a hypothetical model that could be compatible with some of Papertrade’s potential future capabilities.
The Point That May Be Easy to Miss
To me, the most interesting part of the interview may not actually be Blurr’s silence about RFD.
Blurr repeatedly gives the impression that he does not view Papertrade as a completely closed, predetermined product. Even when discussing one of PAPER’s most important future properties, its tradability, he says that he cannot provide a specific date because they first need to observe how the system behaves in the real world.
That may ultimately be more significant than whether he mentioned RFD at all.
If RFD is ever intended to play a role, it may not make sense for that role to be activated, or even announced, before Papertrade’s actual behavior can be observed. The bankroll, PAPER emissions, demand for PAPER, and user behavior would first need to become visible. Only then could it become clear whether there is a genuine need for an external layer providing liquidity, capital allocation, distribution, or some other economic function.
For that reason, the hypothesis I currently find more interesting is:
“RFD could potentially become an independent economic layer around Papertrade, whose utility only becomes relevant once the platform is live and the real-world behavior of PAPER becomes visible.”
If that hypothesis were ever to prove correct, Blurr’s current silence about RFD would also become easier to explain. Announcing such a role before launch could both distract attention from Papertrade and require him to discuss a mechanism whose practical purpose may not yet be ready to demonstrate.
🧵2/3

my full interview with @blurr, co founder of @papertrade_xyz
0:46 origins of papertrade
3:46 how papertrade works
11:29 learning from broken launches
13:35 why build on HyperEVM?
10:04 no funding fees on a $20M position?
25:00 how $Paper emissions work
32:59 I love jez
35:24 onchain wizard with no socials
39:18 super dead, super rich, or supermax
42:36 Tether on a phone was a Godsend
48:21 breeding CryptoKitties for profit
54:01 farming Curve for 3 hours
57:23 crypto can't be a social movement
1:07:29 value of labor is tunneling
1:10:46 why Blurr is a doomer
1:21:35 the CryptoPunks trade
1:28:19 advice for kids chasing the dream
A Speculative Theory
Could $RFD Be the Missing Economic Layer Around Papertrade?
Papertrade.xyz is expected to launch soon. Based on the information available so far, @izebel_eth appears to be the principal architect behind Papertrade, with @blurr participating in its design and development.
One detail in the early Papertrade “whitepaper” is particularly interesting for the Refund community. Blurr was not introduced simply as a developer or collaborator, but specifically as:
“Blurr — Refund Contract Deployer”
This does not prove any connection between #RFD and Papertrade. However, Blurr is well known independently of Refund, so explicitly identifying him through Refund was not strictly necessary. It is therefore reasonable to ask whether Refund could eventually play a role in the broader economic architecture surrounding Papertrade.
$PAPER Appears to Control Papertrade’s Internal Economy
The current Papertrade model does not appear to require a large amount of initial liquidity. Instead, liquidity can grow progressively from traders’ losses. Losing traders receive PAPER, which can be staked to participate in the protocol’s future economics and revenue.
This makes PAPER the central economic asset inside Papertrade.xyz
Based on everything publicly disclosed so far, there is no demonstrated role for RFD within the core Papertrade protocol.
That, however, does not necessarily mean there is no role for Refund outside the core protocol.
The Builder Layer Creates Another Economic Opportunity
Papertrade’s Builder architecture allows third parties to build their own frontend or integrate Papertrade contracts into their existing distribution.
In simple terms, Papertrade.xyz can be viewed as the trading engine, while Builders can create alternative gateways to that engine.
A successful Builder therefore needs to offer users something valuable enough to justify choosing it over the native Papertrade frontend.
This could include better tools, fee rebates, rewards, automation, special access, or benefits connected to holding another asset.
This is one possible place where $RFD could theoretically acquire utility.
For example:
Hold RFD → Trade through a Refund Builder → Receive better fees, rebates or additional benefits
$USDC could still remain the trading collateral. $RFD would not need to become the currency used for trading; instead, it could function as a utility or access asset within the Refund layer.
Could Refund Treasury Become a Liquidity Backstop for PAPER?
There is another potentially more significant possibility.
If $PAPER is transferable under its final token rules, a separate smart contract could theoretically allow $PAPER holders to transfer or sell their PAPER to the Refund Treasury in exchange for $USDC or $ETH.
Importantly, this would not require a $PAPER/$RFD liquidity pool.
A hypothetical mechanism could work like this:
Trader loses on Papertrade
→ Receives PAPER
→ Trader chooses between:
A. Stake PAPER and retain the right to future Papertrade revenue
or
B. Transfer/sell PAPER to the Refund Treasury and receive immediate $USDC or $ETH liquidity
The Refund Treasury could determine the purchase price according to a transparent formula or at a discount to some reference valuation.
For example, a trader may prefer immediate liquidity rather than waiting for future staking income. Refund Treasury could purchase that PAPER, provide USDC or ETH to the trader, and then stake the acquired PAPER itself.
The economic relationship would therefore be straightforward:
Trader gives up future PAPER income in exchange for liquidity today.
Refund Treasury provides liquidity today in exchange for acquiring the future economic rights associated with PAPER.
If PAPER staking generates meaningful revenue, accumulating PAPER at an appropriate valuation could potentially become a productive use of Refund’s treasury rather than simply holding ETH or other assets passively.
🧵1/3
Why This Could Make a Refund Builder Attractive
Such a facility could also solve an important problem: why would a trader use a Refund Builder instead of trading directly through Papertrade?
Imagine that the native Papertrade experience offers:
Trade → Lose → Receive PAPER → Stake PAPER
while Refund offers:
Trade → Lose → Receive PAPER → Stake it OR immediately exchange it for $USDC/$ETH through the Refund Treasury
That second option provides something economically meaningful: immediate liquidity.
$RFD ownership could theoretically enhance those terms.
For example, users holding a certain amount of $RFD might receive a smaller discount when selling $PAPER to the treasury, lower Builder fees, or additional rewards.
This could create a genuine utility loop:
Hold #RFD
→ Use Refund Builder
→ Trade on Papertrade
→ Generate Builder activity
→ Receive $PAPER after qualifying losses
→ Optionally sell $PAPER to Refund Treasury
→ Refund accumulates and stakes PAPER
→ Papertrade revenue flows to Refund Treasury
→ Revenue can potentially support the broader $RFD ecosystem
This would create an economic relationship between Papertrade and Refund without requiring $PAPER to convert into $RFD and without requiring a $PAPER/$RFD LP.
The Potential Flywheel
If some version of this architecture were implemented, the broader structure could look like this:
Papertrade
→ Trading activity
→ PAPER issuance and protocol revenue
↓
Refund Builder / Liquidity Layer
→ Builder fees
→ PAPER accumulation
→ PAPER staking revenue
↓
Refund Treasury
→ Rewards / Rebates / Liquidity / Buybacks / Treasury Growth
↓
$RFD Ecosystem
This could potentially turn Refund Treasury into something much more important than a passive pool of assets. It could become an economic bridge between users seeking liquidity and long-term revenue generated by Papertrade.
“A Penny for the Old Guy”
Viewed through this hypothesis, one of Blurr’s cryptic messages becomes particularly interesting:
“a penny for the old guy”
If the “old guy” were interpreted as Refund/RFD, the “penny” might represent a small share of economic value generated by newer products flowing back toward the older ecosystem.
The direction of value would therefore be:
Papertrade activity
→ Builder fees and/or PAPER accumulation
→ Refund Treasury
→ RFD ecosystem
This would be considerably more sustainable than simply spending Refund’s existing treasury on #RFD buybacks. Instead of consuming the old treasury, new economic activity could continuously replenish or expand it.
Conclusion
There is currently no direct evidence that Refund or $RFD is integrated into Papertrade’s economic model.
$PAPER appears to have a clearly defined role inside Papertrade.xyz while no published evidence currently demonstrates a Papertrade-to-RFD revenue flow.
The more interesting possibility is therefore that $RFD does not belong inside Papertrade’s core protocol at all.
Instead, Refund could theoretically, operate as a higher economic layer around Papertrade through some combination of:
Builder distribution, RFD-based benefits, PAPER liquidity, treasury accumulation and revenue capture.
In such a model:
$USDC = trading capital
$PAPER = Papertrade’s native economic/revenue asset
$RFD = potential utility and value-capture asset of the broader Refund ecosystem
The most intriguing possibility is that Refund Treasury could provide liquidity to $PAPER holders who prefer cash today over future staking income, accumulate PAPER, stake it, and redirect the resulting long-term revenue toward the Refund ecosystem.
If such a mechanism were ever implemented, it could provide both sides with something they want:
$PAPER holders receive optional immediate liquidity.
Refund Treasury acquires a potentially revenue-producing asset.
$RFD potentially gains utility and exposure to external cash flow.
🧵2/3