

Investment theses backed by deep fundamental & technical analysis
Joined August 2018
- Tweets19.5K
- Following61
- Followers2.6K
- Likes4.7K



$VKTX has given back most of its post-data pop and now trades below the $35 offering price, even though VK2735 kept up to 97% of weight loss on every-other-week maintenance dosing. With the funding overhang gone, I think the r/r is very attractive as long as the $30 area holds.
$MRNA is down about 7% today after Citi moved to Sell, arguing $200 would need about $26B in annual cancer sales. I think the bears are early, since INTerpath-001 already hit its Phase 3 primary endpoint and full data comes at ESMO on Oct 24.
$SOFI is down almost 40% this year, even though the business keeps compounding. Members grew 35% to 15.8M, products grew 42%, and the operating margin expanded to 16.9% from 13.1% a year ago. Management even raised the full-year revenue guide to 32–35% growth,
yet the stock trades at only ~21x forward earnings.
The chart is now back at the ~$15 support zone that held from March to May and again in July. As long as this level holds into Q3 earnings on Oct 27, I think the r/r here is very attractive. $SOFI
$APPS has seen some heavy swing, but the last two quarters showed a real operational trend reversal. As long as revenue & profitability growth keep improving, I’m holding my position. Now I want to see consolidation above $10, followed by a steady uptrend in line with the op dev.


$MRNA $150+ on positive cancer trial results. Massive swing winner. Cancer stocks are waking up after the market’s heavy focus on the obesity theme.
$BNTX is a $200+ stock once they announce a breakthrough in mRNA. Not to forget their very comfortable ~$20B net cash position.
$MRNA shorts are getting squeezed beautifully here.
SI still sits around 16%, more than 60M shares that eventually need to be bought back. With momentum accelerating and the technical setup continuing to improve, I think triple digits are very much in the cards on this squeeze.

$APPS broke above $14 today! The next major milestones are $20 and $25. The operational improvements (see quoted tweet) continue to strengthen the turnaround story.
On top of that, there are still over 10 shares sold short, which could provide additional upside pressure.

$APPS latest quarter highlighted the business's operating leverage. Even modest revenue growth can drive disproportionate increases in EBITDA, net income, and FCF.
The fundamentals are clearly inflecting in the right direction. In time, the share price should reflect that.


$GEVO delivered another strong quarter.
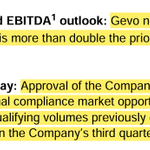
The standout was management doubling EBITDA guidance to $60M. The main negative was a $190M impairment charge, which materially reduced book value. However, it is a non-cash charge and doesn't change the company's operating outlook.

With strong expected revenue growth and improving profitability, $GEVO still looks attractively valued. Even an EV/EBITDA multiple of 10x would imply a valuation of over $2 per share
$APPS latest quarter highlighted the business's operating leverage. Even modest revenue growth can drive disproportionate increases in EBITDA, net income, and FCF.
The fundamentals are clearly inflecting in the right direction. In time, the share price should reflect that.
I believe we're witnessing another major upcycle for $APPS. Revs & profitability are accelerating, with operating leverage driving outsized earnings growth. The alternative app store is a massive opportunity post-Google-trial. Multiple expansion to 20x EBITDA would justify $25 rn

I believe we're witnessing another major upcycle for $APPS. Revs & profitability are accelerating, with operating leverage driving outsized earnings growth. The alternative app store is a massive opportunity post-Google-trial. Multiple expansion to 20x EBITDA would justify $25 rn
$APPS is exploding higher! Key breakout area on the weekly chart. Let's see this push to $20+.
Recent earnings justify a much higher valuation and multiple expansion, in my opinion.

$APPS another strong ER, with a significant upward move in AH trading. The operational improvement appears to be continuing, with rev growth of 27% YoY, EBITDA growth of 69%, and positive EPS of $0.19. The company also raised its 2027 EBITDA guidance to $150M.


$BNTX earnings were another largely uneventful update. The key factor remains the company’s strong cash position of around $20 billion, which provides management with significant financial runway and operational flexibility even as COVID-related revenues continue to decline.
For comparison, $MRNA currently holds approximately $6 billion in cash while facing a higher cash burn rate.
$APPS another strong ER, with a significant upward move in AH trading. The operational improvement appears to be continuing, with rev growth of 27% YoY, EBITDA growth of 69%, and positive EPS of $0.19. The company also raised its 2027 EBITDA guidance to $150M.
$APPS can we see $25 soon?
That still looks like the next major resistance area on the chart after smaller levels around $14, $18 and $20. Sentiment continues to turn increasingly bullish, and the strength over the past weeks has been very impressive.

$APPS For me, one of the most important developments remains the continued reduction of long-term debt, with another $10M paid down.
$CYDVF continues to look like a logical M&A candidate. A $4.01B after-tax NPV, operating costs of just $4,389/t LCE with lithium trading above $20k/t, a strategic domestic resource, and positive development news, all in a market increasingly focused on supply security.


