

Professional investor who (still) believes in rigorous research and analysis. Views, opinions, mistakes are my own - and not investment advice. JD/MBA.
South Florida, USA
Joined July 2020
- Tweets4.6K
- Following661
- Followers697
- Likes873




Grey Value Management retweeted

Whoever believes that fundamentals are not what drive stock markets should take a look at Japan!
Japan's corporate reform is delivering a massive uplift in cash returns to shareholders.
Dividend payout ratios have increased, and ongoing buybacks are returning excess capital to shareholders at levels never before seen.
A big factor in the buyback trend is the unwinding of historical cross-shareholding relationships.
So not only do shareholders experience improving capital efficiency and the benefit of a reduced share count, their companies are also becoming incrementally more subject to market discipline.
For wholesale/sophisticated investors, to learn more about the opportunities created by Japan's corporate reform, visit Senjin Capital's website, sign up to our newsletter, or book a call with us.

Grey Value Management retweeted

This paragraph from $META's inside 10-q filling may mark the official announcement that the funding environment for the AI buildout has turned the corner. (HT: Barclays' Alexander Altmann)

Grey Value Management retweeted

Holy shit, Indonesia raised it's deposit facility rate by 25 basis points.
They then CUT the share of deposits banks must keep at the central bank from 9% to 8% from November 1 and then to 7% from December 1.
Do they think this is what's going to fix everything?
Let me explain.
The deposit rate hike's objective is to stop the rupiah from falling. Essentially, if you pay the banks more to hold rupiah, they presumably won't sell it. Right?
But a reserve cut has the opposite effect, it frees about Rp190 trillion (about $10 billion) for banks to lend.
If you've caught on, they are basically trying to hold up their currency with their left hand, and then flooding the banks with their right?
Governments typically do this when they have two problems and one instrument.
Ok, so then if Rp190 trillion frees, who get's it?
The banks. And it's the three banks the sate controls. These are the same ones that hold most of the systems deposits. (Mandiri, BRI, BCA.)
It doesn't take a genius to see what they're doing: the state squeezes its banks for dividends, the stock crashes, the central bank hands the same banks $10 billion of liquidity, the stock recovers.
Talk about stockholm syndrome.
Let's see how this develops.


Grey Value Management retweeted

🦔A two-tower office complex in downtown Philadelphia was appraised at $471 million in 2019. A judge just approved its sale for $70 million. The 85% decline means even the AAA-rated bonds backed by the property will take losses, only the third time that's happened since the 2008 financial crisis.
Pimco, one of the largest bond managers in the world, holds roughly $58 million across the deal and faces over $35 million in losses. The building was 93% leased in 2020. It's 28% leased today. Over 30 other top-rated single-asset CMBS deals are now below 85 cents on the dollar, per Bloomberg.
My Take
AAA is supposed to mean you always get paid. Pimco bought that rating and is about to recover 44 cents on the dollar. The building lost 65 points of occupancy in six years and the agencies didn't downgrade the bonds fast enough for it to matter. The ratings were wrong in 2008 on housing and they were wrong here on offices.
These single-asset deals were Wall Street's favorite product for a decade. One building, one loan, slap a AAA on the top tranche. A KBRA analyst called it "binary." Either everything pays or everything defaults. That structure hides risk behind a credit rating until it's too late to get out. And the BofA head of CMBS strategy said this is just the start. Chicago, Denver, Portland, downtown LA, none of those office markets have recovered and the loans are coming due over the next two years. At a 5.13% 10-year yield, no one is going to refinance a half-empty office tower. The owners walk away, the bondholders eat it, and the AAA stamp was worth exactly what it was in 2008.
Hedgie🤗


Grey Value Management retweeted

“BOND KING” Gundlach takes aim at $CRWV and $NVDA after one of the first Nvidia GPU ABS maturities were reached. CoreWeave was unable to pay back the ABS as costs and debt/liabilities soared to over $70 billion since IPO 18 months ago. They had to sell shares and use convertible notes.
CoreWeave bonds have failed and are above 13% as executives selloff $10 billion of shares in 2026 alone (30% of company) all while the company lost access to traditional financing leaving equity and bond holders “holding the $75 billion bag of losses”.
“Gundlach took it a step further and compared it to issuing asset-backed securities that were guaranteed by bananas. "Why not do a 30 year ABS deal backed by warehouses of bananas? It's OK, they'll be newly engineered bananas of unknown life," he added.”

Grey Value Management retweeted

Here's the newest private equity structure (bottom to top):
> Layer #1 - a portfolio company borrows to fund its own buyout.
Normal course, fine.
> Layer #2 - the buyout fund that owns it borrows against its portfolio.
Ok, guess that's reasonable.
> Layer #3 - a secondaries fund buys a stake in that buyout fund, then borrows against the stake.
Getting spicier 🔥
> Layer #4 - that borrowing gets sliced into senior and junior, and the senior piece is sold to insurers, rated just high enough for them to own.
Voila. Perfection. 🤌


Grey Value Management retweeted
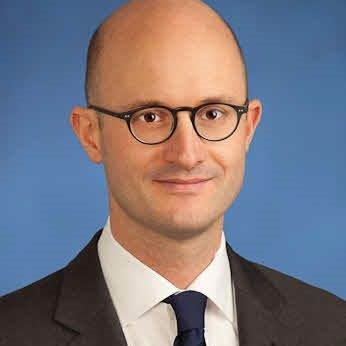
Today is a bad day for global bond markets. The problem with trying to artificially cap long-term yields - as with Treasury buybacks - is that yields jump if markets think buybacks are too small. This tells you underlying upward pressure is intense...
robinjbrooks.substack.com/p/…

Grey Value Management retweeted
🦔An NYU mathematician says OpenAI used his own progress against him to beat him to one of the biggest unsolved problems in mathematics. Tristan Buckmaster had been working toward a Millennium Prize proof using OpenAI's Codex when information about his progress reached OpenAI.
Days later, OpenAI published a full proof of the same problem using the same uncommon approach, after burning $22.5 million in compute to get there. When Buckmaster confronted them, exec Sébastien Bubeck allegedly said "Why would you ruin your career?" and "If you don't want me to be nice, then I don't have to be nice."
My Take
OpenAI spent $22.5 million to solve a problem with a $1 million prize. They didn't do this for the bounty. They needed a headline that says "our AI solved one of the hardest problems in mathematics" and they needed it before someone else got credit. They started days after they heard about Buckmaster's progress and took the same uncommon approach he'd pursued for months. That's hard to explain as coincidence.
Buckmaster did his work inside Codex. OpenAI reserves the right to train on Codex data. They admit they can't rule out that his usage helped improve their models. So a customer used their product, potentially handed them the roadmap, and then OpenAI outran him with $22.5 million in compute he could never match. I don't know if any of this was intentional. But if you're a researcher and you just watched this happen, I don't think you'd keep your best ideas inside someone else's product.
Hedgie🤗
techcrunch.com/2026/09/08/op…

Grey Value Management retweeted

150 years of market data proves that risk drops drastically the longer you stay invested.
📈 1 Year Horizon: 30.9% chance of loss.
📈 20 Year Horizon: 0.1% chance of loss.
Why do you think so many investors still operate on a 1-month to 1-year mindset despite data like this?


Grey Value Management retweeted

🚨 WE ARE NOW ENTERING THE HOTTEST PHASE
Every mid-term election year for 50 years has delivered a drawdown
1974 Ford: -35%
1978 Carter: -15%
1982 Reagan: -17%
1990 Bush: -20%
1994 Clinton: -8%
1998 Clinton: -22%
2002 Bush: -34%
2010 Obama: -17%
2018 Trump: -20%
2022 Biden: -27%
2026 Trump: ???
Ten mid-term years. Ten drawdowns. Not one skipped its turn. Average: roughly -21%.
And 2026 has more than the calendar working against it. A new Fed chair, eight weeks into the job. Across nine decades, every new chair was greeted with an equity drawdown in his first three months. Twelve chairs, twelve drawdowns, average roughly -12%. The market doesn't price a person. It prices a probability distribution. And it probes until the new chair reveals himself.
The last time both cycles overlapped: 2018. Powell takes the chair, Volmageddon hits within days, and after "a long way from neutral" the market pushes the S&P down 20% into Christmas Eve. Then Powell blinked. 2019 delivered over 30%. New chair, mid-term year, autumn washout, capitulation low, melt-up. That's the template.
Even fear has a calendar. The VIX troughs in early summer and peaks in September and October, and in mid-term years the crest runs higher. It sat in the mid-teens in early July, right at the seasonal trough. On Friday it jumped above 18. The market has started paying attention. It has not yet paid the full toll.
Meanwhile the shock absorbers are gone. Retail cash allocations at extreme lows seen only in 1998, 2000, 2018 and 2021. Put/call skew at a record low, nobody is hedging. Record IPO supply draining liquidity from the existing market.
And here's the flip: every single one of those ten mid-term drawdowns was a buying opportunity. Not most. All. Since 1934, the average rally off the mid-term low: roughly 47%. The market took out its prior high four times out of five. Bull markets don't die of drawdowns. They die of exhaustion. The mid-term correction is the maintenance schedule of the four-year cycle.
The playbook is not heroic. Hold your quality. Keep dry powder with a shopping list attached, decided at VIX 18, executed at VIX 28. Buy the fear in tranches.
The full map is out tomorrow, free for everyone. Twelve Fed chairs, ten mid-terms, the VIX season, the liquidity cycle, the 1998 rhyme. And the four tripwires that would prove it all wrong.
Greed is obvious. Fear is the edge.
When the cannons fire, buy.


Readers added context they thought people might want to know
The post lists drawdowns in only 10 of 13 US midterm years since 1974, omitting 1986 (-9%), 2006 (-8%) and 2014 (-7%). Full sample average intra-year drawdown is ~17%, not ~21%.
simianx.ai/stories/midter…
historyofmarket.com/sp500/intrayea…
blackrock.com/us/financial-p…
Grey Value Management retweeted

Carl Menger published *Grundsätze der Volkswirtschaftslehre* in 1871, and the economics profession has never fully recovered from ignoring it.
Menger didn't tinker at the margins of classical economics. He demolished the labor theory of value that had infected economic thought since Adam Smith and reached its toxic conclusion in Marx. Value doesn't originate in the hours a worker spends hammering nails. Value originates in your mind, in the mind of the individual who wants something.
This is the theory of subjective value, and it is devastatingly simple. A glass of water in Vienna costs almost nothing. That same glass in the Sahara is worth everything you own. The water didn't change. The labor to produce it didn't change. What changed is the human situation surrounding it.
Menger built his entire analysis on "goods of higher and lower order," tracing how consumer goods satisfy wants directly, while capital goods satisfy them indirectly through production chains. A sawmill (higher-order good) produces lumber, which produces your house. The value of the sawmill derives from the value you place on the house. Causation runs backward from consumer to producer, not forward from raw materials to finished product.
This single reversal demolished socialist economic planning before the Soviet Union even existed. Prices communicate real human valuations across an entire economy. Menger proved this in 1871. Central planners still haven't read the memo.

Grey Value Management retweeted

NO, THE US CANNOT GROW ITS WAY OUT OF ITS DEBT PROBLEMS
Over the past couple of weeks we have heard US Treasury Secretary Scott Bessent say again and again that the plan is to raise US GDP growth, and that this will solve the country's debt problems. US President Trump has said the same thing repeatedly for the past year and a half.
But is it actually possible?
I have run the numbers. The chart below shows the NOMINAL US GDP growth required to stabilise federal public debt as a share of GDP, given the total stock of debt, the level of interest rates and the public deficit.
The red line is the "required" nominal GDP growth if debt is to be stabilised as a share of GDP. When actual nominal GDP growth (the green line) falls below the red line, debt rises as a share of GDP.
We can see that over the past 25 years the "required" growth rate has been almost permanently above actual nominal GDP growth.
Right now the calculations show that if Bessent is to stabilise the debt, we need nominal GDP growth of 7.2%. And if the Federal Reserve is to hold inflation below 2% at the same time, we need real growth above 5% PERMANENTLY to keep the debt stable.
It ought to be obvious to anyone that this is completely impossible.
But there is of course an alternative, which is to raise nominal GDP growth through higher inflation, because from a debt perspective it makes no difference whether growth comes from inflation or from real growth. It would simply mean that the Fed would have to abandon its 2% target and accept markedly higher inflation.
The Congressional Budget Office estimates potential real GDP growth in the US at around 2.2%, so to reach nominal GDP growth of 7.2% we would need permanent US inflation of 5%.
That is of course an option - the Fed just has to print some more money. The problem is that when nominal GDP growth rises, interest rates tend over time to follow nominal GDP growth quite closely.
And worse still: if markets grow nervous that an attempt is being made to inflate away the debt problems, market rates will shoot up immediately and only make the problem worse.
So the answer is quite clear. The US cannot grow its way out of its debt problems. There is no other route - taxes have to go up and/or public spending has to come down.
The question is whether the US as a nation is capable of making those choices today. I am personally becoming more and more doubtful.

Grey Value Management retweeted
🦔Thomson Reuters just built its own AI model for about $40 million over two years. The final training run cost $450,000. They started with Qwen, an open-source model from China's Alibaba, and trained it on their own legal and news content from Westlaw, Practical Law, and Reuters. The company said the move is about reducing its dependence on Anthropic. Their CTO compared paying for outside AI to being a permanent tenant versus owning the building. Enterprise customers broadly have been cutting spending on OpenAI and Anthropic and switching to cheaper alternatives.
My Take
I covered the DeepSeek pricing collapse a few months ago and said the frontier labs would have a hard time defending premium API pricing once open-source got good enough. Thomson Reuters just did exactly what I expected someone to do. They grabbed a free model, trained it on their own stuff, and now they're pulling back from Anthropic. $40 million, done. Anthropic charges that in API fees from a handful of big customers in a year.
The $190 to $200 billion revenue projection Anthropic is selling to IPO investors assumes companies like Thomson Reuters keep paying. They just stopped. And Thomson Reuters put their model on Hugging Face for academics to use, which means the playbook is now public. I think the frontier API business has maybe two or three years before most large companies with good data figure out they can do this themselves, and the ones who move first are going to pressure the ones still paying full price to ask why.
Hedgie🤗

Grey Value Management retweeted
This is insane footage of the massive mudslide at the Nepal-China border earlier today: the mudslide, originating from Nepal, seems to have basically completely obliterated the border port in Gyirong (吉隆), Shigatse City, Tibet/Xizang.
We're likely looking at one of the worst mudslides in China's history, really bad tragedy.
For having myself lived in Nepal during several months (in the middle of the devastating 2015 earthquake!), probably the place in the world where nature is the scariest.
Grey Value Management retweeted
This rare phenomenon also occurred when the TMT/dot.com bubble burst back in 2000 and continued through 2001 as cheap "boring" stocks rallied strongly even as the market indices fall.

