

https://nitter.gq/t.co/9qq4Q1jWgU
United States
Joined October 2019
- Tweets14.1K
- Following5.7K
- Followers1.8K
- Likes32.4K



Pinned Tweet
Please check out the latest from Jacob Green 🔥🔥🙏🙏 Even is a great site to support indie music
even.biz/r/fastlane-4864a160…

Jacob Green Live retweeted

I’ve said this before.. I believe $IREN will be generating a bare minimum of $16b ARR by year end 2027. This projection is derived from a bottoms-up approach by calculating approximate GPU quantities per model across each site in $IREN's 2027 roadmap multiplied by various GPU rental rates for each model, and adding it on top of the $4b ARR minimum for 2026 (even though they'll likely generate more than this). The upper end of my model projects $22b ARR, so I’m expecting a range of $16b to $22b in ARR as of right now. This range can definitely shift higher but I aligned with Dan’s recent comments regarding the trade-off between $ per IT MW and customer prepayments. See chart below.👇
GPU Model & Quantity Assumption
The GPU quantities for each site were calculated based on the specifications across 2026 sites, assuming that gets copied and pasted into future sites.
-> ~80,000 B300s (Childress)
-> ~7,600 GB300s (Canal Flats)
-> ~132,700 VR200s (Horizon 5-6 and Sweetwater 1)
I used the EV/ARR valuation approach to arrive at projected share prices, and since there's debate on here about what multiple $IREN would receive by early 2028, I provided a range from 6x to 15x to show the possibilities. In my opinion, because ARR is expected to 4x from year end 2026 into year end 2027, and then potentially 2x the year after that, I'd think this growth rate would command higher multiples than most are using assuming, especially if we enter a bull market.
Balance Sheet
- $23b in debt (includes funding for all of 2028 buildout)
- $10b in cash
Share Dilution
I assumed 500m shares outstanding, which takes into account today's 400m shares, NVIDIA's investment (+30m shares), and dilution associated with funding all of 2028 buildout (+35m shares if diluted at an average of $50/share). All this adds up to 465m shares -> round up to 500m shares for conservatism. Keep in mind, I’m assuming customer prepayments remain the same with what we’ve seen in the past when really they’ll likely increase. This could also potentially mean less debt and/or dilution but I’m trying to be conservative with my estimates.
Also, if the GPU rental rates I laid out below represent realistic rates that $IREN could contract next year, then it makes the share prices (color coded below) that much more realistic. As I alluded to before, the range of GPU rental rates I applied may shift higher considering the rate in which pricing power is increasing, but I'm taking into account the possibility of contracting lower than expected GPU rental rates in exchange for higher customer prepayments for the foreseeable future.
On a final note, at the center of my valuation table I boxed the share price that signifies a middle ground expectation (~$375 per share). This does not necessarily represent my personal base case since I expect $IREN to hit closer to $22b ARR by year end 2027, and with a 12x EV/ARR, this would put the price closer to $500 by 2028. I've been vocal about this on here. I'm just pointing out the middle ground to challenge those claiming that $IREN will be less than $300 by 2028. To me, that doesn’t make sense as it clearly assumes $IREN contracts very low rates throughout next year.
Anyway, I hope this framework helps investors better understand the potential possibilities on what share prices we can see for $IREN based on their GPU deployments next year.
As always, constructive feedback is welcomed. @BitcoinAIGuy @bitcoinbutcher1 @Agrippa_Inv @OInvests @ChairmansLedger @ilzmcfly @mcF_dan @StockAnalystPro

Jacob Green Live retweeted

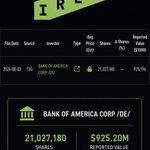
🚨 BREAKING: BANK OF AMERICA DISCLOSES 4.1% STAKE IN $IREN! 🚨
🏦 16,387,980 shares beneficially owned, according to a new SEC filing.
That’s a MASSIVE institutional position.
While retail investors panic over the recent neocloud selloff, Wall Street’s biggest players continue to show serious exposure to the sector.
🔥 BULLISH for $IREN’s long-term institutional credibility.
The big question: Is smart money positioning for the next leg higher? 👀🐂


$SPCX implied move after earnings tomorrow about 8 percent up or down - I am leaning up 😀
Jacob Green Live retweeted

$ASTS MIDLAND, Texas--(BUSINESS WIRE)--AST SpaceMobile, Inc. (“AST SpaceMobile”) (NASDAQ: ASTS), the company building the first and only space-based cellular broadband network accessible directly by everyday smartphones, designed for both commercial and government applications, welcomes the Letter of Intent signed by its mobile network operator partners Deutsche Telekom, Orange, Telefónica and Vodafone to explore a potential joint bid for Mobile Satellite Services (MSS) spectrum as AST SpaceMobile continues to advance service readiness across Europe.

Jacob Green Live retweeted

$ASTS: 🚨🇪🇺 AST SPACEMOBILE ADVANCES SPACE-BASED CELLULAR BROADBAND IN EUROPE IN COLLABORATION WITH EUROPEAN MOBILE NETWORK OPERATOR PARTNERS
Collaboration among Europe’s four largest mobile network operators expected to accelerate network integration, expand coverage and improve connectivity for the citizens of Europe
Dedicated European-operated ground infrastructure and BlueBird satellite capabilities support service readiness across more than 500 million mobile subscribers
MIDLAND, Texas--(BUSINESS WIRE)--AST SpaceMobile, Inc. (“AST SpaceMobile”) (NASDAQ: ASTS), the company building the first and only space-based cellular broadband network accessible directly by everyday smartphones, designed for both commercial and government applications, welcomes the Letter of Intent signed by its mobile network operator partners Deutsche Telekom, Orange, Telefónica and Vodafone to explore a potential joint bid for Mobile Satellite Services (MSS) spectrum as AST SpaceMobile continues to advance service readiness across Europe.
The collaboration among Europe’s four largest mobile network operators is expected to accelerate network integration, improve the customer experience and extend coverage into areas without reliable mobile connectivity. The initiative supports a coordinated approach to spectrum access and service deployment, strengthening European digital data sovereignty while enabling operators to deliver space-based cellular broadband through their existing mobile services.
“Europe’s mobile network operators are taking an important step toward extending connectivity to every subscriber, wherever they live, work and travel,” said Wayne Thorsen, Chief Commercial Officer of AST SpaceMobile. “Our role is to support our partners with the satellite technology, spectrum capabilities and ground infrastructure needed to deliver cellular broadband directly to the phones people already use. Together, we are building a third layer of connectivity that expands coverage and strengthens the resilience of Europe’s mobile networks.”
AST SpaceMobile’s existing European joint venture, Satellite Connect Europe, AST SpaceMobile is providing a dedicated network of European-operated ground infrastructure that link its BlueBird satellites with mobile operators’ core networks. This infrastructure is designed to support coverage across Europe, a market with over 500 million mobile subscribers, while keeping data handling and service control within European jurisdiction. Operators retain their customer relationships as satellite connectivity extends the reach of their terrestrial networks.
AST SpaceMobile’s BlueBird satellites feature the largest communication satellites ever deployed in low Earth orbit and connect directly to standard, unmodified smartphones, backed by 3,900 patent and patent pending claims. The company has demonstrated peak download speeds of 98.9 Mbps, with next-generation satellites expected to deliver peak data rates approaching 200 Mbps. These capabilities are designed to support voice, video and broadband services for consumers, businesses, first responders and governments.
The Company’s satellite technology can tune across approximately 1,150 MHz of mobile network operator partners’ low- and mid-band spectrum globally. Together with AST SpaceMobile’s S-band priority rights, this flexibility enables the Company to combine participating operators’ spectrum with satellite spectrum to support expanded coverage and capacity in European markets, subject to applicable authorizations.
About AST SpaceMobile
AST SpaceMobile is building the first and only global cellular broadband network in space to operate directly with standard, unmodified mobile devices based on our extensive IP and patent portfolio, and designed for both commercial and government applications. Our engineers and space scientists are on a mission to enable 4G and 5G space-based cellular broadband to every device, everywhere, for today’s nearly 6 billion mobile subscribers globally. For more information, follow AST SpaceMobile on YouTube, X (Formerly Twitter), LinkedIn and Facebook. Watch this video for an overview of the SpaceMobile mission.
businesswire.com/news/home/2…


The kids thought AI stocks would always go higher….many were likely liquidated this week sadly and probably will continue to as you can’t catch falling knives
Jacob Green Live retweeted

$IREN
IREN owns its land, power and data centers, fills them with NVIDIA GPUs and rents the compute to Microsoft, NVIDIA and leading AI labs. $4B of ARR is contracted for 2026 capacity, 8x the ~$0.5B it had in June, and another ~0.5 GW is coming in 2027. At ~$35 the company is worth ~$13.7B, ~55% below its 52-week high.
FY26 results (year to June):
• AI cloud revenue: $128.8M, ~8x FY25. Q4 AI cloud revenue of $70.5M more than doubled QoQ
• ARR: ~$0.5B at June 30, $1B operating by Aug 26 and $4B contracted for year-end
• 2026 capacity is "largely sold out", and bitcoin mining is set to be effectively decommissioned by the end of December
The contracts:
• Microsoft: $9.7B over 5 years for 200 MW of GB300s at Childress, Texas, with a 20% prepayment. Horizon 1 was delivered in August and earned NVIDIA Exemplar Cloud status, with Horizons 2-4 targeted for Q4
• NVIDIA: $3.4B over 5 years (~$0.7B of ARR ramping in early 2027), a partnership for up to 5 GW of NVIDIA-aligned infrastructure, and a right to invest up to $2.1B at $70 a share, tied to delivery of up to 600,000 GPUs
• A new multi-year contract with "a leading frontier AI lab" in August. The Information has since reported that Anthropic has an unannounced multiyear cloud deal with IREN
• $2.8B of new contracts in July. Customers include Perplexity, Cohere, Figure AI, Together AI, Fireworks AI, Fal AI and Hume AI
• Co-CEO Daniel Roberts: "The most sophisticated buyers of AI infrastructure in the world keep choosing us."
Pricing power:
• Microsoft works out to ~$9.7M per MW per year. Recent 3-year contracts are above $20M per MW of IT load, with active discussions at ~$25M
• 3-year pricing is up ~125% since November 2025, and 5-year pricing ~70%
• Recent 3-year contracts pay back the compute in ~2 years, with customer prepayments funding 45-55% of GPU capex
• Roberts: "Every megawatt we build is scarce."
Capacity and power:
• Targets of ~300 MW of IT load in 2026 and another ~0.5 GW in 2027, with late-stage talks covering a significant portion of 2027 capacity. 2028 talks are "well underway"
• ~5 GW of power under grid agreements in the US, Canada, Spain and Australia, plus a further multi-GW pipeline
• Sweetwater, Texas: 2 GW, substation energized, conditionally included as base load in ERCOT's Batch Zero, first 300 MW targeted for Q4 2027
• Childress 750 MW, Kiowa, Oklahoma 1.6 GW, Bundey, South Australia 800 MW and Badajoz, Spain 300 MW
• NVIDIA Vera Rubin (VR200) systems are already on order
• Mirantis, acquired in August, has served 1,500+ enterprise customers, and its k0rdent AI platform is integrated with NVIDIA DSX software
Funding:
• ~$14B of cash, committed GPU financing and prepayments, after ~$19B secured over the past 12 months
• $6.5B of GPU financing in 3 months, including $3.6B investment grade at ~6% for Microsoft and $2.4B led by Blue Owl and PIMCO. With prepayments, that funds over 100% of the related GPU capex
• 100% of IREN's data centers are unencumbered
Valuation:
• ~$13.7B, about 2.9x the $4.7B of ARR contracted for 2026 capacity plus NVIDIA.
• NVIDIA's right to invest is at $70 a share, about 2x today's price
• Average analyst target ~$78. Bernstein is at $100, Northland and Cantor at $99, B. Riley at $91, and Macquarie and H.C. Wainwright at $90
• ~82M shares are sold short, ~21% of shares outstanding
Why I think Wall Street is far too conservative:
• Wall Street has revenue of ~$2.8B for the year to June 2027 and ~$7.3B for the year to June 2028
• The 2026 contracts plus NVIDIA already add up to $4.7B a year, and 2027 adds ~0.5 GW more
• If that 0.5 GW prices like recent 3-year deals at $20M+ per MW, the run-rate exiting 2027 is $13B+, well above the $7.3B
• JPMorgan went straight from Underweight to Overweight in September
I expect IREN to do significantly more revenue than Wall Street models, and I think current price targets are far too low. I'm long Iren.