

SEC-registered RIA (registration≠skill). Info=education, not advice. Crypto is high-risk. Disclosures: https://xitter.cf/t.co/yUu1vY3ZGQ
Colorado
Joined February 2025
- Tweets53
- Following33
- Followers105
- Likes41



Protocol Wealth retweeted

This is the moment we built Protocol Wealth for.
When we started the firm, we saw a clear gap.
People who had built significant wealth in Bitcoin, protocol tokens and other digital assets deserved professional financial advice. They needed sophisticated wealth management, thoughtful custody structures and advisers who understood both traditional finance and the onchain world.
That combination was difficult to find.
Then the bear market arrived. Protocol tokens fell sharply. Even major digital assets experienced significant declines. Planning felt less urgent.
But every market cycle tends to produce the same lesson:
During the bull market, people assume it will continue.
During the bear market, they wish they had made a plan while prices were higher.
Now, market activity is returning - but this moment is bigger than another crypto cycle.
Stablecoins are becoming more widely used for payments and yield. More traditional assets are being tokenized. A greater share of personal wealth will be represented on blockchains and potentially used within DeFi.
Investors will still need help answering familiar questions:
• How much risk am I taking?
• How concentrated am I?
• What should I sell, retain or diversify?
• How does this wealth support my family and long-term goals?
But they will also face newer questions:
• How should these assets be custodied?
• Which wallets, platforms and smart contracts are appropriate?
• How do I evaluate on-chain opportunities and their risks?
• How do I move safely between traditional and on-chain financial systems?
That is what we have been preparing for.
We’ve combined decades of traditional financial experience with deep knowledge of crypto, DeFi, wallets, custody and security. We’ve built the technology, reporting and operating systems needed to advise clients across both worlds.
AI is becoming part of that evolution as well - not as a replacement for judgment, but as a tool to operate more efficiently and do more for clients while protecting their information.
For @JasonLeupold, @nickryg and me, this is the convergence we anticipated when we started @Protocol_Wealth.
And it feels like the work is just beginning.
Protocol Wealth retweeted
We’re nearing the second tax season of the year. At the same time, we see several major token unlocks coming, while many others are still vesting a bit every month.
Fortunately, values have crept back up in the past few weeks.
solana:J6pQQ3FAcJQeWPPGppWRb4nM8jU3wLyYbRrLh7feMfvd
$MONAD
hyperliquid:native
ethereum:0x57e114b691db790c35207b2e685d4a43181e6061
$PUMP
So now what?
Now we’re helping clients plan for those unlocks and vesting. It isn’t just a numbers and markets exercise. It's a discussion, and it's different for everyone.
How much cash do you want or need?
How do you feel about the future of your project and token value?
What does your family think about the risk?
Have you addressed taxes and estate planning?
Of course, those personalized questions go along with the realities
How many tokens are unlocking?
Who is likely to sell vs. hodl?
Are there staking or other yield options?
It's ok for each person in this situation to have a different plan. As a matter of fact, you should. Your plan should reflect the realities of the market, and the realities of your family.
That’s why @nickryg, @JasonLeupold and I started @Protocol_Wealth …because generic advice doesn’t cut it for complex, personal situations.
Protocol Wealth retweeted
A liquidity event can feel like the finish line.
You sold the business.
Your company went public.
The token launched.
Your stock or options suddenly became meaningful wealth.
Congratulations.
Now the planning starts.
Because “having wealth” and “having usable liquidity” are not always the same thing.
There may be lockups.
There may be vesting schedules.
There may be taxes due before you have the cash to comfortably pay them.
You may need cash to exercise options.
You may be deciding whether to sell now, wait for long-term capital gains treatment, or continue holding a position that already represents a large percentage of your net worth.
And beyond all of those technical decisions is a much more personal question:
What do you actually want this money to do for you and your family?
That answer should influence almost everything that comes next.
The right plan for someone who wants to buy a home, create financial independence, or step away from work may look very different from the plan for someone who wants to keep building, invest aggressively, or create multigenerational wealth.
That’s why there really isn’t a generic answer for what to do after a liquidity event.
The earlier you start planning, the more options you generally have.
But even if the event has already happened, there is still plenty of planning to do.
This week I’m going to spend some time talking about liquidity events, concentrated wealth, equity compensation, taxes, and—most importantly—how all of those decisions fit into the life you’re actually trying to build.
@Protocol_Wealth
Protocol Wealth retweeted
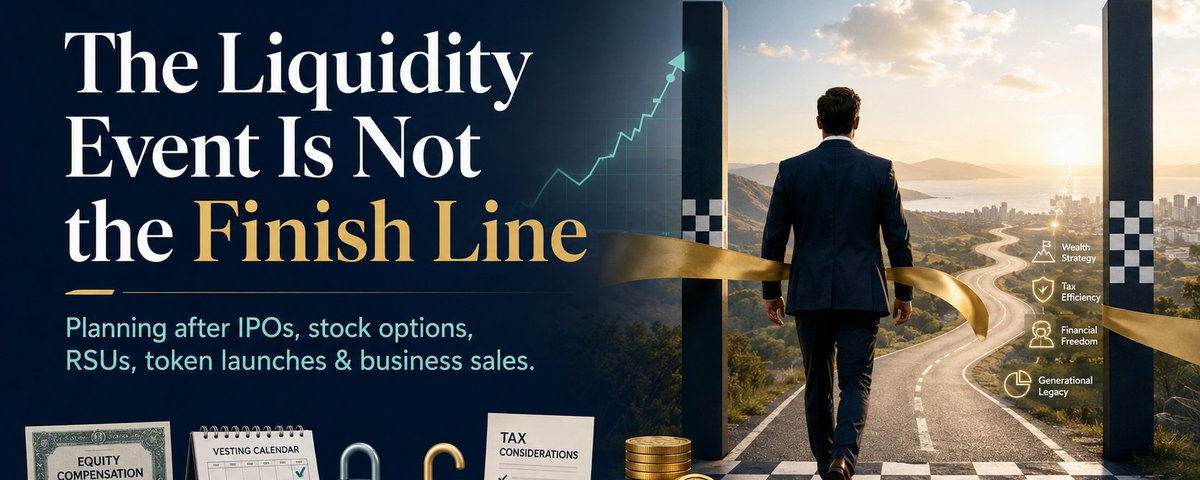
A liquidity event can feel like the finish line.
Your company goes public.
Your options become valuable.
Your RSUs vest.
A token launches.
But financially, that’s often when the real planning begins.
How much is actually liquid?
What do you owe in taxes?
How concentrated is your wealth?
And most importantly:
What do you want this money to do for you and your family?
My latest article, “The Liquidity Event Is Not the Finish Line,” looks at the decisions executives and employees should be thinking about before - and after - their equity becomes real.
@Protocol_Wealth

Protocol Wealth retweeted
We have a new client with an unlock coming in a few weeks.
But we already started the planning
- Understanding the contract and unlock/vesting terms.
- Coordinating with the tax attorney and CPA to understand the tax ramifications.
- Discussing with the family tom make sure they understand their needs and goals, as well as the risks involved.
- Creating strategies for upward or downward movement in the asset price.
When the unlock day comes, of course we're hoping for the asset to go up.
But we, and more importantly our client, will be prepared for any movement, and have a plan.
Control what you can control.
@Protocol_Wealth
Protocol Wealth retweeted
If you think the bottom is in, don’t wait for the next upswing to make a plan.
I’m not in the business of predicting prices. Digital asset markets are volatile, and any number of events could send prices higher—or lower.
But if you believe your portfolio may be poised for renewed growth, now is the time to ask:
• Is my custody strategy still appropriate?
• Could my family access these assets if something happened to me?
• When will I take risk off the table or diversify?
• Do yield opportunities fit my strategy and risk tolerance?
• At what prices will I begin selling?
• What would those decisions mean for taxes and estate planning?
Planning is easier before prices start moving quickly and emotions enter the picture.
We may have reached the bottom. We may not have. Either way, having a thoughtful strategy in place can help you respond deliberately instead of reactively.
@Protocol_Wealth
Protocol Wealth retweeted
A family can have a multimillion-dollar net worth after an IPO—and still not have the cash to make a down payment on a house.
That’s the difference between paper wealth and usable wealth.
In this case, most of the family’s new wealth is held in company stock, restricted stock units, and stock options. It looks substantial on a statement.
But buying a house requires something different:
Cash for the down payment.
Assets and income that work for mortgage qualification.
Enough money left over for taxes and other obligations.
Creating that cash involves several connected decisions:
→ Which vested shares should be sold?
→ What are the cost basis and holding periods?
→ Which options should be exercised—and when?
→ Where will the exercise cash come from?
→ Could exercising incentive stock options create an AMT obligation?
→ How much should be reserved for taxes?
→ What happens if the stock falls before the family can act?
These decisions may need to begin months—or more than a year—before the planned home purchase.
The objective is not simply to sell enough stock for a down payment. It is to create the necessary liquidity, manage the tax exposure, preserve enough cash for future obligations, and decide how much company risk the family can reasonably continue holding.
A liquidity event can increase net worth overnight.
Turning that wealth into something that supports your actual life takes planning.
If a home purchase or another major goal is on the horizon, the time to connect it to the equity strategy is before the cash is needed - not after.
Educational only. This is not individualized investment or tax advice. Equity-compensation and tax decisions should be evaluated with qualified financial and tax professionals.
@Protocol_Wealth
Protocol Wealth retweeted
“Not one advisor in this room knows what to do with five years of sideways.”
An older broker-dealer owner said that to me at a financial-services conference a few years ago.
I’ve been thinking about it again.
A generation of investors and advisors has been trained around a simple playbook:
Buy the dip and wait for equities to recover.
But what happens if the market doesn’t quickly recover?
What if stocks move sideways for several years—or volatility produces dramatic rallies and declines without delivering consistent growth?
The economy does not stop.
Businesses still need capital.
People still need to borrow.
Investors still have capital they want to put to work.
Risk still needs to be financed and insured.
This is where I think the conversation about crypto often becomes too narrow.
Crypto is not only a bet that token prices will rise.
Blockchain rails can broaden access to parts of the financial system that have historically been difficult for many investors to reach directly:
→ Lending and credit markets
→ Insurance and shared-risk pools
→ New forms of capital formation
These markets do not depend solely on public equities moving up and to the right.
But the larger idea is important.
If the next market cycle includes prolonged sideways movement, the answer cannot simply be to keep waiting for the next equity-market rally.
We need more ways for people to participate in lending, risk-sharing, business formation, and the broader movement of capital.
That is one of crypto’s most compelling possibilities:
Not replacing the entire financial system—and not promising effortless yield—but opening more of it to transparent, programmable participation.
Crypto may matter most when “number go up” is no longer enough.
h/t @TR401
@Protocol_Wealth
Protocol Wealth retweeted
If your digital assets are moving up again, don’t just ask how high they could go.
Ask whether the structure around them is ready.
We’ve recently started working with several clients who are preparing for greater liquidity, including tokens coming out of lockup.
Before focusing on what or when to sell, we’re examining the infrastructure supporting the wealth:
• Where are the assets held—and is that still the right custody model?
• Are keys, recovery procedures, and family access properly documented?
• Could a spouse or fiduciary access the assets without searching for a 24-word seed phrase?
• Are smart-contract, counterparty, and concentration risks understood?
• Do yield strategies match the client’s liquidity needs - or create lockups at the wrong time?
• Should assets and strategies be spread across multiple custody and yield solutions?
For some clients, that means evaluating MPC wallets through our partner @FordefiHQ. For others, it means improving backups, coordinating custody with the estate plan, reviewing smart-contract coverage, or dividing assets into liquidity buckets with different time horizons.
The goal isn’t to predict the next move.
It’s to make sure that if your wealth grows, the systems protecting it grow up too.
A bull market can create wealth. It can also magnify weaknesses that were easy to ignore when prices were lower.
If you hold significant digital assets, the best time to address custody, access, liquidity, yield, and estate coordination is before one of those weaknesses becomes urgent.
Every situation is different, and this is not individualized financial, tax, or legal advice.
@Protocol_Wealth
Protocol Wealth retweeted
Your IPO lockup may not be one date. It could be several releases—each with different tax, liquidity, concentration and trading decisions.
The goal isn’t four separate strategies. It’s one strategy with multiple checkpoints.
@Protocol_Wealth

Protocol Wealth retweeted
Using AI to help your liquidity event planning
Yesterday I published an article about managing your finances during a liquidity event. It goes for those who have an IPO or token unlock coming up, or even have public equity or tokens as part of your compensation.
So...since I know you're going to use AI anyway
Take the article, as well as any of your equity or token-comp documents, and throw them into your AI tool of choice.
Ask it to fill in the 2 tables we detail in the article.
Now you have the beginning of a plan.
@Protocol_Wealth
xitter.cf/Interaxis8/status/2092…
Protocol Wealth retweeted
Yesterday, I shared an article about planning for concentrated wealth.
There is a reason I keep coming back to this subject.
We often meet people who are worth millions of dollars on paper but do not feel financially secure.
Most of their wealth may be tied to one company, one token, or one investment they have held for years. Selling it can feel like abandoning the conviction that created the wealth. But continuing to hold everything can leave their taxes, home purchase, family goals, and long-term security dependent on that one asset behaving perfectly.
The conversation is rarely as simple as, “Should I sell?”
It is usually:
- How much liquidity will I need?
- What happens if the asset falls substantially?
- How do I prepare for taxes, vesting, or an unlock?
- What portion of this wealth needs to become independent of the asset that created it?
- And what do I actually want this wealth to make possible for my family?
That is why concentrated-wealth planning is not simply an investment decision. It is a coordination problem involving risk, liquidity, taxes, security, and real life.
The goal is not necessarily to eliminate the concentrated position.
It is to make sure the rest of your financial life does not depend on it behaving perfectly.
@Protocol_Wealth
Protocol Wealth retweeted
“If you had invested in gold five years ago…”
“If you had bought Bitcoin 15 years ago…”
“If you had gone all in on NVIDIA…”
Those comparisons may be interesting, but they are not especially useful for most people.
We don't make financial decisions with the benefit of hindsight. We make them while living real lives - with expenses, families, taxes, unexpected events, changing income, and goals that often require actual cash.
Even if you identified the winning investment early, would you have had the money to invest heavily? Could you have held it through every decline? Would you have resisted taking profits after it doubled, tripled, or increased tenfold?
There is nothing wrong with having strong conviction in an investment. But conviction should still be evaluated alongside the rest of your financial life.
Good planning comes down to two things:
First, plan for the life you actually have. Understand what you need your money to accomplish, which risks you can afford to take, and how much liquidity you may need along the way.
Second, make the best decisions you can with the information available today.
Then keep reevaluating:
Has the investment changed?
Has your conviction changed?
Has your financial situation changed?
Does the position still make sense within your overall plan?
We know what happened in the past. We have some understanding of what is happening now. The future will always remain uncertain.
The goal is not to build the portfolio that would have been perfect in hindsight.
It is to make thoughtful decisions that allow you to invest - and live with the uncertainty ahead.
@Protocol_Wealth
Protocol Wealth retweeted
The same amount of wealth does not create the same financial plan.
We recently began working with several new clients who occupy different parts of the founder ecosystem. Some founded companies or protocols. Others were members of the founding team or early investors.
Their total wealth may be relatively similar, but the composition of that wealth - and the lives it needs to support - could not be more different.
One holds a significant portion in liquid tokens. Another has exposure to several tokens. Another owns pre-IPO stock. Each has different unlock schedules, liquidity constraints, custody considerations, tax exposure, and potential sources of yield or income.
Their personal circumstances are just as varied: single, newly married, married with children, homeowners, and people living in different states.
Those differences affect nearly every planning decision:
• How much liquidity they need
• Where monthly cash flow will come from
• How assets should be held and secured
• How to prepare for unlocks or vesting events
• What risks should - and should not - be taken
• Whether life and disability insurance are important
• How taxes may influence the timing of decisions
A portfolio is only one part of a financial plan.
The real question is: How can this wealth support the life this particular person or family wants to build?
Four people can have roughly the same net worth and require four completely different strategies. That is why good planning begins with the individual - not the asset.
@Protocol_Wealth
Protocol Wealth retweeted
Concentrated wealth is often how significant wealth is created. The problem is not the concentration itself - its allowing every family goal, tax obligation, and future decision to depend on one asset continuing to perform perfectly.
We explore how founders, executives, and digital asset investors can preserve conviction while building a more resilient financial plan.
@Protocol_Wealth

Protocol Wealth retweeted
Ran a treasury workshop with 3 protocols last month.
One booked a call before they left the room.
What surprised me: none of them knew their market maker wasn't required to act in their interest.
Full story in this week's Protocol Briefing 👇
xitter.cf/Interaxis8/status/2049…

Protocol Wealth retweeted
I'm heading to @Consensus2026 Miami next week.
I'm managing Wealth Management Day, which means I've spent the last few weeks thinking about what conversations actually matter right now — not the ones that make the main stage, but the ones happening in hallways and side rooms.
Here's what I'm most interested in this year:
Treasury management accountability. The protocols that raised in 2021 and 2022 are now managing real treasuries through real market cycles. Some are doing it well. Many are not. I want to talk to the teams who are serious about getting it right.
The fiduciary gap. There are a lot of people giving financial advice in crypto. Very few of them are legally required to act in your interest. I think this is the most important structural problem in the space right now, and I want to have that conversation with more people.
Founders who are also building personal wealth. The best founders I know are running a company and building a life at the same time. Most of them have no one helping them think about the personal side — keys, estate, liquidity, taxes. That's a solvable problem.
If you're going to be in Miami, DM me. I'd rather have a real conversation than exchange cards.
@protocol_wealth

Protocol Wealth retweeted
Most founders think about fiduciary duty in one direction — to their community, their token holders, their protocol.
But there's another fiduciary duty almost no one talks about.
The one you have to yourself.
When you've built something that generated real wealth — when your token holdings, equity, or treasury position represents years of work and risk — you have an obligation to manage that wealth with the same rigor you'd expect from anyone managing money on your behalf.
That means:
Documenting your decisions. Why you hold what you hold. What would trigger a change. What your liquidity plan is. Not because you need to justify yourself to anyone — but because undocumented decisions are emotional decisions, and emotional decisions in volatile markets are expensive.
Diversifying systematically, not reactively. Most founders diversify after a crash, not before one. That's not a plan — that's a response. A fiduciary approach means setting a diversification schedule before you need one, when you're not under pressure.
Planning for continuity. If something happened to you tomorrow, could your family access your assets? Could your protocol continue operating? Custody and succession planning aren't morbid — they're responsible. And they're the first thing an institutional investor asks about.
Coordinating across disciplines. Tax, estate, investment, and custody decisions interact. Making them in silos — with a CPA who doesn't know your estate plan, and an estate attorney who doesn't know your token vesting schedule — is how gaps become expensive mistakes.
The founders I work with who do this well share one trait: they treat their personal wealth with the same intentionality they bring to their protocol. Not because they're required to. Because they've seen what happens when you don't.
You built something real. Manage it like it is.
Protocol Wealth works with crypto founders on the institutional-grade financial infrastructure that protects and grows what they've built.
@protocol_wealth

Protocol Wealth retweeted
I was talking to a friend who manages a treasury for a well-known protocol at the Digital Asset Summit recently.
I asked him: "What's the difference between managing a treasury for a TradFi company versus in the crypto world?"
His answer was immediate: "This world is harder because everyone sees what you're doing."
In TradFi, treasury management is a back-office function. It's critical for keeping the lights on, but it's not a public exercise.
In crypto, managing a protocol treasury—or your own founder token allocation—is entirely different. It is relentlessly public.
→ Everyone wants to weigh in (and in a DAO, they get to).
→ Everyone can see the treasury wallets.
→ Everyone can see what's happening on-chain.
If a risk manager leaves or a strategy shifts, it doesn't stay in a boardroom. It gets pasted all over X, debated on LinkedIn, and dissected on podcasts.
Because of this transparency, there needs to be significantly more foresight into how assets are managed. You can't just "sell tokens" or "provide liquidity" without a plan. You know you're going to get scrutinized. You know there are OPSEC and governance issues at play.
The reality is that crypto founders and treasuries have far more options for what they can do with their assets than traditional companies. But with those options comes the need for a strategic, survival-first approach.
Transparency is a feature of this industry, not a bug. But it means your treasury strategy needs to be built before the scrutiny starts, not in response to it.
If you're a founder or managing a protocol treasury, how are you preparing for this level of public oversight?
Let's talk about building a strategy that holds up to the scrutiny.
@Protocol_Wealth