

Tech investor for ~25 years. Ran large hedge fund for 10 of those. Here to help. Not investment advice. I never reach out to sell ANYTHING.
NYC
Joined July 2018
- Tweets2K
- Following351
- Followers19.5K
- Likes2.5K

Ok, it might be over folks.
Anthropic revenue disclosure maps to ~5.8b in September revenue or 70b ARR which means August / September only increased by 2-3b ARR in each month.
[There is no way that ARR is calculated using last day of the month as that would be more aggressive than anything I've ever seen out of companies this size (exception: Musk).]
Worst monthly numbers by far this year. (Maybe some self-infliction from cleaning up distillation?).
My rough math indicates OAI / ANT ARR monthly add softened from 16b in July to 10b in Aug to 9b in Sept. That is no bueno...
Supportive of the view that either CAPEX is getting cut or pricing is going to weaken substantially.

OpenAI at 70b net never really made any sense intuitively.
Still seems like net ARR added in September was 17b similar to 17b in August. 17b is still pretty ridiculous and suggests we finish the year ~200b gross across ANT / OAI.

@a16z put out a solid deck today on State of AI.
Does a good job of just putting it all together - AI capabilities rapidly expanding, AI model revenue ramp unprecedented, semi spend underneath unprecedented and driving earnings growth of the entire stock market, and multiples reasonable due to cyclical concerns.
To me, the "elephant in the room" question is simply will AI monetization accelerate over the next couple years from what likely will be ~200b run-rate at the end of this year.
Very rough math, but we added ~170b of model revenue in 2026 against 1.4t of capex over the past 3 years and 780b in 2026.
Expectations per chart below are for 1.1t of capex in 2027 which then flattens. Maybe that implies the model companies in aggregate need to add ~200b of ARR each year to justify that spend?
Is that possible? Sure but also tough to assign probability bc there are a million unanswerable questions underneath (product development, pricing power, etc.).
That's also the bear case for semis for a future date: even if model companies plus others can add ~200b / year of incremental revenue, that implies semi spend stagnates after 2027 -> second derivative turns negative and multiples stay low until the inevitable downturn.
I personally think 2028 is probably a 20-30% growth year in capex so the whole trade is more likely to up than down from here at these valuations, but just pointing out the risk that the market is pricing in here (and that has to dissipate via continued ARR growth / hyperscaler capex growth commentary to see the trade run).
[Btw, I also think it's so fascinating that leading investment firms are also publishing leading news / research. This free newsletter from A16Z smokes independent publications (WSJ, Gartner, etc.), and the sell-side (less conflicted in some ways and more informed)]


Should have added that OAI simply saved down that I have $FDS and will just use it when it needs to going forward....!
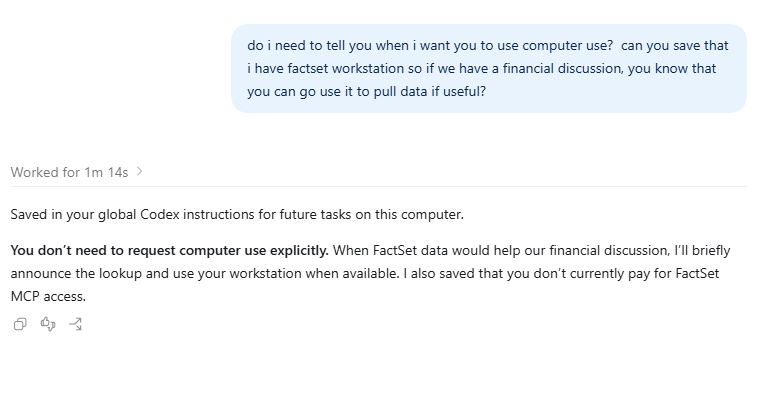
Another day, another bit of AI functionality, and another question as far as incumbents...
So I previously tested $FDS MCP which was a huge advance for AI financial functionality, and a growth driver for $FDS subscriptions (call it 20% uplift to enable).
And then today I tested just using OAI's computer use on the regular desktop session, and it worked pretty well albeit a lot slower.
Kind of funny how quickly some of the SaaS bear points from earlier this year are materializing...
In this case, it's that usage of the SaaS app becomes more automated from outside and becomes unmonetizable...
(Separately, being bullish on $CRM Claudeforce is really puzzling to me - that felt more like a defensive point for the SaaS won't go away tomorrow than an offensive point for SaaS will participate in AI).

I'm really curious to know what percent of $GOOGL / $AMZN ad spend consists of brands buying sponsored listings for their own search terms - basically spending to defend their own screen turf from competitive ads.
See below for searches for Speedo Goggles:
GOOGL: The entire visible screen is sponsored ads which Speedo has to pay for. The next screen down has Speedo in a thin organic result followed by a Deals market ad where Speedo again has to pay for shelfspace.
Using Gemini search for "Find me speedo goggles" only showed Speedo branded goggles.
AMZN: Speedo has an organic link in the bottom left and right, and otherwise is surrounded by competitive listings. Interestingly Speedo not paying up here (maybe realized using branded term this close to checkout means consumer is buying Speedo regardless).
Using Alexa AI search for "Find me speedo goggles" only showed Speedo branded goggles.
I personally find GOOGL / AMZN search results to be over-monetized w/ ads that don't add value - and, in fact, make it more annoying for me to find what I want.
AI search for products on AMZN works really well for me fwiw so I must already be seeing far fewer ads simply by this usage shift.
I don't really know what happens to this "traffic defense" spend in an agentic world. Feels like it would be less necessary in a world where agents need to be trustworthy to win consumer preference. So hard to imagine I ask an agent for speedo goggles and it spends 80% of the answer discussing competitive brands like regular search results do today...
Maybe consumers always want choice so there is room for other brands to pay to be mentioned within the AI results - while still not being dilutive to the consumer's experience?
Or, maybe agents can find the best 2-3 products so less need for brands to advertise within search and just put those dollars towards improving product quality / Internet posts to drive agentic preference?
Random thoughts...


$QQQ forward P/E has averaged ~25x for the past 10 years.
It currently trades at ~20x the 2027 EPS estimate.
Let's assume a big recession in semis. I cut the 2027 EPS estimates for NVDA, AVGO, AMD, MU, LRCX and AMAT by 50%.
$QQQ is then trading at 24.5x the revised 2027 EPS.
Obviously, that isn't going to happen but shows that the market is already effectively pricing in an outcome like that already. [Maybe that's too optimistic and market would trade at 20x EPS in that scenario which would present 20% downside from here if it were to unfold].
I'm not smart enough to have a view on 2028 yet but doesn't feel like capex is going to get cut materially unless Anthropic / Open.AI growth dramatically decelerate.
Separately, AI in Excel is pretty solid. Just obvious to me AGI is already here.

