

Tech investor for ~25 years. Ran large hedge fund for 10 of those. Here to help. Not investment advice. I never reach out to sell ANYTHING.
NYC
Joined July 2018
- Tweets2K
- Following351
- Followers19.5K
- Likes2.5K


Re: ANT S1
What's the take on META / Cursor moving to in-house models given the language below?
Seems either very clever phrasing (Q3 was peak but then eroded thereafter) or, more likely, the big customers are still fine. Or META isn't a top 5 customer.
"At the same time, our largest customers continue to expand. For the three months ended September 30, 2026, our revenue from each of our top five customers reached a record high."
The slowdown in Q3 was partly attributed to inhousing but seems like that may not have happened?
Seems like we may be good to go here:
-AI functionality is genuinely mind-boggling and ROI is obviously there (not categorically of course). People who say otherwise might as well try to convince me the sky is green. I just don't see it that way based on my lived reality.
-OAI growth expectations tempered from irrational. Funding will be completed soon.
-ANT had a soft Q3 but should accelerate in Q4. S1 looks great - no gotchas. Positive surprises in a lot of places - particularly with improving compute margins and being solidly FCF positive. IPO will get done at reasonable price. ($DXYZ).
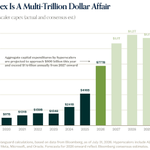
-SPCX / META spending / capital raise plans already out there / getting completed.
-Hyperscaler earnings likely all positive.
-Semi supply constraints likely limit spending growth in 2027 regardless of customer balance sheets / appetite. Helps de-risk pace of investment and lower probabilities of a big digestion period in 2028.
-Multiples basically at trailing lows w/ US yields stabilizing / improving.
-Momentum selloff pretty fierce compared to priors w/ X filled w/ AI bears doing victory laps. So always better to be buying into negativity.
Let's see.
Seriously? Slack, INFA and now next-gen ET (BRZE)? DATA may be useless in a few years although AI obviating it isn’t there bad M&A.
Their bad M&A is literally half the reason the multiple stays low.
Great thoughts. Thx.
Curious if you have thoughts on the concern that there are now 5 players spending half their AI compute budgets on training more or less the same AGI model. So arguably half the spend is duplicative investment.
And that the models already seem pretty good for most things so maybe a rationalization post-AGI leads to a glut that isn’t far off.
I suppose that might then suggest ad potential on Muse is real. I wouldn’t mind seeing ads for other dress shoes - even if they don’t meet the criteria which Muse is using for its search.
Thx. Didn’t catch that. I’m sure they will revisit that down the road but not a good sign for monetization near term.
3 random thoughts on $META
1) Re: The Cheeky Pint podcast - It's kind of crazy they admitted that their AI buildout is a huge bet that will have "very, very, very bad" financial consequences if it doesn't work out. Especially bc monetization is likely far into the future so doesn't that suggest 2027 potentially sees material EPS headwinds as the depreciation comes online?
I get it. There isn't a way to be competitive in AI w/o making big infra bets and I'm sure they were excited in the moment about Muse success. But certainly pulled the curtain back a bit...
2) Muse is great. I get a monthly note on all local events in my area (sports, music, theater, restaurants, etc.). I paid two parking tickets with it. And I have it looking for a new pair of dress shoes and a PS5 Pro (we haven't found either to my liking so the search continues).
But I'm not sure what else to do with it so I haven't checked the app much after that.
3) I assume the Muse data will be added to the knowledge graph. That's interesting bc now META knows far more about me and my ongoing searches. I would think that has to improve targeting / pricing on core META properties.
As opposed to just showing me general products that match my interests / pixel data, they now know that I am in need of new dress shoes on an ongoing basis since the search is still outstanding - and I would think advertisers that have shoes exactly like or even adjacent to what I'm looking for would want to target me on FB / IG.
Anyways, the thought is maybe monetization of Muse actually first shows up as higher monetization of core META.
Good point. Although if I were management and supply constraints limited growth, I would definitely say that in the S1 / meetings.

This exchange:
Analyst "So, should we expect a re-accel to maybe 100-110b by year-end"
Anthropic CFO: "We aren't commenting on forward looking figures but believe in a large opportunity over time"
Analyst "Got it" [Writes down "management didn't talk me down from 110b"].
For what it's worth, I think Anthropic ARR and revenue are both gross per their consistent commentary that they are the principal in transactions.
So the revenue and ARR tie nicely, and mention of 85% GMs likely means the cloud partner share is categorized as S&M.
So I think this all foots.
And, fwiw, Claude says cleaning up distillation is at most 500m / mo headwind so that's not it. But apparently company is saying otherwise?
I'm not meeting with Anthropic today so I don't know - but I would have to imagine that if that explanation is significant, it is definitely being discussed.
Because otherwise the M/M growth implies a dramatic slowdown.
Ok, it might be over folks.
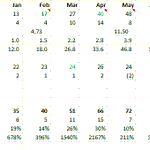
Anthropic revenue disclosure maps to ~5.8b in September revenue or 70b ARR which means August / September only increased by 2-3b ARR in each month.
[There is no way that ARR is calculated using last day of the month as that would be more aggressive than anything I've ever seen out of companies this size (exception: Musk).]
Worst monthly numbers by far this year. (Maybe some self-infliction from cleaning up distillation?).
My rough math indicates OAI / ANT ARR monthly add softened from 16b in July to 10b in Aug to 9b in Sept. That is no bueno...
Supportive of the view that either CAPEX is getting cut or pricing is going to weaken substantially.

Thx for the thoughts.
I think the pushback would be great models are available from 5-10 players who have been neck and neck forever, so seems like inference margins will be quite low over time (although I hear your point that this isn't a certainty), and that LLMs don't seem to present a distribution threat for now.