

Analyst @MilkRoadAI | Finding opportunities across the AI value chain
See my portfolio →
Joined February 2022
- Tweets2.2K
- Following139
- Followers1.6K
- Likes1.6K





Pinned Tweet
WHY BLOOM ENERGY $BE COULD BE THE AI PLAY FOR 2026
——
The AI boom has a boring problem.
Electricity.
You can’t scale power like software.
Wires, transformers, permits, years.
But hyperscalers are competing on months.
That timing gap is creating a new category: „on-site power that shows up fast“
That’s where Bloom Energy enters.
——
A) What Bloom actually does
Bloom sells on-site power for data centers.
Think “power plant in a box” next to the facility.
Fuel cells produce electricity via an electrochemical process (not the
burn-and-spin turbine setup).
For operators, the use case is simple.
If the grid can only give you 50 MW,
but your campus needs 300 MW,
you can supplement the missing power on-site.
——
B) Why the market suddenly cares
Two forces collided.
Grid expansion is slow and political.
AI demand is compounding fast.
Global data center electricity demand is projected to more than double by 2030 to ~945 TWh.
That scale forces new solutions.
Also because traditional solutions like gas turbines are sold out and nuclear takes too long!
In one recent discussion, Bloom cited a survey showing data centers planning on-site generation jumped from 13% to 38% in about six months.
That’s a real “tipping point” signal.
⸻
C) The 3 moats that matter
1) Speed and uptime-style reliability
Speed is the first moat.
Bloom can deploy its systems at scale within ~90 days.
Also they build these systems as modular ~65 kW building blocks.
So maintenance events are small, not one big turbine down, ensuring 99% uptime.
2) Low emissions and easier community acceptance
Second moat: local footprint.
They emphasize “no combustion” at the point of generation, and they highlight the system being quiet (around ~65 dB).
That matters when communities push back on noisy, dirty backup-style setups.
3) Lower total cost of ownership
Third moat: economics.
If you include TCO (not just fuel price), Bloom is often framed as ~20% lower TCO vs. gas turbines and others.
Especially once you factor in lead times, maintenance windows, and the cost of delay.
In an AI race, time-to-power is part of the bill.
——
Key takeaway
Bloom Energy is perfectly positioned to benefit in an environment where customers need
- 24/7 reliable energy
- fast energy deployment
- low emission energy
- grid not able to supply enough
= AI datacenter boom

The only one is being a sales representative at a cyber-security company atm
nitter.gq/wallstengine/status/21…

J.P. Morgan says third parties that provide services to the firm were the target of a CYBER ATTACK, and it believes attackers accessed certain marketing data held by the vendors, which may include some customer names and email addresses.


63
Vincent retweeted
who will pay more?
what does it to the culture?
who will get a raise and who not?
do nvda employees care about money?
to many risks around $NVDA


who will pay more?
what does it to the culture?
who will get a raise and who not?
do nvda employees care about money?
to many risks around $NVDA
Vincent retweeted
Nvidia without Jensen = me losing a lot of conviction in $NVDA
Why? 5 core reasons.
1) No successor bench. In March, Jensen said his direct staff was 60 people. Nvidia is a kingdom built around one king, and he's gone.
2) I expect rivals now try to poach NVDA's best engineers.
3) Founder-led Nvidia took long, risky bets like CUDA. A new CEO gets less room for bets like that.
4) Jensen personally held the key sales and supplier relationships. That's gone (see post of Elon recently).
5) Open source gets harder to defend without Jensen and with export controls under scrutiny.
We are probably all in NVDA as a buy-and-hold, not a short-term trade. So, the ultimate question is what will drive up the multiple of this stock again?
The last 3 quarters showed growth of 73%, 85% and 106%, and the P/E multiple crashed regardless.
With Jensen out, reclaiming higher multiples will be harder, not easier.

Nvidia without Jensen = me losing a lot of conviction in $NVDA
Why? 5 core reasons.
1) No successor bench. In March, Jensen said his direct staff was 60 people. Nvidia is a kingdom built around one king, and he's gone.
2) I expect rivals now try to poach NVDA's best engineers.
3) Founder-led Nvidia took long, risky bets like CUDA. A new CEO gets less room for bets like that.
4) Jensen personally held the key sales and supplier relationships. That's gone (see post of Elon recently).
5) Open source gets harder to defend without Jensen and with export controls under scrutiny.
We are probably all in NVDA as a buy-and-hold, not a short-term trade. So, the ultimate question is what will drive up the multiple of this stock again?
The last 3 quarters showed growth of 73%, 85% and 106%, and the P/E multiple crashed regardless.
With Jensen out, reclaiming higher multiples will be harder, not easier.
At least some good news in AI today: AI agent traffic on websites went vertical!
a16z data shows AI agent requests on websites up about 8x from August-October.
That's agents visiting, and more and more of them are actually shopping.
Shopify's $SHOP Q3 shows AI traffic up 2.6x YoY, AI orders up 3.3x AND AI referrals converted 64% better than organic search!
As MUSE, GrokBot and others only scale from here, all the companies welcoming AI agents as economic entities will see massive growth in volume!
Think $HOOD $SHOP and others.

Vincent retweeted
Democrats potentially slowing new AI data centers could be very bullish for $SPCX
If AI demand keeps growing while new compute supply arrives later, SpaceX could gain significant bargaining power.
The agreement between $SPCX and $ANT allows either side to exit with 90 days’ notice after the initial lock-up periods end in early 2027.
If the supply-demand imbalance widens, SpaceX could use that flexibility to exit and negotiate a higher price.
And if already-approved data centers get built in 2027/28 while new approvals slow, my bet is that Elon brings the most new compute online.
Could this be the path to >$500B in ARR in 2027?

Are the election results slowing down the AI buildout and thus increase the value of operational compute AND force the reduction of CapEx?
so, buy $SPCX and hyperscalers?

Democrats potentially slowing new AI data centers could be very bullish for $SPCX
If AI demand keeps growing while new compute supply arrives later, SpaceX could gain significant bargaining power.
The agreement between $SPCX and $ANT allows either side to exit with 90 days’ notice after the initial lock-up periods end in early 2027.
If the supply-demand imbalance widens, SpaceX could use that flexibility to exit and negotiate a higher price.
And if already-approved data centers get built in 2027/28 while new approvals slow, my bet is that Elon brings the most new compute online.
Could this be the path to >$500B in ARR in 2027?
Are the election results slowing down the AI buildout and thus increase the value of operational compute AND force the reduction of CapEx?
so, buy $SPCX and hyperscalers?
Vincent retweeted
Elon Musk is personally putting in the manual labour to get data centres built!
At Colossus II in Memphis, he describes walking the whole site several times a day, pulling power cables, running fiber, wiring switches and working on plant-management software himself.
He says he even lives in an Airstream beside a power plant!
WHICH OTHER CEO IS WILLING TO DO THAT?
The value created from this is obvious:
Doing the work helps him understand the difficulties crews face. For example, if a piece of electrical equipment keeps holding up a data hall, standardising it or ordering earlier could prevent the same delay at the next site.
The goal is to turn those lessons into a process that teams can run themselves, across multiple sites. Getting powered compute online sooner means it can start earning revenue or training Grok sooner.
What's clear is that Elon's 100% focus is on building data centres atm, which is scary for everyone else involved!
Elon Musk is personally putting in the manual labour to get data centres built!
At Colossus II in Memphis, he describes walking the whole site several times a day, pulling power cables, running fiber, wiring switches and working on plant-management software himself.
He says he even lives in an Airstream beside a power plant!
WHICH OTHER CEO IS WILLING TO DO THAT?
The value created from this is obvious:
Doing the work helps him understand the difficulties crews face. For example, if a piece of electrical equipment keeps holding up a data hall, standardising it or ordering earlier could prevent the same delay at the next site.
The goal is to turn those lessons into a process that teams can run themselves, across multiple sites. Getting powered compute online sooner means it can start earning revenue or training Grok sooner.
What's clear is that Elon's 100% focus is on building data centres atm, which is scary for everyone else involved!
Vincent retweeted
Was talking about $PLTR the other day on Milkroad pod!
Remains the ultimate AI adoption bet with LLY imo. Great buy after the dip!

Alex Carp is calling for Palantir's US Commercial revenue to his $15B alone by 2028, while the street has the ENTIRE company at $17.8B!
For context: commercial is only 50% of the business today!
But not only is Palantir scaling its customer base, more importantly, its Net dollar retention also went from 157% to 165%. What this means is if you spent a dollar with Palantir last year, you spent $1.65 in the third quarter
Once they're inside a company or inside the government, they just keep going deeper, because they're creating that much value. Nobody is getting rid of them
And their job of turning an ROI for its customer is getting easier and easier as models get cheaper and smarter. There is a consistent tail wind behind Palantir because of this
I think thats the part the market is missing about Palantir. It continues to look at what is possible today and forgets about how fast these models are getting cheaper and smarter and what that unlocks for new use cases
Palantir continues to be an incredible company and I don't see what stops them anytime soon
Was talking about $PLTR the other day on Milkroad pod!
Remains the ultimate AI adoption bet with LLY imo. Great buy after the dip!
Alex Carp is calling for Palantir's US Commercial revenue to his $15B alone by 2028, while the street has the ENTIRE company at $17.8B!
For context: commercial is only 50% of the business today!
But not only is Palantir scaling its customer base, more importantly, its Net dollar retention also went from 157% to 165%. What this means is if you spent a dollar with Palantir last year, you spent $1.65 in the third quarter
Once they're inside a company or inside the government, they just keep going deeper, because they're creating that much value. Nobody is getting rid of them
And their job of turning an ROI for its customer is getting easier and easier as models get cheaper and smarter. There is a consistent tail wind behind Palantir because of this
I think thats the part the market is missing about Palantir. It continues to look at what is possible today and forgets about how fast these models are getting cheaper and smarter and what that unlocks for new use cases
Palantir continues to be an incredible company and I don't see what stops them anytime soon
Vincent retweeted

Alex Carp is calling for Palantir's US Commercial revenue to his $15B alone by 2028, while the street has the ENTIRE company at $17.8B!
For context: commercial is only 50% of the business today!
But not only is Palantir scaling its customer base, more importantly, its Net dollar retention also went from 157% to 165%. What this means is if you spent a dollar with Palantir last year, you spent $1.65 in the third quarter
Once they're inside a company or inside the government, they just keep going deeper, because they're creating that much value. Nobody is getting rid of them
And their job of turning an ROI for its customer is getting easier and easier as models get cheaper and smarter. There is a consistent tail wind behind Palantir because of this
I think thats the part the market is missing about Palantir. It continues to look at what is possible today and forgets about how fast these models are getting cheaper and smarter and what that unlocks for new use cases
Palantir continues to be an incredible company and I don't see what stops them anytime soon

Vincent retweeted
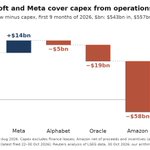
Hyperscalers now spend more on AI than their businesses bring in!
In the first nine months of 2026, they generated $543B of operating cash flow but put $557B into CapEx.
Only Microsoft and Meta covered their CapEx from cash.
However, I expect that we are close to a peak in terms of external financing, and we are reducing the "risk" gradually.
Gavin Baker agrees, saying recently: “I don’t know if we’ve seen the peak of external financing, but I think we’re getting close.”
The argument is that cloud growth is accelerating, older compute contracts signed below market rates could reprice higher, and high margins could turn that growth into enough operating cash to fund more of the 2027 buildout than investors expect.
I think the market will be bullish once that comes to light!

Hyperscalers now spend more on AI than their businesses bring in!
In the first nine months of 2026, they generated $543B of operating cash flow but put $557B into CapEx.
Only Microsoft and Meta covered their CapEx from cash.
However, I expect that we are close to a peak in terms of external financing, and we are reducing the "risk" gradually.
Gavin Baker agrees, saying recently: “I don’t know if we’ve seen the peak of external financing, but I think we’re getting close.”
The argument is that cloud growth is accelerating, older compute contracts signed below market rates could reprice higher, and high margins could turn that growth into enough operating cash to fund more of the 2027 buildout than investors expect.
I think the market will be bullish once that comes to light!