

A tremendous slouch. Former payments and fintech analyst. Investor and writer. Dad and aspiring pro golfer. This is not financial advice.
St Louis, MO
Joined April 2025
- Tweets2.1K
- Following242
- Followers3.4K
- Likes4.4K





Trump: We must win the AI race against China at all costs. Voters rejecting data centers are ‘backwards’ and will be ‘poor’.
Also Trump: My primary AI ally, arguably one of the most powerful men in the world, is having a romantic relationship with a Chinese spy. Nothing to see here.
Democrats should (and will) have a field day with this issue.
Politicians still figuring out how toxic inflation is. As the party not in power, it’s easy to talk about, but fixing it while you’re in office is a whole different matter, and a potentially painful one.

We have now had two U.S. elections in a row where incumbents got wrecked because of "the economy" even though, by most objective measures, the economy was doing incredibly well on the eve of *both* elections (and maybe even accelerating slightly).
2
4
778
AI and Data Centers
Nearly 60% of voters cited AI and data centers as a crucial or major factor in their vote during the mid-term elections. Those voters broke 2-for-1 for Democrats. It was the most lopsided issue for Democrats, even above the war in Iran and government corruption. There were 45ish ballot measures on data centers nationwide on Tuesday, only one passed. Maybe I’m not cynical enough about politicians, but it’s hard to see Democrats slapping some superficial requirements on data centers and AI companies and letting construction and development continue as before. Also, it does not appear Trump is backing off his support for AI AT ALL, making it more likely that Democrats could dig their heels in on this issue. Finally, why should Democratic representatives, senators, and governors care about whether stock prices go up or down, their constituents do not. Trump’s problem is and was that is all he cares about.
FYI: Sold the last 500 shares of $FOUR at $41.23. I’m out. Hope to share fuller thoughts on lessons learned in the coming days, but in the end, the (potential) economic incentives of owning this stock did not align with the mental capacity it required. I was wrong to hold this stock as long as I did, and I may certainly be wrong selling it now, but my involvement is over.

Thoughts on the payments names coming out of Q3 earnings based on my confidence levels:
$V $MA $SHOP - Pristine but on the expensive side, SHOP especially
$TOST 1a - $XYZ 1b, but on the rise for sure
$FISV - seems like they've reset the base and better days are ahead, more uncertain on core banking
$ADYEN - demand is there, but investments and NT profitability are a big ?
$GPN - Like what they're saying, but the #s need to catch-up, namely got to get organic revenue growth above 5% in 27, ideally 6%
$FOUR - total wildcard at this point, don't know where organic GRLNF growth is going to bottom
1
12
2,218
Couple thoughts $FOUR. Seems to be a challenge for them to forecast/communicate their business, which is never a good sign. The framework they laid out for FY27 of MSD-HSD organic revenue growth is disappointing, and could possibly put them at the middle/lower end of $FISV (6-8%), $GPN (5-6%) and $FOUR IMO. Pedal to the medal on share buyback seems diabolical. They bought $200M in Q3. $FOUR is not alone (b/c I've seen it happen w/other companies too) but I'll never understand why when you have a forecast/framework in hand that you know is going to move the stock appreciably lower (which for certain they should've known would be the case), you're in the market buying back so much stock? Then again, if the outlook deteriorated that much in the last part of Q3/first month of Q4, then that's a whole different issue altogether. I'll never make a snap decision to sell, but certainly that's very much on the table right now.
2
14
2,001
$FOUR: What else is there to say. Q3 looked in-line, but Q4 guide is bad w/GRLNF just +3.5% at midpoint, and adj EBITDA -3.5% at midpoint ($292M vs. $328M consensus). Saying travel disruptions more pronounced in Q4 and weaker SSS. No one else is saying that. Stock's down mid-teens.
4
25
4,325
$GPN Earnings: Looked fine to me. There's no PR to sell the company, so I guess some people could be disappointed by that. Interestingly, in the presentation, each one of its segments - SMB, Enterprise and Platforms - reported a 1-point improvement in organic revenue growth from Q2 to Q3. Overall, organic revenue growth was >4% vs. just 4% last Q. Very modest I know, but improvement nonetheless. Keeping guidance unchanged and lifting expense synergy target for Worldpay to $650M from $600M.
4
1,337
Flipped the 250 shares of $FOUR at $44.32 just now, retaining the 1k position heading into tomorrow's earnings. Yes, I'm a wimp, but feels like a good day to lighten up in a few spots.
$FOUR: While I had issues with the stock in the $70-80 range, at $36, the risk/reward seems quite favorable IMO. As a result, I've increased my position by 25% to 1,250 shares. Buy price was $36.16. I think the company's far from 'dead' even though the stock is priced that way.
1
8
1,842
Just took a look at the final results for the Senate races and the margins across the Sun Belt are almost unbelievable. Needless to say, if the shift has any staying power for Dems, almost certainly catastrophic for Republicans in 2028 and beyond.
1
2
755
Trump made a lot of poor decisions, with the Iran war probably the most inexplicable of all, but I don’t feel like people grasp the unpopularity of AI outside of technologists and investors (which is what X mostly is). Obviously, it was primarily to pump markets, but I’ll never fully understand why he went to bat so forcefully on this issue, it’s a losing one.
$XYZ: Not complaining b/c the stock is up on the numbers, but they look okay, not great, especially Cash App PBAs, volume, and inflows, all slowing by a non-trivial amount. Square is actually better IMO w/volume/GP both +14% and the +20% food/beverage GPV matching $TOST. I think losses were not as bad as feared and people like the +15%/+30% GP/AOI marker being set for 2027, with a similar pattern of upside surprises as we've seen in 2026.
$XYZ: I think the market (myself) would like (need) to see a few things in Q3 results: Square GPV growth at or above last Q’s 13%, with little to no daylight b/w it and GP growth; Cash App commerce enablement volume growth maintaining a healthy high-teens growth rate; acceleration would be better to match $CHYM, along w/an uptick in PBAs. To be honest, on credit, I’m sure what the market’s looking for is either a cooler # and/or more color about loss rates by product (as opposed to generic terms like ‘healthy’). I’ve got no idea if they can deliver a cooler # but if past is prologue do not hold your breath for greater detail. Good luck!
11
1,959
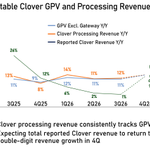
In my mind, one of the bear's key arguments for SMB-aligned payments companies ($FISV $GPN $XYZ $FOUR $TOST) is that there is somehow a 'race to the bottom' on pricing for core processing services. This chart, along w/data from the others, clearly refutes that argument IMO. If you hold share and price in a secularly growing market, that is a recipe for revenue growth that is highly attractive relative to valuations.
A really nice chart for $FISV showing Clover processing revenue growth tracking volume growth closely, suggesting stability in pricing for core payment processing services.
