

Yardstiq connects you to 1000s of interviews w/ the world’s largest network of software buyers. Access first-hand intel on quality, competition, pricing & more
New York, NY
Joined August 2022
- Tweets150
- Following1
- Followers393
- Likes22






YARDSTIQ retweeted

🧩🎯 M&A strategy teardown
Why did @HubSpot ($HUBS) acquire @clearbit?
TL;DR
1. The obvious near-term opportunity is going after @ZoomInfo $ZI
2. More interestingly, this really sets up a longer-term fight with @LinkedIn Sales Navigator (owned by $MSFT)
First, let's talk ZoomInfo
A quick look at @CBinsights interview transcripts with software buyers shows that Clearbit was already battling and beating ZoomInfo
As this buyer highlights, vs $ZI, Clearbit was "overwhelmingly the best database for the companies we sell to".
Add in it was already integrating with Hubspot which likely allowed the HUBS corp dev team some insight into the product's value/usage by customers
While the above comment is a signal of volume, this conversation transcript highlighted Clearbit winning over ZoomInfo because they "had a higher accuracy rate with our total addressable market"
In our scorecard of data enrichment vendors based on these interviews, we see CSAT for ZoomInfo lags other players including Clearbit
Interestingly, here is where we also saw LinkedIn Sales Navigator enter the chat which did score higher than Clearbit
And so the medium-term target of Hubspot is likely LinkedIn's Sales Navigator business
The reality is customers already see them as competitors
And so by the transitive property of M&A*, ZoomInfo and Hubspot are now competitors.
It's hard to tease out exactly how big the LI Sales Navigator business is but some data we've gleaned:
* In 2016, LinkedIn Premium Subscription were $155M (prior to closing of their acquisition by MSFT
* The business now goes by different names so it's hard to know exactly where Sales Navigator now sits and MSFT disclosures on it are minimal, but we do know that LI Sales Solutions grew to $1B+ in revenue by 2021
So needless to say that LI Sales Navigator has been incredibly fast growing, big and sticky.
And now Hubspot has a competitor and additional product arrow in its quiver to capture a slice of that Navigator pie
Of course, there are tons of other players in the data enrichment space which also pose challenges for ZoomInfo and LI Sales Navigator including @MeetApollo, @RocketReachCo, @Cognism and @LushaData
So this deal also portends more M&A / consolidation in the space
Here is a snapshot of still private ZoomInfo competitors from CB Insights
* transitive property of M&A competition
If A is a competitor of B and B is now acquired by C, then C is now a competitor of A


ALT Clearbit vs Zoominfo best database

YARDSTIQ retweeted
1 area of generative AI facing headwinds is...
...the text generation & editing space
Earlier this week Jasper, valued at $1.5B, replaced its CEO
And earlier this year, Grammarly, valued at $13B, also named a new CEO
There are lots of highly valued companies in this space as the graphic from @CBinsights below highlights
The challenge these players face is the result of 2 things:
1. Huge, well-capitalized competitors attacking
2. Lofty valuations which may be tough to grow into
--ON COMPETITION--
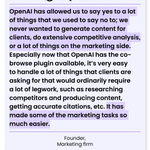
chatGPT from @OpenAI is a problem
And so are @Google and @Microsoft as they integrate AI capabilities into MS Word, Google Docs, etc
When we talk to their customers, they bring this up repeatedly.
The big dogs are innovating quickly as this buyer highlighted in this conversation (source: @yardstiq)
And the large competitors are also putting immense pricing pressure on players like Jasper as this customer highlighted in this @yardstiq interview transcript
It's not competition only from the large incumbents.
@Grammarly understandably and logically, is attacking the enterprise market but there, they are running into players like @Acrolinx
This conversation with a Fortune 500 customer of Acrolinx highlights that they evaluated Grammarly as well, but it didn't have the integrations they required
--LOFTY VALUATIONS--
The other challenge for players in the text generation and editing space are skyhigh valuations which may be challenging to grow into.
Some of the most highly valued players in the space per @cbinsights are:
* Grammarly $13B valuation
* Jasper $1.5B
* Writer $500M
What about valuation multiples:
Jasper 16.67x (2022 multiple) based on a reported $90M of 2022 revenue
For comparison, @Turnitin, a Grammarly competitor was acquired by family office Advance for $1.75B in 2019 and was reportedly doing $130-170M the year prior
That would give Turnitin a 10.29x - 13.46x revenue multiple
By this comp, Jasper's multiple isn't crazy provided they can keep growing despite pricing and competitive pressures and keep churn under control
At the high end of that range (13.46x), Grammarly would need to be doing almost $1B of revenue (~$970M) to justify their $13B valuation
Grammarly was bootstrapped in its early years and admirably keeps a low profile so CB Insights hasn't picked up on any recent whisper revenue numbers
But for comparison, OpenAi is on track for $1B in revenue this year. Translation: $1B is a big-ass revenue number and is no joke
The boom in generative AI isn't ending anytime soon, but if there is a pocket of weakness within it, it is in the text content generation and editing space
WDYT?
Anyone seeing tailwinds for companies in this space that makes the valuations look reasonable or even a bargain?
As always, if any of my assumptions are wrong, feel free to comment and if it changes the analysis dramatically, I'll edit
--SOURCES--
Source for all quantitative and qualitative info and screenshots is CB Insights or Yardstiq (a CBI product)
Jasper company profile - app.cbinsights.com/profiles/…
Grammarly company proifle - app.cbinsights.com/profiles/…
Text content generation and editing market report -
app.cbinsights.com/market-re…


YARDSTIQ retweeted

Here we go
@deel backed by @a16z is looking at taking on @Rippling
Dig into Deel's valuation and the competitive global payroll provider market here
app.cbinsights.com/profiles/…

YARDSTIQ retweeted

$SNOW Vendors’ feedback on using Snowflake and it’s advantage over Databricks (per Yardstiq).

