



Chris retweeted
Call me crazy...
But maybe the fact that 3 MILLION people in Paraguay just had their salaries, pensions, and savings frozen...
...while every American news network spent the last 48 hours hyper-focused on election night...
is not a coincidence.
Ueno Bank.
60% of all adults in the country.
Accounts locked.
App dead.
Branches guarded by police.
Central bank stepped in after the solvency ratio cratered below half the legal minimum.
State pension funds exposed for hundreds of millions.
Depositors locked out overnight.
And almost nobody in U.S. media is talking about it.
Because election coverage is easier.
And infinitely more convenient.
Chris retweeted

The tech bubble started in 95-96 when Netscape went public. It countinued when capital poured in and exploded in 98-99. I began trading NQ in 97. In 99 as we rallied every day to new highs, I focused on my process and my process alone. I didnt know enough about anything else to get in my own way yet.
In March of 2000 the bubble burst. The high of the NQ was 4882, by Oct of 02 we made a low of 790. That is the biggest break in the market since 1929, the NQ broke 85%. It took almost 17 years and trillions in QE, credit expansion and artificially low interest rates to achieve that price again.
There are some similarities between that and the AI bubble, there are differences. However, the geo-political situation today is MUCH more precatious then then-that is the wild card.
BE CAREFUL!!!!!! I know I know, every dip is bought, BLAH BLAH FUCKING BLAH. It is till it aint. Be careful.
Cash IS a position.
If I am wrong, I do not care. I would rather deploy capital at higher prices then to lose a significant part of my net worth in a true bear market........
I would ALWAYS ALWAYS rather give something up on my reentry than to average in a loss.
Have a blessed weekend!!!!!!
None of this is financial advice, this is my own direct experience.



Chris retweeted

🚨 NOMURA: THE MARKET MAY BE MISREADING THE ENTIRE AI DATA CENTER BOOM.
Big Tech is spending hundreds of billions on AI infrastructure. Free cash flow is under pressure. Investors are worried the AI boom isn't profitable.
But Nomura argues something very different:
AI infrastructure is already highly profitable. The cash flows simply haven't caught up with the investment cycle.
Here's the breakdown 🧵👇
1/ The profitability numbers tell a different story.
According to Nomura's November 2 report:
• AWS revenue: $46B, +39% YoY
• AWS operating margin: 38.7%
• Google Cloud revenue: $30.7B, +103% YoY
• Google Cloud operating margin: 36.2%
• Azure growth: +48%
These are not the numbers of an industry struggling to generate operating profits.
2/ The real issue is timing, not necessarily profitability.
Big Tech pays for data centers, GPUs, networking and memory upfront.
Revenue and cash generation arrive over subsequent years.
That creates a classic free-cash-flow J-curve:
CAPEX accelerates → FCF deteriorates → Infrastructure generates revenue → Investment growth moderates → FCF recovers.
3/ Nomura expects operating income to surge before free cash flow.
Its illustrative forecasts suggest operating-income growth could peak around 2029, while FCF growth accelerates later.
That distinction matters enormously for investors valuing AI infrastructure businesses.
4/ Why can't hyperscalers simply stop spending?
Because AI increasingly threatens their existing businesses.
Search, advertising, shopping, software and cloud services are being reshaped by AI agents.
Companies that underinvest today risk surrendering customers, data and market share tomorrow.
5/ Demand may not be the primary constraint. Capacity is.
Nomura cites enormous contracted cloud backlogs:
• Google Cloud: $560.8B
• AWS: ~$496B
• Microsoft commercial RPO: $677B
These figures have different reporting definitions, but collectively illustrate substantial contracted demand.
6/ Big Tech has financing alternatives to cutting CAPEX.
Nomura identifies four paths:
① Accelerate investment
② Freeze CAPEX
③ Use joint ventures and operating leases
④ Monetize contracted future cash flows
Its preferred expectation is continued investment supported by increasingly sophisticated financing structures.
7/ Oracle offers a real-world example.
Nomura highlights Oracle's combination of long-term leases, project financing, customer prepayments and customer-provided hardware.
The broader message: hyperscalers can restructure who finances infrastructure without necessarily reducing how much infrastructure gets built.
8/ This distinction is critical for semiconductors and memory.
Negative hyperscaler FCF does not automatically imply collapsing demand for GPUs, DRAM, HBM or other data-center components.
If spending continues through financing structures, semiconductor demand can remain resilient even while hyperscalers optimize their balance sheets.
9/ What could invalidate the thesis?
A genuine compute oversupply.
Watch:
• Cloud revenue growth
• GPU rental pricing
• Contracted backlog growth
• Data-center utilization
• Memory supply commitments
• Hyperscaler investment guidance
These are more useful indicators than negative FCF alone.
10/ The investment takeaway:
The key question is not simply:
"Why is Big Tech burning so much cash?"
It is:
"Will the infrastructure being built today generate enough durable cash flow to justify its cost of capital?"
Nomura is optimistic.
But the answer ultimately depends on pricing, utilization, investment discipline and the durability of AI demand.
The AI infrastructure cycle may be a cash-flow timing problem rather than a profitability crisis.
$NVDA $MU $GOOGL $MSFT $AMZN $META $ORCL


Chris retweeted

Remembering John Candy in his birthday. 🙏😔
He brought so much joy to so many people. In fact, he still does. A legend and an amazing soul.

Chris retweeted
Fuck.
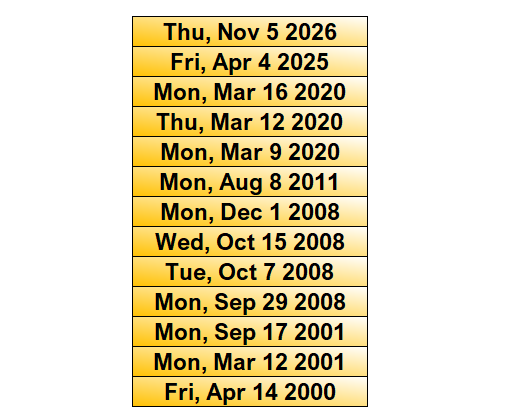
For absolutely no reason whatsoever, here is a list of every time in QQQ history where it
▪ Gapped down -2.5% or worse
▪ On a Friday
▪ Following a -1% day
- 3 times in 2001
- Jun 2002
- Oct 2008
- Twice at the beginning of COVID
- Liberation Day
- Possibly today