
Retired Investment Pro. Battle Tested after 3 decades. Straight Talk on Macro, AI Infrastructure & Digital Assets. No Hype. No Fluff. Mindset is Everything.
Heath, TX
Joined February 2021
- Tweets14.5K
- Following374
- Followers2.8K
- Likes23.6K






Phil DeSantis, CFA 🇺🇸 retweeted

Shoutout to @JaguarAnalytics @PDphillyPhil who have been vocal on this.
Phil DeSantis, CFA 🇺🇸 retweeted

This is heavily misleading. Yes, the cost per token is going down but with every token cheaper the use cases broaden. If it costs 1M tokens to run a query in an LLM and it costs 1T tokens to cure cancer the value per token is less, but the price someone is willing to pay in aggregate is way more because the returns are substantially higher. Or take robotics for example, where once it economically makes sense to train models on 1T tokens because of the returns on the other side. A bunch of companies enter in and set a baseline floor for that new use case in token consumption. Hence Jevons Paradox.
Phil DeSantis, CFA 🇺🇸 retweeted
Bond market is already sniffing out $CRWV running into issues being a buyer of GPU’s without owning the physical infrastructure. Spreads for investment grade colocation deals despite this remains tight. The market is going to have a rude awakening once it understands that the scarcity comes from the power, labor, permits, and capital that allows the chips to be brought online. Equity markets shoot first and take down the colocation/neocloud sector without differentiating and understanding the implications. $IREN $CIFR $WULF $NUAI


Phil DeSantis, CFA 🇺🇸 retweeted
"In bear markets, stocks return to their rightful owners." - J.P. Morgan

Phil DeSantis, CFA 🇺🇸 retweeted

AI could be extremey bad for equities.
- Pure AI companies face brutal competition as token prices go to zero. Massive bloodbath for pure LLMs, Impossible to justify economics.
- Normal companies find their moats dissapearing as AI startups clobber them.
Buy Bitcoin.
Phil DeSantis, CFA 🇺🇸 retweeted
The IREN strategy is flawed and I think mgt knows this but was forced in this direction.
The majority of their clients will be either out of business or on their backs in 2-3yrs.
IREN needs everything to go perfect for them and I don’t see it happening………….
IREN is a stock that can maybe be traded but I don’t see the cloud strategy succeeding and they certainly don’t have the marketing dollars long term to compete. Short term contracts and below IG customers will be the death of this company.
Market it ✅
$IREN
Phil DeSantis, CFA 🇺🇸 retweeted

Big update from Northland on $NUAI. 👀
Their previous $12 target assumed just 45% ownership of TCDC through a JV.
With NUAI now pursuing hyperscalers directly, Northland models 95% ownership, pushing its implied valuation to $20/share.
Same project. Much more upside retained by shareholders.
The boys @optionology and @fnitefiend are getting even more excited. 🔥
Phil DeSantis, CFA 🇺🇸 retweeted

$NUAI’s gay price action is definitely part of it.

Few remember that $IREN round-tripped to ~$5 twice before it went on its legendary run.
$NUAI price action is giving me the exact same kind of déjà vu.
We’ll see who survives the shakeout.
youtube.com/watch?v=Dz5VzLz6…

Phil DeSantis, CFA 🇺🇸 retweeted

$NUAI is on the radar now bc a lot of very smart ppl have put it there. There’s a reason for that.
It’s incredibly hard on X to work out who actually knows their shit, but from my interactions w/ the ppl around this name, the quality of the group is a level above most others I’m in.
Obvs I don’t care whether you own it. I’m not selling you anything.
But I do know what getting to the next level of wealth can change in your life, and if anything I post helps a few ppl get there, that’s worth something to me.
I’ve been pretty clear about how I see $NUAI.
As they say, you’ve been warned.
Phil DeSantis, CFA 🇺🇸 retweeted
$NUAI These guys are absolutely on fire 🔥🔥🔥
If you’re following the NUAI story, give these guys a follow:
@fnitefiend @LovedropV @optionology
Great research. Great updates. No subscriber fee and no satellite photos…
Next part of our $NUAI work with @optionology and @fnitefiend
We mapped what we believe are the next major catalysts:
• Letter of credit by Oct 9
• Non-binding tenant LOI in the next ~2 weeks
• Macquarie funding
• Final lease agreement in the next ~45 days
These dates are our estimates based on public information and commentary, not company guidance.

Phil DeSantis, CFA 🇺🇸 retweeted
More and more breadcrumbs keep showing up around $NUAI and TCDC.
Starting to feel like we’re connecting the dots in real time 👀
Piece by piece, the story keeps getting clearer.
@optionology @shwogud

We heard big news from the Ector County Commissioners Court today about $NUAI and its TCDC project! The judge said that now that the 200 MW power deal is signed, "this is starting to become a reality." New Era asked for no tax breaks and will pay the full rate, which could mean HUNDREDS OF MILLIONS in property taxes, back to the community. The county is getting ready for this to be built, and it's a huge win for the local community. @LovedropV @fnitefiend

Phil DeSantis, CFA 🇺🇸 retweeted

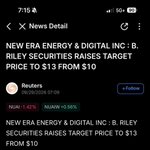
B. Riley just raised its $NUAI target to $13 from $10 and kept its Buy.
That's a 30% jump from the firm that started coverage at $10 in July.
The timing stands out. Last week New Era set up a $100M program to sell shares at market prices (an ATM). An analyst raising the target while the company is raising cash suggests they think the money buys real growth, not just time.
Small cap, big swings. But conviction is going up, not down.
Long $NUAI Not financial advice.
news.google.com/rss/articles…
Phil DeSantis, CFA 🇺🇸 retweeted

J.P. Morgan: WHY BEHIND-THE-METER (ONSITE) WINS
BTM’s core advantage is speed-to-power, roughly 12-18 months vs. ~5 years for grid interconnection, enabling earlier monetization
“We view regulatory changes and local opposition to grid-connected data centers as tailwinds, with expectations that 50%+ of incremental data center capacity (2028+) could be BTM-powered.”

Phil DeSantis, CFA 🇺🇸 retweeted

The last time the 10-year bond yield was this high was July 2007.
Three months later, the global financial crisis started.
The Nasdaq crashed 56% over the next 16 months.


🚨 THIS IS NOT LOOKING GOOD.
Entire US bond yield curve is going parabolic.
US01Y is at a 25-month high
US02Y is at a 28-month high
US05Y is at a 19-year high
US10Y is at a 19-year high
US20Y is also at a 22-year high
US30Y is at a 19-year high
Higher yields across the board mean higher borrowing costs for the government, businesses, and consumers, and that's bad news for both the economy and stocks.

Phil DeSantis, CFA 🇺🇸 retweeted
Being early isn’t free.
The market charges rent on every thesis.
Opportunity cost, dilution, funding risk, theta. Your own patience.
You can be completely right about what a co becomes and still lose money bc you got the timing or structure wrong.
“I was right eventually” is not the same thing as a good investment.
Phil DeSantis, CFA 🇺🇸 retweeted
🧵 Northland’s new $NUAI note has a few very important takeaways:
They expect management to spend the next couple of weeks commercializing the initial ~757 MW of TCDC capacity, not just the 207 MW Phase 1.
207 MW Vistra PPA + 550 MW Thunderhead BTM.
That is a much bigger story than a standalone Phase 1 lease.

RT @optionology: $NUAI was built for exactly this! Abbott’s letter today paused Texas data center permits until ERCOT finishes its audit an…
Phil DeSantis, CFA 🇺🇸 retweeted

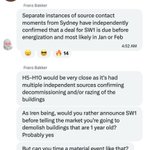
For those wondering what this means, this is one of the few sites in the US with 207 MW of live energy that is fully approved by the large load interconnection process.
As a result, $NUAI is poised to sign a long term off-take agreement with a hyperscaler or Neo Cloud in very short order.
This 207MW was originally committed to $CIFR and then to a hyperscaler. Both failed and NUAI prevailed. That is a testament to the quality of this management team. In doing so, NUAI now has the upper hand to negotiate a hell of a deal in what is the hottest datacenter market in history.
And it doesn’t stop there. With another 550 MW of on-site generation capacity already contracted, NUAI’s TCDC site will quickly become a mega project that values the company at ~$5-7bn (or greater) vs yesterday’s ~$0.6bn market cap.
Good day to be an $NUAI shareholder. Congrats to all.

Phil DeSantis, CFA 🇺🇸 retweeted
$NUAI +29%
It’s been a rough and volatile wait, but we are in the final 4 weeks of this deal announcement with a Hyperscaler end tenant on TCDC. Would not want to be short here 🐼


$NUAI Thesis
I know you’ve probably been seeing $NUAI across your timeline recently, and was wondering what the deal with the company is. When I first saw this micro-cap stock on my timeline, I was extremely hesitant. But, after looking deeper I started to draw parallels to companies like $IREN and $APLD before the markets inevitably priced in what they could be worth. For those of you who have been in $IREN you understand that a 10x means speculating on an asset before its true value becomes obvious to the market, and seeing a vision for a company that plans to transition to something different. I believe $NUAI is the next 10x opportunity at $4.60, and here’s why.
Introduction
$NUAI’s flagship site is called TCDC, or Texas Critical Data Centers, that is 1.4GW Gross or ~1GW Critical IT load, in Ector County near Odessa, TX. I believe the market is completely missing the scale of what is happening at the TCDC site. If you haven’t been paying attention closely it’s easy for the recent announcements to fly under the radar. Since the beginning of this year $NUAI has put out announcements every couple weeks forging partnerships with energy generation partners, hiring significant industry leaders, and working meaningfully to prep their site for their hyperscaler client.
Following the Breadcrumbs
At the beginning of the year $NUAI closed the acquisition of the remaining 50% stake of TCDC from SharonAI, their original JV partner on the project. This was to have total control over the land to build new partnerships, and likely at the hyperscaler clients request to bring a new JV partner to the table.
In late February $NUAI announced a 450 MW Behind-the-Meter Generation Plan at TCDC with Thunderhead Energy and TURBINE-X Energy to generate power for the project. They have a SPV/venture where they have partnered with a private equity firm to fund the capital required to source, install, and run 450MW of gas turbines. They will generate an ROI as they sell power to NUAIs TCDC tenant. This equipment is normally extremely difficult to source, and $NUAI was able to grab these 2-3yr long lead time items in an extremely supply constrained environment, showing the connections of the upper management. The notable thing about this partnership is that they don’t have to put any capital upfront for this equipment, allowing them to start generating revenues while loaning the equipment without huge dilution (~70m).
Then, in mid-March $NUAI hired Ted Warner, ex head of the Energy, Power, and Digital Infrastructure at Northland Capital Markers, where he successfully structured and managed more than $7 billion in financing solutions specifically for large-scale data center developments. This was the signal that caught my eye and made me significantly up my position in the company. Something notable is his PSU’s, or Performance Stock Units, which reward him significantly for “Entering into a binding commercial agreement with a hyperscaler for a minimum of 200 megawatts”. Judging by his history I put him as an A+ hire, and you can see more about his notable achievements here.
xitter.cf/litigious_dulce/status…
Now, to get into the most recent developments that completely change this company from just a speculative random micro-cap to a more credible multibagger infrastructure play. On April 1st, $NUAI secured an LOI with Stream Data Centers. Originally, $NUAI was slated to co-develop the TCDC site with other partners (first Sharon AI, then Primary Digital Infrastructure). However after back and forth for months the unnamed hyperscaler tenant likely mandated that their own preferred execution partner handle the physical construction and operation. Stream is one of the top data center
This project with Stream will be done in a GP/LP fashion, where instead of issuing billions in new stock to pay for construction, the deal utilizes a heavily levered GP/LP (General Partner / Limited Partner) joint venture structure, operating at roughly 80% Loan-to-Cost (LTC). The roles exist as such:
The Originator ($NUAI): $NUAI acts as the local sponsor. They bought the TCDC 438-acre site, secured the initial power footprint, navigated local Texas politics, and laid the development groundwork. Originally I had thought that this agreement would mean passing up the GP role fully to steam and forfeiting their GP revenue streams as the originator. After contacting IR they said “we expect the final structure to reflect the contributions from each (NUAI as a project originator + local relationships, Stream as the developer)”
The Operator (Stream): Stream Data Centers steps in as the development manager and operator. They bring the engineering blueprints, the construction expertise, and the direct, trusted relationships with the hyperscaler. The hyperscaler obviously has a preference for this developer and has likely worked with them before.
The Institutional Capital (The LP): An unnamed institutional investor (99%+ confidence being Apollo, given their majority ownership of Stream) acts as the Limited Partner, writing the massive equity checks and leading the project financing. Apollo Global Management is consistently ranked among the top, most influential, and pre-eminent firms in private equity globally. It is commonly considered part of the "Big 4" of the PE industry and a mark of validation for this project that shouldn’t be looked past.
What this structure does is it protects $NUAI shareholders from the dilution that is so costly to shareholders in a company like $IREN, which long term (2-3 years) has potential to grow into a 100B+ market cap giant, but will need to dilute massive equity to get the cashflow flywheel going (as shown by 6B ATM). A 1.4 GW campus costs upwards of $12 Billion to build, and $NUAI cannot fund that on its own balance sheet. I expect this LOI to be facilitated into a binding agreement in the next 2-6 weeks.
The second piece of news that is the most convincing is the $290M credit facility from Macquarie. Just to put it out, in case it isn’t obvious already, Apollo and Macquarie don’t blindly gamble on some random micro-cap without doing extensive underwriting and due diligence on the parties involved. They deemed $NUAI worthy enough at a $250 million market cap to receive a $290 million multi-tranche facility that shifts the risk profile of the entire TCDC project.
The structure goes as follows: a $20M committed Term Loan A-1 to kick off development, followed by $30M and $40M tranches, with a massive $200M Delayed Draw Term Loan waiting for execution milestones. That’s already impressive in itself, and likely came from Ted Warner’s existing relationship with Macquarie, but an even stronger validation is the equity kicker. Macquarie took a direct $5 million equity stake at a 20% premium to market share price, taking their entry at exactly $5.00 per share. They also have a tranche of warrants that will have an exercise price of $5.00. The warrants will be issued across the first $50 million drawn on the Facility.
When one of the largest infrastructure lenders in the world is taking an equity stake at a 20% premium to the market’s price, it should tell you everything you need to know about the asymmetry of this setup. You have to ask yourself, would Macquarie offer a loan of this size to a random microcap without doing extensive due diligence and underwriting of an advanced hyperscaler LOI or term sheet?
Luckily, we got the answer to that hidden in the SEC filing of the Macquarie term loan agreement without a formal press release from $NUAI. $NUAI currently has an LOI in place with a hyperscaler tenant as of March 24th, 2026. I believe the reason it was not put in the form of a press release was at the hyperscalers request, and you can read more about it below from @kamikazzzi1981
xitter.cf/kamikazzzi1981/status/…
Now that all of the pieces of the puzzle are starting to come together that a hyperscaler deal is imminent, what should the company actually be worth?
Stock Price Projections
Firstly, I'd like to get out of the way that if you believe that $NUAI will secure a hyperscaler deal in the first place the announcement alone will probably put the stock around 2x higher than the current prices, or around $9-$10/share. This is by giving Stream, one of the most reputable data center builders hand selected by a hyperscaler, around a 60% chance of execution from the math below. If you want to, from that point, you can decide whether you want to sell, or if you believe they can execute the numbers start to get pretty wild.
From Phase 1 alone, with super conservative assumptions (more likely to be ~$1.50M EBITDA/MW)
Phase 1: 200 MW x $1.35M EBITDA/MW = $270M project EBITDA.
At 50% ownership, that is $135M to NUAI.
At a 14x-16x EBITDA multiple, that suggests $1.9B-$2.2B of value, or $14-$16/share on 135.5M fully diluted shares.
Northland’s analysis used a 19x EBITDA multiple in their analysis, 14x-16x is extremely conservative. At a 19x multiple you get a share price ~19$/share
If they can fully execute on Phase 1, the full TCDC 1.4GW campus can be modeled out as done by @ThePrudentWhale
xitter.cf/ThePrudentWhale/status…
• $34.51 Price Target in a 100% success case.
• $25.91 Probability-Weighted PT (applying a 25% execution risk haircut).
And here is super conservative bit of the model: this entirely excludes Behind-The-Meter power generation economics for phase 2+, GP stream revenues, 7 GW New Mexico development pipeline, and the reinvestment of cash flows into the futures phases of the projects for more equity.


Phil DeSantis, CFA 🇺🇸 retweeted

MOTION FOR PLAT HAS BEEN APPROVED FOR $nuai TODAY.
Signed PPA with Vistra should soon follow this. THEN SIGNED HYPERSCALER LEASE NEXT.
The question now is will the hyperscaler lease be for phase 1 or both phase 1+2? Either way this stock price about to take off. Rerate incoming.
Really good DD by @optionology and real time tracking today by @ChadWetWetz & @2b2c00 & @bitcoinbutcher1
Huge news on $NUAI! Their Texas Critical Data Centers project just landed on the city Planning & Zoning agenda for next Thursday: Preliminary plat of "New Era, Phase 1," 63 acres carved out of the 440 acre campus, city staff recommending approval. It just got more real than ever. Not if but when.
It comes with a site plan: A 400,000 square foot data center building. That's Phase 1. Parking, on-site recycled water, and a private road out to Loop 338. The lot sits directly across the parkway from the power plants. Very industrial area, with no neighborhoods.
Why this matters: before a tenant signs, the land has to be a real lot with a real building plan. This is that step, in public, with an engineering firm's stamp on it. Nobody spends this kind of money on a hypothetical tenant. The plat now, soon the PPA, all leading to even bigger announcements. Will be a huge win for the community. NFA. @KashRamki @litigious_dulce @awilkinson @bitcoinbutcher1 $NUAI
