Our Q3 2026 earnings report is now public → ir.spacex.com/files/content_…
The live webcast with @ElonMusk, @Gwynne_Shotwell, and @BretWJ will begin in 30 minutes

Watch live as SpaceX discusses our Q3 2026 earnings at 3:30pm CT today → xitter.cf/i/broadcasts/1PKqrNbLZ…
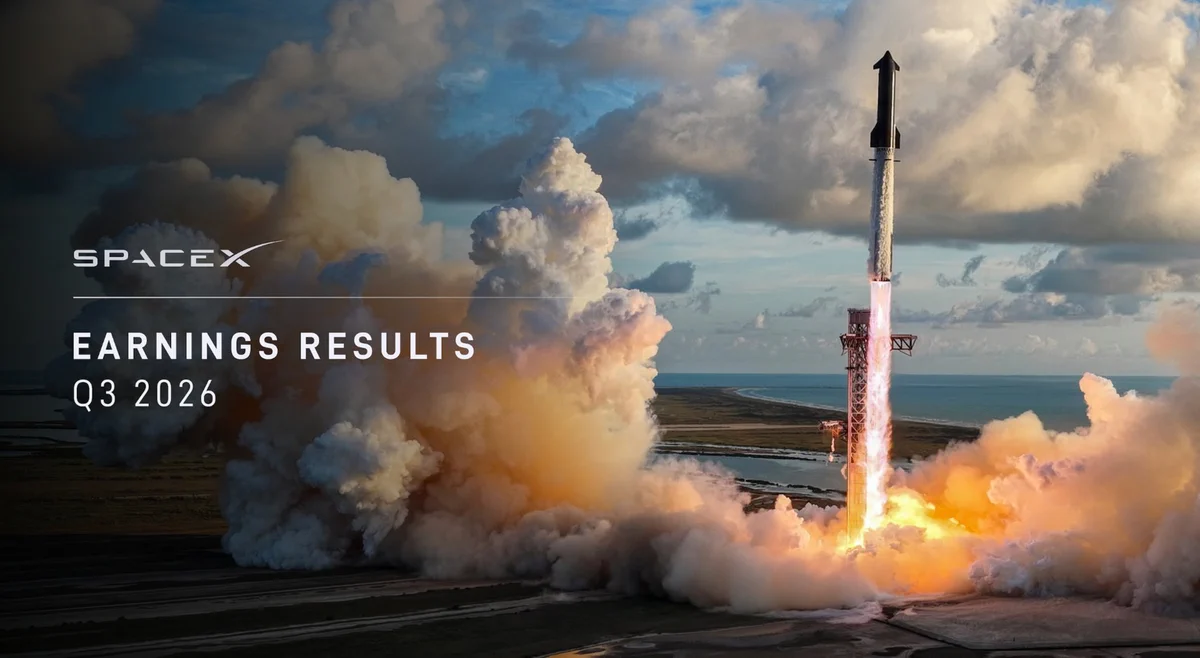
Q3 2026 highlights:
- Delivered revenue of $14.6 billion, up 161% year-over-year
- Successfully launched our first revenue-generating Starship mission, delivering 26 Starlink V3 satellites to our broadband constellation, representing approximately 10x the downlink capacity added by a Falcon 9 Starlink launch
- Added $6.7 billion of incremental Super Intelligence solutions and infrastructure revenue year-over-year, driven by cloud services agreements, the acquisition of Cursor, and our growing SI models and software applications, including @Grok @Bot
- Delivered year-over-year revenue growth of 69% and income from operations growth of 99% for the Connectivity segment, supported by strong momentum in enterprise and government adoption, and continued @Starlink consumer subscriber growth
- Continued to scale nameplate compute, reaching 1.7 GW as of September 30, 2026

Oct 20, 2026 · 8:13 PM UTC


$14.6b and up 161%? Huge result, and 13.6M Starlink subscribers is wild. Big effort from the whole crew, Aussies are cheering! 🚀🇦🇺





At a roughly $2tn valuation, SpaceX needs to prove this is a durable cash engine. Q3 net income was $4.4bn, but operating profit was $2.8bn. The difference includes $1bn of other income, with $561m from related parties, and a $390m tax benefit.
The AI unit made $431m in operating profit, against $5bn of adjusted EBITDA after stripping out $2.5bn of depreciation and $2bn of share based compensation. It spent $16.4bn on AI capex.
The customer risk is real too. SpaceX’s latest filing says one unnamed AI customer was 19.5% of revenue. It also says cloud contracts generally can be terminated by either side on 90 days’ notice after the capacity ramp. After nine months, SpaceX was still $413m in the red. That is a huge valuation resting on concentrated, cancellable AI revenue and a very long way to go before the investment turns into cash.

💰 Revenue: $14.6B, up 161% year over year
🛰️ First revenue-generating Starship mission: 26 Starlink V3 satellites, about 10x the downlink of a Falcon 9 Starlink launch
🧠 Super Intelligence and infrastructure: +$6.7B year over year
📡 Connectivity: 69% revenue growth, 99% operations income growth
🌍 Starlink: 13.6M consumer subscribers, 174 countries, 11.1K satellites in orbit
🚀 Launches: 113 year to date, 1,517 t to orbit
⚡ Compute: 1.7 GW nameplate as of September 30, 2026
Magnificent accomplishment to every team making it happen.
Source: @SpaceX Q3 2026 highlights


Hey @elonmusk – Fly Me To Mars 🚀
Got my ticket, got my seat.
Next stop: Mars.
#AlphonsoBellamonte

14.6 billion in one quarter. up 161% year over year
thats not a company thats a country with a launch pad. and now starship is flying revenue missions, 26 starlink v3 sats on the first one adding 10x downlink capacity
the $1T by 2028 math: 58B run rate needs a 17x. so basically they gotta colonize mars AND start charging rent
still the most bullish revenue chart in human history. what do you think they print in 2028


The quiet story is Connectivity: Enterprise & Government revenue +91% YoY to $2.13B, vs +57% for consumer. With one Starship flight adding ~10x a Falcon 9's downlink, capacity stops being the ceiling for that segment. Distribution becomes the game.