

Crypto Enthusiast • Web3 Guy • Defi • AI • RWA • Gamefi • Multichain Analysis • Marketing Strategist • NFA • Threador 🧵🦅
space
Joined November 2010
- Tweets24.3K
- Following2.6K
- Followers21.1K
- Likes39.1K




Happy birthday Reubs! ❤️ Wishing you and your family more wins this year. Big things ahead for Tenero and $STX!
The distinction between protocol revenue and tokenholder value is crucial. I’d add one more filter: how much revenue survives a full cycle after incentives, operating costs and dilution? That’s a better measure of resilience than peak fees alone.
spacebyte ⛓ retweeted

A crypto protocol can generate $100M in annual revenue and still be one of the worst tokens to hold through a bear market.
The numbers behind crypto’s revenue cycles are pretty brutal.
Across 227 protocols, median revenue contracted by more than 60% during major market downturns.
+ DEX-volume downturn: -62%
+ Bitcoin-market downturn: -65%
A protocol earning $10M monthly could see that fall toward $3.5M under comparable conditions.
Now imagine valuing that business using earnings from its strongest quarter. The multiple might look attractive, but the underlying revenue could be far less durable than it appears.
I think this is one of the biggest problems with how crypto fundamentals are evaluated.
Over the past 30 days, protocols generated approximately $1.22B in revenue.
+ @tether : $506M
+ @circle : $203M
+ Combined contribution: ~58%
Two stablecoin issuers accounted for more than half of tracked revenue.
Their economics are quite different from those of DEXs, derivatives exchanges and launchpads, where earnings depend heavily on trading activity and leverage.
Stablecoin issuers earn primarily from reserve assets and outstanding balances. Lending protocols depend on borrowing demand, utilization and interest rates.
These businesses can all experience revenue declines, but they don’t necessarily contract for the same reasons or at the same pace.
And there’s another complication.
A protocol generating more revenue doesn’t automatically have better token economics.
Consider two hypothetical businesses:
+ Protocol A: $50M annual revenue, with $40M allocated to token buybacks.
+ Protocol B: $100M annual revenue, with no direct tokenholder distribution.
Now assume A’s revenue falls 25% during a downturn while B’s declines 70%.
A would still generate $37.5M annually. B would fall to $30M.
The smaller business would now earn more through the downturn, while maintaining a clearer mechanism for returning economic value to its token.
That doesn’t guarantee A’s token will outperform. Entry valuation, dilution and buyback execution still influence returns.
But it shows why revenue size alone tells us very little about the quality of a token investment.
A derivatives exchange reporting record fees during a leverage-driven rally could be an excellent business. The question is how much of that revenue remains when leverage disappears and trading activity contracts.
The same applies to launchpads and protocols that rely heavily on incentives to attract users.
Personally, I’d rather evaluate a business generating $30M consistently across market conditions than one earning $100M at the peak and $10M when activity dries up, assuming comparable valuations and tokenholder economics.
Because a high-revenue protocol isn’t necessarily a durable business, and a durable business isn’t automatically a good token investment.
The strongest fundamental opportunities may come from protocols that can preserve earnings through downturns and convert those earnings into tangible value for tokenholders.

That revenue gap shows how much Pumpfun has turned token launches into a full trading funnel. The challenge now is keeping traders active when new launches stop attracting the same attention.
Pendle’s opportunity is making tokenized assets useful beyond simply holding them. Tradable yield gives onchain capital more ways to generate value.
spacebyte ⛓ retweeted

One of my stronger convictions in RWA-Fi is that @pendle_fi is positioning itself at the forefront of the next wave of onchain capital markets.
We're talking about trillions $$$ in potential tokenised asset supply over the coming years, but bringing assets onchain is only half the equation.
The real opportunity lies in unlocking their productivity once they're there.
Its obvious that Pendle is increasingly becoming a fundamental layer for that.
A few developments worth highlighting:
1. From yield tokenisation to broader asset productivity
PTs have already established themselves as a core DeFi primitive for fixed-yield exposure + capital-efficient looping strategies.
With PendleLoop, that utility is expanding beyond traditional yield-bearing assets into leveraged exposure across BTC, ETH + tokenised equities.
Tokenised stock long strategies on @base now integrate borrowing through @aave, (up to ~4.2x leverage) enabling users to trade yield expectations towards helping them deploy capital more efficiently across different asset classes.
2. Becoming a value discovery layer for RWAs
From tokenised treasuries + private credit to AI infrastructure, reinsurance + equities, Pendle has reportedly listed 100+ RWA markets YTD.
*FYI: RWAs now account for >80% of its TVL.
What stands out is the breadth of exposure being brought into DeFi.
As more institutional assets come onchain, Pendle provides a venue where their yields can be priced, traded + incorporated into broader DeFi strategies.
Tokenisation creates asset availability, yield markets help turn that availability into financial utility.
3. Institutional credibility as a compounding advantage
The growing roster of asset managers is particularly notable:
🔸 Janus Henderson (deJAAA)
🔸 Franklin Templeton (FLHYon)
🔸 Partners Group (NGI+)
🔸 Bitwise (PPLUS)
Alongside its RWA Insights series featuring institutions such as Grayscale, Pendle is building relationships with some of the most established names entering tokenised finance.
This matters wayy beyond the immediate TVL contribution.
Institutional relationships bring credibility + differentiated asset supply, which can attract more liquidity, improve market depth + strengthen Pendle's position as a destination for future RWA listings.
And that's where the reinforcing flywheel gets interesting.
More institutional assets → broader yield markets → deeper liquidity + capital utility → greater incentive for new issuers to participate.
Ofc, the flywheel depends on actual market demand + sustainable liquidity, not simply the number of listings.
But the direction is pretty clear.
As tokenised assets proliferate, the opportunity increasingly shifts from who can bring assets onchain to who can make those assets productive.
Pendle is building a pretty compelling position at that intersection.
A 24/7 yield discovery layer for an increasingly onchain financial system.
Best part of this? We're still vv early in this transition.
Pendle 🫡

Same gold, different prices.
On October 27, @Tether’s XAUT traded at a 0.16% discount to spot gold, while @Paxos’ PAXG traded at a 0.05% premium.
That’s a 0.21 percentage-point gap between two tokens backed by the same commodity.
Their market values also differ considerably:
→ XAUT: $2.97B
→ PAXG: $1.77B
PAXG offers monthly reserve attestations and direct redemption fees starting at 0.125%. XAUT provides quarterly attestations and charges 0.25% for direct redemption.
But for retail holders who aren’t redeeming physical bullion, execution price and secondary-market liquidity could outweigh those differences.
XAUT has the larger market presence, while PAXG offers more frequent reserve reporting.
At what price difference would you actually choose one over the other?

I’d watch whether XAUT supply holds steady through further downside. Low redemptions suggest holders aren’t rushing out, but concentrated minting could reflect a few large buyers rather than broad demand.
The multipliers could influence where traders route orders. The real question is whether the extra points outweigh the fees and execution costs of switching venues.
Crypto doesn’t need another blockchain. It needs protocols that put existing infrastructure to work.
That’s the idea behind @Oly_Dao.
OLY combines ETH staking through Lido, Uniswap liquidity fees and trading-tax revenue to build around real DeFi activity.
Now, it’s expanding its role on Robinhood Chain, where $OLY already trades against tokenized NVIDIA and Tesla stocks, alongside BTC and ETH.
These markets need liquidity to function well. OLY wants to become one of the chain’s largest liquidity providers.
But the next chapter raises another question: why is a DeFi protocol creating the Bank of OLY with just 1,000 NFT Charters?
That’s the part I’m curious to learn more about.
🤝 Paid partnership

The key distinction is whether rewards come from sustainable external revenue or depend on trading taxes generated within the same ecosystem. For Oly, I’d track how much each source contributes and whether liquidity provision remains profitable when trading activity cools.
spacebyte ⛓ retweeted
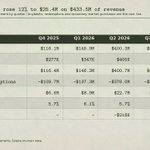
.@Raydium’s revenue more than tripled in Q3, but memecoins are no longer its biggest source of swap fees.
According to Blockworks Research, Raydium generated $8M in net revenue during Q3 2026, with tokenized assets becoming its largest source of swap fees.
The numbers:
+ Q3 net revenue: $8M
+ Revenue growth: More than 3x
+ Annualized net revenue: $32M
+ Largest swap fee category: Tokenized assets
For a DEX historically tied to Solana’s speculative trading cycles, the changing revenue mix is arguably more important than the growth itself.
Consider $1B in trading volume.
+ At 5 bps: $500K in gross swap fees
+ At 20 bps: $2M in gross swap fees
That’s four times the fee generation without any increase in volume.
Of course, gross swap fees aren’t Raydium’s net revenue. LP allocations and protocol take rates determine how much the business retains.
But this illustrates how a different trading mix can improve fee generation without requiring equivalent growth in volume.
Tokenized assets also introduce different liquidity requirements, market-making costs and trading behavior, so their long-term profitability remains unproven.
Still, Raydium is developing another meaningful revenue source beyond memecoin trading.
If that continues across market cycles, it could change how investors assess Raydium’s business and the economics behind $RAY.

The fee mix shift is the bigger signal here. If tokenized assets can sustain higher-value trading beyond speculative cycles, Raydium could build a steadier revenue base, but repeat volume and LP profitability will determine whether that growth lasts.
Private companies now have trillion-dollar valuations trading on crypto exchanges, even before their shares become publicly available.
Anthropic’s IPO filing has brought these markets back into focus, and October 27 data shows how differently exchanges are pricing exposure to Anthropic and OpenAI.
Anthropic’s last reported funding valuation was $965B. Its perpetual markets are now implying almost twice that amount.
→ @extendedapp : $1.877T (+94.5%)
→ @variational_io : $1.877T (+94.5%)
→ @binance : $1.880T (+94.8%)
→ @bitget : $1.882T (+95.0%)
→ @Lighter_xyz : $1.934T (+100.5%)
OpenAI shows a similar pattern against its last reported $852B valuation.
→ Extended: $1.410T (+65.5%)
→ Variational: $1.411T (+65.6%)
→ Binance: $1.413T (+65.8%)
→ Bitget: $1.438T (+68.7%)
→ Lighter: $1.501T (+76.1%)
What’s striking is how much the prices differ between exchanges.
Anthropic’s implied valuation varies by approximately $58B across these venues. For OpenAI, the difference reaches $90B.
And liquidity tells another part of the story.
Binance has around $50M in open interest on its Anthropic contract, compared with $2.4M on Lighter and just $24K on Extended.
So one of the lowest quoted valuations comes from a market with very little outstanding exposure.
These contracts aren’t private shares. They’re derivatives whose prices depend on liquidity, funding rates, margin requirements and settlement terms.
Without a publicly traded underlying share price to anchor arbitrage, large pricing differences can persist.
Pre-IPO perps are bringing continuous price discovery to private companies, but a quoted valuation is only as meaningful as the liquidity and settlement mechanics behind it.

Tokenized equities need more than an onchain ticker. They need assets people can actually use.
@Swisscheese_fn is building on Polygon, combining tokenized stocks with swaps, staking and borrowing. Its security measures include smart contract audits, cold storage, encrypted data and 2FA.
Reliable pricing, liquidity and compliance will determine how far this model can go.
With $SWCH listed on MEXC and Gate.io, SwissCheese is building its presence in the wider crypto market.
The goal is to make stocks functional assets within DeFi, not just put them onchain.

The separation between raw footage and the finished 3D model is important for privacy, but coverage quality will determine whether buyers can actually use the output. How does Vangrid handle disputed captures when a requester rejects a reconstruction that meets the submission requirements?
Funding can quietly turn a profitable trade into a mediocre one over time. Yield-bearing margin helps address the idle-capital problem, but the real comparison is net return after funding, borrowing costs and liquidation risk.