

Page : Fun Manager จาก Facebook แอบมาเปิดสาขาเพิ่มใน X เพราะในนี้มีสิ่งดีๆเยอะ
Joined May 2023
- Tweets3.7K
- Following1.1K
- Followers6K
- Likes3.7K





Fun Manager retweeted

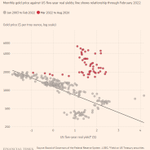
A lot has changed in 7 weeks - the only thing that hasn't changed (yet) is the $DXY.

Fun Manager retweeted

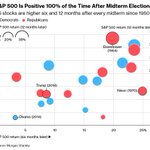
Implied volatility markets are not pricing midterm results to be a big event.
The forward volatility market is implying just a ~1.2% move in the S&P 500 Index tomorrow. That’s below what was implied one day ahead of 3 of the last 4 midterm elections. And it’s below what the S&P 500 realized after the 2018 and 2022 elections.

Fun Manager retweeted

GS: Consensus capex estimates on AI/Cloud players... should grow to ~$1.74 trillion by 2030 at a 31% 2025-2030 CAGR

Fun Manager retweeted

Opportunities in fixed income | UBS
_/ Opportunities include adding medium- and long-duration IG bonds, diversifying thru EM credit and high-yield debt & focusing on current yields. Caution is advised on longest bonds due to fiscal and #AI debt concerns.
smallpdf.com/file#s=5c9f44d3…

Fun Manager retweeted

🚨 AI INFRASTRUCTURE BOOM JUST GOT BIGGER.
GS has raised its 2030 global data center capacity forecast from 217 GW to 273 GW a massive 26% upgrade.
That's an estimated $8.5 TRILLION in infrastructure spending over five years.
And here's the real story: AI demand isn't slowing down. The race for power, GPUs, and data center capacity is accelerating.
The biggest AI investment cycle may still be ahead of us. 🧵👇

Fun Manager retweeted
GS: A Statistically Significant Relationship Between AI Adoption and Job Growth and Unemployment Among Nonmanufacturing Subsectors

Fun Manager retweeted
The S&P 500 P/E ratio is now right near its April 2025 low... 18.3x... down almost 5 turns from 12 months.
A valuation bear market. @dualityresearch

Fun Manager retweeted

The market is so negative on AI capex spend that hyperscalers with an average 21% revenue growth are trading at a 20.7x P/E multiple.
Meanwhile, you have companies like Costco and Walmart trading at 40x P/E while growing revenue at a fraction of the rate
If the capex proves to have any reasonable ROI, people are going to deeply regret being this bearish on some of the best companies in the world

Fun Manager retweeted

คุณโฟร์ทสรุปครบ

3 Supercycle พลิกประวัติศาสตร์
โลกไม่ได้แค่เจอ “แรงกระเพื่อม” ธรรมดา แต่เรากำลังเข้าสู่ 3 Supercycle ลูกใหญ่ที่จะพลิกประวัติศาสตร์เศรษฐกิจโลก!
#เศรษฐกิจโลก #Supercycle #นฤมลจิวังกูร #Citibank #NATIONFORUM2027


Fun Manager retweeted

ว่าแล้วคุ้นๆเป็นคนเดียวกับที่พูดว่า " ถ้าในวันที่ทุกสิ่งดูผิดพลาดไปหมด ใจที่ดีจะนำทุกสิ่งกลับเข้าที่เอง " เพราะแกไม่ยอมแพ้ทำมันทุกอาชีพที่ได้เงินแล้วแกก็สู้จากสาวโรงงานจนได้เป็นผู้พิพากษาเลย ไปฟังสัมแกโคตรอิมแพค

Fun Manager retweeted

How are economies navigating the balance between global trade and long-term sustainability? 🌍
Our partner, @hinrichfdn, has released the 2026 Sustainable Trade Index, examining economic, societal, and environmental dimensions of sustainable trade across 30 economies.
Explore and download the full 2026 report: hinrichfoundation.com/resear…


Fun Manager retweeted

Investor appetite for leverage is through the roof:
10 largest US leveraged equity ETFs have attracted +$12 billion in inflows over the last month.
This is despite the market cap of these funds falling -$20 billion over the same period.
Recent inflow growth has been led by the 3x leveraged long Semiconductor ETF, $SOXL, which attracted +$9 billion over the last 2 weeks, its largest 2-week inflow on record.
The 3x leveraged long Nasdaq 100 ETF, $TQQQ, posted +$1.3 billion in inflows, its 2nd-largest 2-week intake of 2026.
Over the last 5 months, the 10 largest US leveraged equity ETFs have attracted +$19 billion in inflows.
Investors are piling into leveraged ETFs at a record pace.

Fun Manager retweeted

The picture is of a market with an increasingly powerful mechanical bid underneath it. Something that does not evaluate, that does not read a rally as useful information at all, and that shows up on declines with a size and a speed that has no precedent

Fun Manager retweeted

Nomura Report on Global Memory- 10.19.2026
Nomura's central thesis: The market is overestimating risks surrounding AI financing, slowing AI revenue growth and Chinese memory competition, while underestimating the earnings and cash-generation opportunity of memory manufacturers.
They expect memory supply constraints to persist through at least 2028, supporting an extended period of favorable pricing and profitability.
→ AI infrastructure demand is accelerating.
Nomura forecasts:
- AI data center capacity grows from 34 GW in 2026 to 74 GW in 2028 — approximately 118% expansion in two years.
- AI's share of facility capacity increases from 54% to 76%.
- Total global data center power usage rises from 60 GW in 2025 to 115 GW in 2028.
- Heavy-agent workloads become an increasingly important source of AI power demand.
Nomura considers market concerns surrounding CXMT's progress in 4F² DRAM technology excessive.
Its position:
- CXMT's technological progress does not invalidate the broader supply-constrained memory thesis.
- The breadth of AI demand is being underestimated.
- Global memory supply constraints should persist through at least 2028.
This is particularly relevant to the scarcity thesis for Micron and SK hynix.
They make stock recommendations for Samsung and SK Hynix
🔽 🔽 🔽
Outer Ninth's 3 most important takeaways:
1. The memory scarcity thesis remains intact.
Nomura's expectation of tightness through at least 2028 supports the possibility of an extended earnings cycle, rather than a short-lived pricing spike. This is constructive for Micron, SK hynix and broader memory exposure and inline with our views.
2. The separation between infrastructure spending and economic capture is becoming increasingly important.
The difference between semiconductor suppliers' cash accumulation and data center operators' indebtedness reinforces one of our core research principles: Participation in AI growth does not necessarily translate into equal financial returns.
I've been speaking to you guys more about this recently and I research it thoroughly- debt structure and capital return to shareholders will matter more heading into 2027.
Companies that control scarce, essential components may capture a disproportionate share of the economics.
3. For our memory ecosystem, the most important insight is the potential for an extended period of scarcity-driven earnings growth and economic capture by upstream semiconductor suppliers.
Companies highlighted on our latest memory ecosystem research w/c I reposted this evening:
SK Hynix 하이닉스 000660.KW | $SKHY
Samsung 삼성 005930.KW
Micron $MU
Sandisk $SNDK
ESMT 晶豪科 3006.TW
Nanya 南亞科 2408.TW
Kioxia キオクシア 285A.JP | $KXIAY
Winbond 華邦電 2344.TW
Phison 群聯 8299.TW
AP Memory 愛普 6531.TW
Etron 鈺創 5351.TW
Seagate $STX
Penguin Solutions $PENG
Western Digital $WDC
Transcend 創見 2451.TW
PSMC 力積電 (6770)
ETFs- $DRAM & $DISK


Fun Manager retweeted

The dot com bubble didn’t end in an across the board bust … it ended with rotation
Wrote about this here 👇
nitter.gq/sonusvarghese/status/2…


Fun Manager retweeted

AI Beneficiaries:
Investing in Second-Order Effects
I just read this great piece from Counterpoint Global, which puts out some amazing free research.
Highly recommend giving it a read. It’s light, easy to follow, and well worth your time. morganstanley.com/content/da…


Fun Manager retweeted
JPMAM sees US large caps and ex-US stocks returning 7.5% annually over the next 10-15 years

Fun Manager retweeted

Ken Griffin, who runs Citadel, just admitted that the biggest advantage of giant funds, armies of people and billion-dollar budgets, is disappearing
And for the first time in history, a small team with AI can move faster than a hedge fund
He’s seen it in his own firm. His AI agent does in 2-3 hours what used to take Citadel’s PhD researchers 6-8 weeks
A fund runs one cycle: come up with a strategy, turn it into code, test it on history, deploy it to the market
Every step used to cost separate people and years of training. Now AI does the whole cycle
You describe an idea in words, it writes the strategy itself, runs it on years of real data, and if it’s alive, deploys it straight to a broker
But the speed isn’t the point. The point is what the retail trader doesn’t understand
You take a strategy with a beautiful chart and you believe it. But a beautiful chart is no proof
Run enough versions and a profitable curve will appear even on random numbers. One just got lucky, and you decided you found gold
Funds don’t trust any curve until they test it on data the strategy has never seen. There the fit falls apart, and a real edge survives
I ran two of the most-cited quant papers through this cycle
Time Series Momentum on Bitcoin: +1,537%. Alive
Betting Against Beta, a classic from every textbook: minus 7.78% a year while the market rose 14.86%. A corpse
One still prints money, the other died long ago. And trading blind, you’d never know which is which until it took your deposit
Griffin says the future belongs to small teams with AI. But the only ones who win are the ones who test before they bet
How to plug your AI into real market data so it runs this exact test instead of guessing, in the article below

