
Engineer by profession. Trading a bit on the side. Just here for FinTwit
Austin, TX
Joined March 2024
- Tweets1.3K
- Following1K
- Followers169
- Likes16.7K






Yes, of note earnings are very cyclical and consequently we have a bubble in earnings: such high earnings per share will not likely be sustained in the long term.

Only looking at S&P 500 P/E ratios is incomplete; Look at literally ANY other valuation metric:
📈 Price/Sales: 3.10 (Still very high)
📈 Price/Book: Extremely elevated
📈 Price/Cash Flow & FCF: Near historic highs
📉 Dividend Yield: Historically low
Almost every alternative valuation measure is sitting in the 90th+ percentile. The market isn't cheap just because earnings multiples look okay. 🍒

10
Cal Petersen retweeted

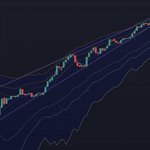
Let's be clear what this S&P chart is showing us:
1. This selloff is just starting. Can we bounce Monday or Tuesday? Sure. But that big red candle. Last week's...it's a big one. Big red candles are usually followed by more big red candles.
2. That was a 6+ year channel. Now, we are back in it. Technically, we treat these like any other false breakout. If you think about a previous range, then a false breakout of previous range, we treat this is the same. If I had to throw a probability on it, I would say (over time....let's say in the months ahead) there is a 70+% chance of us breaking UNDER the previous channel now. False breakouts tend to lead to breakdowns.
3. We will have bounces, and they will be violent. When they occur, they tend to be very convincing. Most "bear market rallies" are. But we will be in sell rally mode for awhile, unfortunately.
Volatility will be high. Position sizes should be smaller to weather the bigger swings. Trade carefully out there.
That is all.

Cal Petersen retweeted

Hormuz tanker traffic hit wartime highs in October. Non-Iranian tanker transits reached 418 in October, up from 385 in September. China's Gulf crude imports neared pre-conflict levels.
And then November happened- Hormuz flows collapsed again following non stop attacks on ships.

Cal Petersen retweeted

Odd choice by the board too because she will be spending a lot of time w the attorneys, no real time to be CEO. She will have to be terminated too, along with the others involved in both the Megaspeed related stuff, as well as the financial/disclosure related issues. She was the one communicating all the misleading stuff re sales to Asia/China as well, and she was CFO when they changed their geographical rev recognition re this issue. There are going to be so many more shoes to drop on this thing it is not even funny.
SELL is not a four letter word.
$NVDA

Cal Petersen retweeted

The number of stocks with DeMark Sequential sell Countdown 13s developing within $SPX is among the highest I've seen since the beginning of the year. More on the next Hedge Fund Telemetry note
Ie credit spreads are starting to confirm the recent downturn

On November 3, CCC spreads were 3.64 times B spreads, up from 2.71 times a year earlier and in the 94th percentile of the window. CCC trailed BB by 5.3 points in total return over 3 months, and the CCC-B gap was 954bps. The stress sits at the bottom of the ratings ladder.

1
31

Cal Petersen retweeted

Ryan is a beloved perma-bull.
Keith is a chest-pounding bully to get clicks (& conversions) by putting Ryan down to make himself feel better/bigger.
Keith disgusts me - always has.
Ryan challenges me - always has.
Hopefully this exchange reminds you: character matters. 🎩Ryan


Cal Petersen retweeted

Now that we saw the market drop 4% in a day with a few pod shop liquidations, we can now circle back to the point I was making in this post, the majority of the street was NOT betting lower, it was and still is the complete opposite!
All the horrible sell side data in the weeks prior were talking about how hedge fund exposures were “LOW” and how short based bets were super high lol.
Dive into the thread. It should serve as a good learning lesson.

Everyone who keeps sharing these short interest charts is missing the flows behind them. Most shops are not taking outright short bets. This is another effort to ease margin requirements across the street: banks providing balance sheet for more speculative bets are asking clients to post more short exposure.
The sequence on the street looks like this:
HF manager: “I want more margin.”
Bank: “Things look risky in public AI bets, and we’re already lending a lot against private AI bets. For some clients, we’ll extend more financing, but only if they add more short exposure to improve their collateral scores.”
HF manager: “Okay, I’ll short more stock against my main bet.”
That is how you end up with short exposures that look astronomically high while many end users remain heavily long tech. The additional shorts are supporting the financing of their main bets.
Which also tells the bigger story on why raw equity financing rates haven’t blown out the way they did ahead of the big SpaceX IPO in June, despite the fact that lending is slowing.

Cal Petersen retweeted

The 5% Canary
It took 22 days for the S&P 500 to cross the 5% drawdown level. As discussed in my paper, The 5% Canary, this exceeds the 15-day threshold that's commonly associated with larger protracted declines.
This alone doesn't mean the market can't suffer further losses, the 2007 peak for instances took 21 days to decline 5% from its high for example while '18 took 15, '22 took 11 and '25 took 9. In the paper I show that when it takes a protracted period of time to lose the initial 5%, selling pressure is often too thin for continuation.


Cal Petersen retweeted
Quick mini thread on tail risk hedging thanks to my man, @Fink_Money
Tail hedging is a pretty complex topic and there are 10 more reasons why it can be challenging for a smaller investor to implement. But two of the biggest limitations from an infrastructure perspective is understanding what exactly to buy and how much to pay. Trying to execute on those two simple concepts have further nodes that have its own challenges.
Ultimately, you’re trying to answer two questions. Which tails do you want to own, and at what price does owning them make economic sense?
A static hedge can struggle even if you’re right about the crash. Say you only buy one-month, deep OTM puts, and the market takes six months to grind lower, with sharp rallies along the way. You can be right about where spot ends up and still watch one set of puts after another expire worthless. That’s why I don’t put much faith in one-trick-pony hedges. You need infra to guide you on a core understanding of which tenors and strikes are likely to reprice based on positioning and how well those options carry as spot moves along the skew curve.
Execution matters just as much. Say a tail option is quoted $0.02 bid at $0.10. It’s easy to look at the offer and think, “It’s a dime. How expensive can it be?” Suppose you pay $0.10, spot sells off, vol rises, and the option reprices to $1.00. Your position is worth 10× what you paid, a 900% gain. If you can work the order at $0.05, that same move takes you to 20× what you paid, a 1,900% gain. Getting filled at a nickel lets you own twice as many contracts. That’s where you double your convexity. You own twice the exposure going into the crash because of the infra you have to post liquidity and find a real inside market before spot or vol moved at all.
That’s the part I think is hard for a retail investor or a smaller shop to replicate. Even if you identify the right tails, you still need the infrastructure and execution logic to work orders at scale across names, tenors, and deltas, all at prices that make the hedge worth owning.
Start adding in how to offset the bleed in a real uncorrelated fashion along with a real alpha focused monetization framework and you have tons of other considerations to make when executing something like this.

Cal Petersen retweeted

Drawdowns:
$SNDK -64.5%
$ARM -63.0%
$INTC -62.2%
$MRVL -58.4%
$KLAC -58.4%
$LRCX -56.7%
$AMAT -56.1%
$ORCL -54.4%
$CAT -48.1%
$MU -46.3%
$DELL -45.8%
$SPCX -44.8%
$NFLX -44.5%
$BABA -40.5%
$AVGO -40.3%
$AMD -37.2%
$SKHY -36.4%
$GEV -36.2%
$TSLA -31.5%
$ASML -31.2%
$GOOGL -30.4%

Cal Petersen retweeted

I can’t shake the feeling that selling your high-beta tech stocks already down 40-70%, to buy low/no growth consumer names at 30-100x earnings…might not be so smart, either.
Cal Petersen retweeted

Generational washout in momentum
The mtum/usmv ratio has now retraced all the way back to the March 30 lows, effectively unwinding the entire April dispersion/gamma-driven momentum surge. What was one of the most crowded trades on the way up has now been fully washed out on the way down.


Cal Petersen retweeted

BIG: The New York Times reports the US military is preparing for a possible strike on Iran.
It could come as early as tomorrow, right after the midterms.
clashreport.com/defense/arti…

Cal Petersen retweeted
ICYMI - Here's todays Tasty Crumbs on @tastyliveshow
🐻⬇️
youtube.com/watch?v=IpOYPk0q…
