

Evidence-based financial education and fun stats. Part research, part ramblings. Tweets ≠ advice. YouTube vids at https://nitter.gq/t.co/Q5xmqlofr3
USA
Joined September 2020
- Tweets10.4K
- Following70
- Followers3.3K
- Likes9.5K
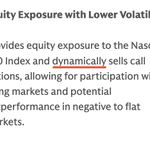




Fun fact on GPIQ and GPIX, covered call ETFs from Goldman:
The permitted range of option overwrite is 25-75%, but nowhere in any of the fund literature does it say what informs that percentage.
I thought they might mention the usual terms like market sentiment, directionality, or implied vol (all of which would still be vague). Nope. Nothing.
So these are more discretionarily active than I initially thought. That word "dynamically" could mean anything here.
So far, the average has been about 35%.
Read more at:
optimizedportfolio.com/gpix/

ALT Source: Goldman Sachs. GPIX product page.
Honestly, Google can probably do a better job than me, but I'll try.
A put option or a "put" is a financial contract that gives the buyer the right to sell a certain asset at a certain price ("strike") before the contract expires.
A buyer pays for it. A seller collects that fee.
In the context here for OVQ, a "short put spread" is the strategy of selling a put option at a higher strike and buying a put option at a lower strike.
QQQI has some objective design improvements for the long haul IMHO like tax treatment and upside recapture, but for an extended sideways or bear market, JEPQ will probably slightly edge it out, at least pre-tax. In the interest of full disclosure though, I'd take neither.
Planning to finance or pay cash in full? If the former, you might like this idea: youtu.be/oij8c-szRAg
And you would have needed even less, at least for the period since SPYI's inception, with a pretty naive mix of simple low cost index funds in the form of 80/20 VOO/SGOV, and conveniently with lower risk.
Raising this purely to illustrate the sheer silliness - IMHO, at least - of this type of "here's the distribution payout on various funds" posts.
It does depend on the fund, just not in the "income = yield" way these posts frame it as. nitter.gq/OptimizedPort/status/2…


I maintain that one can typically extract any given requisite income more efficiently than a covered call "income" fund, even after taxes, from a simple, diversified mix of traditional low cost index funds.
Long tweet ahead. Strap in.
What do I mean by “more efficiently?” The same income with lower risk or more income at the same risk. Conveniently, we typically see both - more income and lower risk.
There will, of course, be some specific short periods of choppy sideways markets when assets converge where I'm wrong on this but I think on average, for any reasonably long horizon, I won't be (even with the newer, fancier iterations of these products). We care about how the portfolio delivers income across the whole decumulation period, not over a snapshot of a month or 2.
(Let’s also go ahead and get this out of the way - no one is suggesting you just buy the underlying index and come out ahead. That’s not the argument. I’m talking about using a diversified portfolio for current income today. So please don’t come at me with that accusation.)
I've attached a few examples of this concept using older funds with at least a little bit of history.
I've described these older products like PBP and XYLD as comparatively more "blunt" - full overwrite coverage and ATM options - compared to newer iterations like SPYI and GPIX that are more nuanced and active, don't write on the whole equity book, and use OTM options.
Proponents of covered call "Income" funds reflexively say these older ones are the "worst" examples to use and that I'm being unfair and idiotic in doing so. I do so purely to get a longer observable time period for more robust data, i.e. more observations, which is Stats 101. I'm happy to run the numbers with the newer products too, and I've done that, but most of them are only a few years old at most and haven't even seen the environment in which they'd shine. I make sure to explicitly point this out in all my articles on these funds.
The trap the influencers and novices continually fall into is thinking the implementation and management of any given covered call product is what makes or breaks it. It's not. It's the fundamental inefficiency and asymmetry of the covered call trade itself. They think the next iteration of a flashy high-yield covered call product will finally be the holy grail to break the curse and solve the issues. It won't. Ironically, the only way to do so is to remove the covered call trade entirely.
I mentioned this in my first blog post on this topic years ago. First QYLD and XYLD from Global X were the new hot thing among yield chasers. Then they moved on to JEPQ and JEPI from JPMorgan, and QYLD and XYLD were viewed with disdain. Now it's ostensibly GPIQ/GPIX from Goldman and QQQI/SPYI from NEOS, which Goldman is acquiring. Now anyone who even mentions JEPQ or JEPI is labeled a moron.
But NEOS and Goldman can’t change option math. Meet the new boss, same as the old boss.
These products satisfy a psychological desire to avoid liquidating shares. Totally understandable. But appreciate that they are not magically dismissing sequence risk, improving realized Safe Withdrawal Rate, or allowing for earlier retirement. Your favorite finfluencer is probably claiming it’ll do all 3. The marketing materials of these products even sometimes hint at such fanciful abilities.
(Previously, it was admittedly arguably logistically harder to liquidate shares too. Fair. But nowadays, the broker can auto-sell for me and transfer cash to my bank account monthly without me logging in or lifting a finger. Same outcome.)
Those same people will say this is a new wave of retirement products that opens new doors (“this time is different”) and that I’m just not up to date on the recent research. I think this is pretty silly fundamentally even if only for the fact that markets are still markets. But the irony is we’ve had boatloads of research on this type of product because it’s existed for decades, long before NEOS tacked on some tinsel like 1256 treatment and a long call leg. Those are probably improvements, no doubt, but they don’t move the needle on the elephant in the room I mentioned earlier - the CC trade itself. The “research” they’re citing is marketing literature from the fund provider, who probably pays the influencer anyway.
The CC trade necessarily caps upside and doesn’t adequately mitigate the downside proportionately. This is what we mean by “inefficiency” and “asymmetry.” Lower volatility of these products is just less market exposure. You can do that by …owning less of the market.
In point of fact, the behavior of the fund often doesn’t look dissimilar from just holding the underlying + cash, which I’ve shown here, and which many smarter than me have also shown. Appreciate the hilarious irony that despite what content creators in this space will tell you, a naive 90/10 underlying/cash allocation often beats the flashy, complex, expensive “income” product by virtually any measure.
To add insult to injury, these products always carry pretty hefty fees, comparatively, which almost always easily cancel out any purported tax benefit from ROC, which I’ve also shown: optimizedportfolio.com/roc-c…
I sympathize with the novice investors because I believe they want to believe the empty promises. But these products often don't even pass the sniff test. If it sounds too good to be true, it probably is. If a YouTuber is talking about retiring early on 12% yield with only $300k when the conventional rules of thumb fly in the face of that assertion, your spidey sense should at least be tingling and you owe it to your future financial well-being to at least do more research.
As an aside, sequence risk is a big factor here that every single finfluencer I've seen hawking these products loves to ignore completely: optimizedportfolio.com/seque…
It’s neither obvious nor intuitive that the high distribution rates like 12% are not really returns. Ben appropriately calls it an “illusion.” That’s how you can end up with a fund like QYLD with a distribution rate of 12% and a long term total return of only 9%. The return can be less than the distribution rate. Many don't realize this. In short, these funds often end up having to distribute from their own capital base, because the prospectus says they have to distribute but it doesn't say they must earn more than they distribute.
Don’t get caught up in the mental accounting of viewing yield and price return separately. As always, total return is all that matters at the end of the day. That’s what’s paying your bills.
To keep numbers nice and round, I used $100k starting and $1k/mo. income (12% distribution rate) for all these.
In short, if you want the most income and the most stability thereof, the evidence, even over short recent periods for newer products, shows covered call funds are probably not the way to go (at least not going all in on them). Only time will tell, though, how that claim matches up with one’s personal retirement horizon, but then that’s my argument for diversifying broadly in the first place…
Let me know what I forgot or if I can clarify anything or answer any questions, but you’ll probably find those answers in existing posts where I’ve already broken all this down into even greater detail:
optimizedportfolio.com/qqqi/
optimizedportfolio.com/jepq/
optimizedportfolio.com/gpiq/


One-way links are still helpful albeit not as much as they used to be.
Swaps are basically worthless and wouldn't be worth the time, effort, and shoehorning.
$OVQ is the newer, Nasdaq-100 cousin to $OVL. It holds the NDX via QQQM at 97%, adds a short put spread overlay on the S&P 500, distributes 12% annually, and costs 0.97%.
Is it worth an extra 0.86% fee compared to 95/5 QNDX/TQQQ, which it resembles, for a small option strategy and having your money handed back to you? You decide.
New post here: optimizedportfolio.com/ovq/

Subscribe to my paid newsletter where I tell you which total market index funds are the cheapest and why they'll beat the stock picks from the other newsletters you're paying for. #sarcasm
Glaring problem with this idea is you could easily end up with a negative return over the life of the loan, probably ~5 years, or more easily, one that lags the loan cost, using equities, which is the popular holding for "income funds."
That's why we say rule of thumb is no stocks for horizon < 5 years. The reason investing in stocks works is because we have a long runway. Recent years have been the exception; they don't indicate the unknowable future.
As usual, just comes down to after-tax total return.
If the numbers work, T-bills would obviously be the most sensible choice here since they're virtually riskless. I described doing so here: youtu.be/oij8c-szRAg
nitter.gq/OptimizedPort/status/2…
"Yourself" is paying for it either way. The only way to "cover" it is if after-tax total return is greater than the loan's interest rate. The "income ETF" aspect is largely irrelevant to the consideration.

Probably one of these: nitter.gq/OptimizedPort/status/2…

CSHI behaves more like short bonds than T-bills and drops precisely when you need cash the most - during stock crashes. I need to do a deep dive on it.
Reminder: $WEEK continues to be the worst way to own T-bills.

A corollary to this, to word it differently, is that solely using dividends means unnecessarily delaying retirement, as you'd have to wait longer til the portfolio grows larger to then draw from a subset of it (just dividends) instead of the whole thing.
You can just glance at the holdings on the official product page: lsfunds.com/etfs/ovq
