

Markets, crypto & AI investing, minus the suits. Building Kyro: every broker, exchange & wallet in one view. Not financial advice.
Worldwide
Joined August 2026
- Tweets552
- Following101
- Followers57
- Likes129
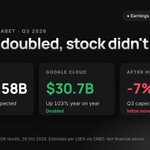


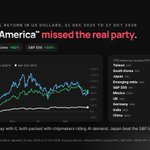


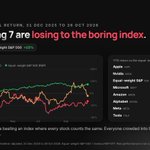


$GOOGL just doubled Google Cloud revenue to $30.7B, and the stock still fell about 7% after hours. Total revenue of $127.58B came in a touch under estimates, GAAP EPS of $2.12 took an $8.7B hit from equity losses, and $51.4B of quarterly capex pushed free cash flow negative. Tonight the market is looking at the spend, not the growth.

$MSFT just put up a clean beat, with revenue of $92.28B vs $90.63B expected and Azure up 48% ex-FX. The surprise is capex at $39.4B, well under the roughly $46B the Street had penciled in. More cloud growth on less spend is exactly what the AI capex worriers wanted to see, and shares are up about 5% after hours.

Ten feels like a lot for forever. Your core, growth and momentum picks are mostly the same megacaps in different wrappers, so it's really more like eight.

Listing is one thing. Coinbase earns a fat cut on USDC, so I'd be surprised if RLUSD gets anything like the same push in the app.
Yeah, the customer base is the cheat code. Every company already pays for Office, so the upsell is basically one email. Renewals after year one will tell us if it's real.
Negative free cash flow at Meta is a sentence nobody would have believed two years ago. The ad machine is basically funding a data center habit now.
Copilot is the bit I'm least sure about. Azure demand kind of sells itself, but getting companies to pay per seat for an assistant is a much harder sell.


Forced selling always looks obvious in hindsight. In the moment it just feels like the floor keeps moving.